

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automotive Sound Insulation NVH Market (Base Year 2025) Poised to Reach USD 21,123.45 Million by 2032 at a 5.85% CAGR

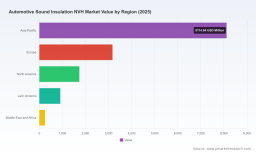
Automotive Sound Insulation & NVH Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
Executive snapshot
PW Consulting today publishes a strategic industry brief that synthesizes quantitative market sizing, regulatory trajectories, technology shifts, and competitive dynamics shaping the Automotive Sound Insulation & NVH (noise, vibration, harshness) market as OEMs navigate the 2026 inflection point. The brief’s macro finding is unambiguous: total industry revenues have expanded from a multi-billion-dollar baseline at the start of the decade to an estimated USD 14.19 billion in the report’s base year (2025), and our model projects continued momentum through the forecast window with a compound annual growth rate of 5.85%. This growth trajectory underscores NVH as both a resilience lever for traditional powertrains and a strategic differentiator for electric vehicle (EV) interiors.
Worldwide Wind Energy Equipment Cabin Bolts Market
Why this brief matters for 2026 decision-makers
- Regulatory deadlines converging in 2026 (notably stricter EU noise limits and the mandatory rollout of updated UNECE R51.03 testing regimes) convert NVH from a comfort optimization to a compliance-critical function. Executives must prioritize investments that mitigate regulatory risk while preserving margin.
- Electrification changes the NVH problem-set: lower powertrain noise raises the relative importance of cabin-born noise paths, body-borne vibration, and ancillary systems. The 2026 planning cycle is the last major window for OEMs and Tier 1s to rebase supplier agreements and engineering roadmaps ahead of model-year 2028 content freezes.
- Market scale and steady growth (CAGR 5.85%) create a favorable environment for technology-led consolidation, targeted M&A, and partnerships that offer material substitution, weight reduction, or mono-material recyclability at scale.
Report composition — what we deliver
PW Consulting’s brief balances executive-ready guidance with rigorous analytical transparency. Key deliverables include:
Battery Liquid Cooler Market
- Independent market sizing: historical series and a granular forecasting engine that explains the drivers behind the transition from the historical baseline to the 2025 base and the projected 2026–2032 trajectory.
- Regulatory impact assessment: a scenario analysis quantifying the commercial and technical implications of EU and UNECE noise standards, with mitigation cost curves and compliance timelines mapped by vehicle architecture.
- Technology deep-dive: performance benchmarking of material classes (rubber compounds, polymer foams, engineered fibers, and hybrid/composite solutions), life-cycle carbon implications, and manufacturing feasibility at OEM volumes.
- Supply chain and cost-to-serve mapping: sourcing risk heatmaps, capital intensity metrics for key manufacturing footprints, and logistics scenarios for nearshoring vs. concentrated sourcing.
- Competitive intelligence and deal flow advisory: profiles, capability matrices, recent initiatives, and M&A archetypes to accelerate inorganic growth or strategic alliances.
- Actionable playbooks: procurement negotiation levers, engineering-to-cost (E2C) approaches for NVH specification harmonization, and a phased implementation roadmap aligned to 2026 compliance milestones.
Competitive landscape — strategic takeaways
The NVH ecosystem remains fragmented by application and material specialization, with the largest incumbent players combining product innovation, vertical integration, and geographic reach. Market concentration metrics indicate moderate aggregation: the top three suppliers capture a meaningful share of revenues, and a top-five cohort controls more than half of the addressable market—conditions that favor scale players in pricing and platform-level adoption.
Worldwide Heavy Duty Steam Rice Cooker Market
Profiles in context: what leading suppliers are doing
- Autoneum Holding AG — A market leader in fiber-based acoustic and thermal management, Autoneum’s recent public showcases emphasize lightweight mono-material carpets and PET-based constructions designed for recyclability and EV-specific comfort. For OEMs seeking low-mass, high-performance cabin architectures, Autoneum’s platform-level solutions reduce integration friction.
- Vibracoustic SE — Specializing in powertrain decoupling and ride-related components, Vibracoustic’s recent supply wins in premium electric truck programs illustrate the continuing relevance of targeted mechanical NVH controls even as electrification reduces combustion-source noise.
- BASF SE and The Dow Chemical Company — Both chemical majors continue to push polymer innovation for microcellular foams, engineered elastomers, and cavity-fill systems. Their material science roadmaps are critical for OEMs that require both acoustic performance and manufacturability at high cycle rates.
- 3M Company — With a portfolio of thin, lightweight acoustic insulators and damping films, 3M remains a go-to supplier for retrofitable and interior surface treatments that help OEMs hit short-term NVH targets without heavy retooling.
- Sumitomo Riko, Henkel, and ElringKlinger — These firms fill strategic niches across mounts, adhesive dampers, and sealing/ acoustics. Their product breadth is particularly valuable for integrators managing cross-domain NVH challenges between powertrain, body, and HVAC subsystems.
Recent signals and what they imply for 2026 planning
- Product showcases and trade shows in 2025 spotlight sustainability and mono-material designs. For procurement and materials teams, this signals a pivot to recyclability criteria in supplier scorecards, not merely unit cost.
- Application wins for EV platforms (notably in premium pickup and utility segments) show that mechanical NVH components retain strategic value. Firms should not assume electrification eliminates demand for mounts, air springs, or engineered bushings—rather, specifications shift.
- Regulatory timing is non-negotiable: with enhanced urban noise weighting and high-load testing phased in by mid-2026, engineering groups must accelerate validation cycles for any new NVH material or architecture that has not yet completed certified testing.
Strategic implications — prioritized actions for 2026
- Embed NVH as a cross-functional KPI. NVH must sit alongside weight, cost, and emissions in platform scorecards. Assign accountable owners in R&D and product planning and align supplier contracts to outcome-based acoustic metrics.
- Advance material substitution pilots now. Given the projected growth and regulatory berth, short pilots on mono-material carpets, engineered PET felts, and low-density microcellular foams can de-risk qualification timelines and provide bargaining leverage in 2027 purchasing cycles.
- Re-evaluate supplier portfolios through a compliance-and-sustainability lens. The market’s moderate concentration rewards strategic partnerships with Tier 1 leaders that can guarantee scale, but niche suppliers can be critical for differentiated NVH performance—use targeted M&A or JV structures to secure capabilities.
- Prepare for testing regime changes. Update validation benches and acoustics labs to reflect UNECE R51.03 Phase 3 test profiles; plan for iterative certification cycles and allocate capex for accelerated test throughput.
- Monetize NVH as a value lever in marketing for EVs. Quiet cabins are a brand differentiator; coordinate product, marketing, and dealer channels to translate acoustic performance into perceived quality premiums.
Risk matrix & upside scenarios
The primary near-term risks to planned investments are: prolonged supplier qualification timelines, raw-material price volatility affecting foam/elastomer margins, and delayed regulatory clarifications in non-EU jurisdictions. Offsetting upside scenarios include faster-than-expected adoption of lightweight bio-based fibers and broader OEM willingness to pay for superior acoustic differentiation in premium segments. PW Consulting’s scenario suite quantifies these levers and maps their P&L sensitivity for both OEMs and Tier suppliers.
How PW Consulting supports executive decisions
Our brief is designed to be a decision-ready instrument for C-suite and business-unit leaders preparing 2026 budgets and 2027 product commitments. We pair market analytics with negotiation playbooks, supplier scorecards, and an M&A shortlist methodology tailored to NVH. For organizations pursuing more bespoke support, PW Consulting offers accelerated workshops that convert the brief’s strategic recommendations into executable 90–180 day plans, including sourcing pilots, laboratory upgrades, and alliance negotiations.
Next steps — where to find the full intelligence
This release is an executive preview intended to surface the most consequential trends and recommended actions as stakeholders prepare for regulatory and market inflection in 2026. The full report contains the complete forecasting model, detailed supplier profiles, segmented demand drivers, cost-to-serve matrices, and downloadable scenario tools. To access the comprehensive dataset, confidential company deep dives, and tailored advisory options, please visit PW Consulting’s Automotive Sound Insulation & NVH report page or contact our advisory team for a briefing and sample extracts.
Closing thought
As NVH shifts from a differentiator to a compliance-anchored discipline in the coming 12–18 months, companies that integrate acoustic strategy into platform planning — and treat materials and supplier selection as strategic investments rather than line-item costs — will capture both regulatory resilience and customer-perceived quality premiums. PW Consulting’s brief equips leaders to make those trade-offs with clarity and urgency.
For detailed analysis of this topic, please visit the official page: Automotive Sound Insulation NVH Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com