

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Car Entertainment Systems to hit USD 345.4M by 2032 at 6.98% CAGR

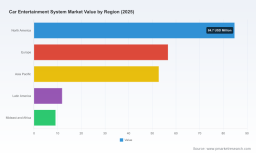
Car Entertainment System Market: Strategic Imperatives for 2026
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a focused preview of our latest Car Entertainment System Market study — a strategic briefing designed to shape executive decisions in 2026. The market has entered a new phase: from a recovery and digital-integration cycle in the early 2020s to a sustained expansion driven by software-defined vehicle architectures, immersive in-cabin experiences, and tighter integration between infotainment and safety domains. Using 2025 as the base year, our modeling shows the global market expanding from approximately USD 163.15 Million in 2020 to USD 215.0 Million in 2025 and forecasted to reach USD 345.4 Million by 2032, representing a compound annual growth rate (CAGR) of 6.98% across the 2026–2032 period. This trajectory creates windows of opportunity — and distinct execution risks — that require targeted strategic action in 2026.
Car Entertainment System Market
Why this study matters for 2026 decision-makers
-
Timing of platform bets: The industry is shifting from hardware-led differentiation to software- and services-led differentiation. OEMs and Tier‑1 suppliers who decide on platform architectures and software partnerships in 2026 will lock in multi-year product roadmaps and partner ecosystems.
Car Entertainment System Market -
Monetization inflection: Subscription models, over‑the‑air (OTA) feature rollouts, and aftermarket upgrade pathways are moving from pilot projects to commercial programs. Strategic choices on pricing, feature bundling, and revenue-sharing will materially affect lifetime value.
Car Entertainment System Market -
Certification and regulatory alignment: New certification frameworks for Android Automotive and AAOS-based IVI systems introduce compliance overheads and preferred testing routes—decisions on where and how to validate systems now carry program-level implications.
-
Consolidation and supplier strategy: The market remains relatively fragmented (CR3 ~24.6%; CR5 ~26.2%), creating a dual dynamic — room for niche innovation and an attractive runway for consolidation. Strategic M&A, joint ventures, or exclusive supply agreements could be decisive moves in 2026.
What the full report delivers (actionable, not academic)
-
Proprietary market sizing and forecasting model (base year 2025; historic tail to 2020; forecast 2026–2032) with scenario outputs for high/medium/low adoption pathways, enabling sensitivity analysis for CAPEX and revenue planning.
-
Technology radar that ranks platform approaches (native AAOS vs. proprietary stacks), audio and display innovations (spatial audio, HDR certifications), SoC integration strategies, and connectivity/vehicle domain convergence.
-
Commercial playbooks: OEM vs. aftermarket go‑to‑market templates, pricing and subscription frameworks, partner selection checklists, and go/no-go gates for feature monetization pilots.
-
Operational toolkits: supplier sourcing scorecards, qualification matrix for IC and SoC partners, certification roadmaps (including Android Automotive/AAOS testing), and a compliance impact matrix for procurement and quality teams.
-
M&A and partnership playbook: valuation benchmarks, consolidation scenarios, and integration risk checklists tailored to the current fragmentation levels and competitive dynamics.
-
Risk scenarios and mitigation: supply-chain shocks, software security incidents, regulatory shifts, and consumer-UX adoption hurdles — each with contingency plans and milestones for 12‑ to 36‑month horizons.
Competitive landscape: how to read incumbent moves
Our competitive analysis focuses on strategic positioning, software and ecosystem relationships, product roadmaps, and commercial reach. Below are the key players and the implications of their recent moves.
-
Harman International (Stamford, CT) — Strengths: premium connected systems, immersive audio, integrated UX. Strategic signal: Harman’s industry-first HDR10+ automotive certification (announced late 2025 / reinforced in 2026) is evidence of investment in media-quality differentiation and OEM co-development for premium segments. For partners, Harman represents a platform play for experiential, content-driven monetization.
-
Pioneer Corporation (Tokyo) — Strengths: aftermarket leadership, navigation and audio systems. Strategic signal: Pioneer’s SPHERA (early 2026) — an aftermarket in-dash receiver embedding Dolby Atmos into Apple CarPlay — underscores the aftermarket as a rapid-prototyping ground for advanced audio UX and a channel to capture incremental consumer spend. OEMs should watch aftermarket innovations as demand signals for future OEM features.
-
DENSO TEN Limited (Kobe) — Strengths: AV products and automotive electronics. Strategic signal: DENSO TEN continues to play the classic Tier‑1 role — integrating hardware reliability with evolving software stacks — making it a candidate partner for OEMs prioritizing integration depth and production-grade quality.
-
Panasonic Automotive Systems (Yokohama) — Strengths: in‑vehicle infotainment, navigation, premium audio. Strategic signal: Panasonic’s systems remain attractive to OEM programs that seek end‑to‑end integration across cabin subsystems and premium UX. The firm’s focus on modular IVI platforms supports faster OEM time-to-market.
-
Mitsubishi Electric Automotive America (Northville, MI) — Strengths: connected infotainment, integrated cockpit, rear-seat entertainment. Strategic signal: Mitsubishi Electric is positioned to capture platforms that require heterogeneous cockpit experiences across occupant zones — a growing demand vector as vehicle interiors become multi-purpose spaces.
-
Bosch (Stuttgart) — Strengths: infotainment ECUs, central computing, connectivity. Strategic signal: At CES 2026 Bosch demonstrated a fusion of infotainment and driver assistance on a single SoC-based cockpit & ADAS integration platform. That convergence underscores a strategic tilt toward domain consolidation — a structural shift that will redefine supplier boundaries and integration complexity.
-
Continental AG (Hanover) — Strengths: information management, connectivity solutions. Strategic signal: Continental remains a key systems integrator; its strength in connectivity and data management positions it for roles in vehicle-to-cloud monetization and centralized cockpit services.
Additional market activity (e.g., Fiacre Telematics’ showcase of commercial-vehicle infotainment at mobility expos) evidences niche growth vectors where customized solutions and regional regulatory alignment matter most.
Regulatory and certification dynamics to watch in 2026
-
P3 Group’s role as Google’s third‑party laboratory for Android Automotive testing and the formalization of AAOS certification frameworks creates a de facto gate for many OEMs and suppliers. This reduces technical ambiguity but raises program costs and time-to-certification.
-
Practical implication: product teams must bake AAOS test plans into development sprints, and procurement must select certified test partners early to avoid downstream delays. The report includes an executable certification checklist and vendor selection rubric.
Priority strategic moves for 2026
-
Embed software-first thinking into product roadmaps: Move from one-off feature launches to modular, OTA-enabled platforms with clear update governance and rollback plans.
-
Lock in certification pathways early: Allocate budget and program timelines for AAOS certification and preferred third‑party lab engagements.
-
Define clear monetization experiments: Pilot subscriptions and feature tiers in targeted regions or customer segments; instrument pilots to capture conversion and churn metrics.
-
Prioritize integrations that reduce system complexity: Consider consolidation of cockpit domains where safety‑critical and infotainment workloads converge; evaluate SoC partners with demonstrated multi-domain performance.
-
Build strategic partnerships across the ecosystem: app-platform providers, cloud service vendors, audio content partners, and certified test labs — not just hardware vendors.
-
Use M&A selectively to accelerate capability gaps: With modest top-5 concentration, tuck-in acquisitions or JV structures can quickly secure software talent, content deals, or aftermarket distribution.
-
Invest in cybersecurity and privacy-by-design: With increasing vehicle connectivity, embedded IVI systems are high-value targets; security investments must be part of the product budget, not an afterthought.
How PW Consulting can accelerate your 2026 program
Our full Car Entertainment System Market report is built as an execution guide: downloadable financial models, procurement scorecards, certification roadmaps, a partner‑selection matrix, and scenario-based investment cases tuned to the 2026 decision calendar. The public preview you’re reading now intentionally omits granular segment breakouts and granular regional/application-level revenue tables — those detailed splits and program-level benchmarks are included in the subscriber report to preserve commercial integrity and to give paying clients immediate, prioritized value.
If your 2026 roadmap requires defensible investment cases, faster certification, or a market-entry playbook for OEM and aftermarket channels, the full study provides the templates and advisory engagement options to convert strategic intent into milestones and measurable outcomes.
In short: the Car Entertainment Systems market is growing, recentering around software and experiential differentiation, and is opening strategic windows for firms that move decisively in 2026. Our report tells you where to place those bets and how to reduce execution risk — with the granular segment data and region/application splits available in the full release.
For detailed analysis of this topic, please visit the official page: Car Entertainment System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com