

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Chemical & Materials
PW Consulting: C9 Petroleum Resin Market to Reach USD 2,402.4 Million by 2032 at a 4.85% CAGR; Asia Pacific Holds USD 821.7 Million in 2025
By pmarketresearch, 2026-07-07
C9 Petroleum Resin Market: Strategic Imperatives for 2026 — PW Consulting
The C9 petroleum resin market is entering a decisive phase as legacy feedstock dynamics, evolving end‑use demand, and incremental product innovation reconfigure competitive advantage. Using 2025 as our base year, PW Consulting’s C9 Petroleum Resin Market Report synthesizes a continuous historical series (2020–2025) with a forward‑looking model (2026–2032) to quantify opportunity and risk. The global market grew from the low‑thousands (USD Million) at the start of the decade to an estimated USD 1,724.5 Million in 2025 and is forecast to expand at a compound annual growth rate (CAGR) of 4.85% through 2032, reaching roughly USD 2,402.4 Million by the end of the projection period. This briefing summarizes the strategic value the report delivers for decisions you will make in 2026 — while intentionally withholding the full proprietary segment-level tables to encourage direct review of the primary analysis and models.
C9 Petroleum Resin Market
Why this report is material to 2026 corporate decisions
-
Actionable clarity for capital allocation. Our integrated demand‑supply and margin model translates feedstock scenarios into expected cash‑on‑cash outcomes for new plant investments, debottlenecking and retrofits.
C9 Petroleum Resin Market -
Procurement and risk management playbook. The report maps the sensitivity of resin margins to upstream naphtha/C9 fraction swings and provides hedging and contract structures that midstream and downstream players can adopt immediately.
C9 Petroleum Resin Market -
M&A and partnership prioritization. We identify where scale, feedstock security, or proprietary grades translate into premium valuation multiples, and where bolt‑on acquisitions can be de‑risked by technology or customer overlaps.
-
Commercial and product stratification. The analysis gives revenue‑mix templates that help sales and innovation teams prioritize hydrogenated and specialty grades where value capture is highest.
-
Regulatory and sustainability readiness. Our regulatory appendix clarifies current risk profiles and tactical steps to prepare for evolving REACH/TSCA expectations and downstream customer requirements.
Core market dynamics that will shape 2026 outcomes
-
Feedstock architecture is the single largest strategic variable. C9 petroleum resins are produced from the aromatic C9 fraction, itself a byproduct of steam cracking. A structural shift in cracker feedstock mix — notably the move from naphtha to ethane — materially reduces C9 byproduct availability per unit of ethylene output. For integrated producers and merchant resin manufacturers alike, this alters feedstock security, margin volatility and the calculus on vertical integration.
-
Volatility transmission from upstream to resin margins. Historical episodes of naphtha and C9 fraction price spikes show rapid pass‑through to resin pricing, but with lags and differential exposure for thermal vs catalytic vs hydrogenated process routes. Our scenario workbench models multiple volatility regimes to quantify downside for unhedged players.
-
Regulatory posture is largely permissive today — hydrocarbon resins are assessed as low hazard in several recent regulatory evaluations and often qualify for polymer reporting exemptions. Nonetheless, expanded scrutiny on lifecycle emissions and chemical footprints means producers should proactively document supply chain emissions and impurities ahead of customer demands.
-
Incremental product innovation is a differentiator. Hydrogenation, catalytic control and crosslinkable formulations are moving from lab to commercial practice; producers that can cost‑effectively scale higher‑value grades will capture better margins even in a moderately consolidated market.
Demand structure and substitution vectors
Demand remains anchored in adhesives & sealants, paints & coatings, printing inks and rubber compounding — each exhibiting different sensitivity to resin grade, supply security and technical performance. Structural tailwinds include growing industrial and construction activity in selected geographies and an uptick in specialty formulations that demand more refined resin grades. At the same time, substitution risk exists from alternative tackifiers and polymer systems, particularly where formulators prioritize low VOC or bio‑based claims. PW Consulting’s market model flags which end‑use pockets are most likely to pay a premium for upgraded resin chemistries and which are likely to remain price‑sensitive.
Supply-side structure and competitive posture
The C9 resin market shows a moderate level of concentration, with the largest groups collectively holding a material share of capacity while a diversified base of regional and specialty producers supply local markets and niche grades. This balance creates both margin compression in commoditized segments and sustained premium capture for differentiated technologies and secure feedstock positions.
-
Kolon Industries (South Korea) — a domestic leader with unique proprietary formulations in aromatic and aliphatic resins and an early mover in crosslinkable hydrocarbon resins. Their playbook centers on formulation partnerships with adhesives and coating customers.
-
Neville Chemical Company (USA) — long‑standing USA producer with a strategic emphasis on secure domestic supply and technical service for high‑performance coatings and adhesives customers.
-
Eastman Chemical Company (USA) — brings integrated production and a broad hydrocarbon resin portfolio; positions itself to convert scale into global account penetration.
-
Cray Valley / TotalEnergies (France / USA) — global reach with continuous investments in resin technology and customer support, emphasizing specialty grades for inks and adhesives.
-
Chinese manufacturers (multiple) — a cluster of domestic producers who compete aggressively on price and supply flexibility for regional customers; several are advancing higher‑margin grades and export footprints.
-
ExxonMobil (USA) — integrated feedstock advantage; their resin strategy leverages upstream cracker economics and global commercial channels.
-
Arakawa Chemical (Japan) — steady provider with strong technical service in Asia and a focus on coating and adhesive segments.
Practical implications and recommended moves for 2026
-
Reassess feedstock strategy within 90 days. Firms should stress‑test existing contracts against at least three cracker feedstock scenarios (naphtha‑centric, mixed, ethane‑centric) and quantify the margin and supply risks for each production route.
-
Prioritize flexible production and premium grades. Capex planning should favor modular upgrades that enable shifts between thermal, catalytic and hydrogenation routes to capture premium demand without committing to single feedstock exposure.
-
Lock in strategic customer partnerships. Longer‑term off‑take arrangements with formulators in adhesives and coatings can de‑risk new capacity and support premium pricing for specialty grades.
-
Integrate sustainability disclosure into commercial terms. Collect upstream emissions and impurity data now to avoid last‑minute compliance costs and to position products for green‑premium procurement.
-
Use M&A selectively to acquire technology or feedstock security. Smaller bolt‑on plays that bring hydrogenation or crosslinkable tech, or that secure access to C9‑rich streams, are higher‑value targets than broad geographic roll‑ups.
-
Deploy dynamic pricing and analytics. Use near‑real‑time feedstock indices and customer elasticity models to move beyond static annual contracts.
What PW Consulting’s report delivers (practical, executable content)
The full report is structured to be actionable within procurement, strategy, R&D and commercial teams. Key deliverables include:
-
A bottom‑up market model covering 2020–2032 with scenario toggles for cracker feedstock mix, margin sensitivity, and end‑use demand elasticity.
-
Price and margin dashboards that translate upstream price movements into expected resin price bands and margin outcomes for thermal, catalytic and hydrogenated routes.
-
Competitive company dossiers with strategic SWOTs, capability maps and a decision matrix for partnership or M&A targets.
-
Technology and product roadmaps describing commercialization timelines and expected cost curves for higher‑value resin grades.
-
Regulatory and sustainability playbook summarizing current low‑hazard assessments plus recommended disclosure templates for customer use.
-
Commercial templates — 100‑day go‑to‑market plans, procurement contracting language, and capex evaluation checklists aligned to our scenario outputs.
How to use the report in 2026 boardroom discussions
-
Bring the scenario results to your next strategy offsite. Use our ethane vs naphtha scenarios to stress‑test your most capital‑intensive options and to set trigger points for investment.
-
Make procurement the owner of feedstock risk. Assign KPIs tied to margin leakage from feedstock volatility and deliver monthly flash reporting using our index templates.
-
Set a clear R&D milepost for upgraded grades. If you are aiming to commercialize hydrogenated or crosslinkable resins, map out a two‑year commercialization timeline with key customer validation gates.
-
Use the competitive dossiers to prioritize alliance or acquisition targets. Focus diligence on feedstock access, proprietary process IP, and customer stickiness instead of headline capacity alone.
Final note — why this is a “must‑read” before committing 2026 resources
Decisions made in 2026 will lock in feedstock exposure, product mix and commercial positioning for the better part of the decade. PW Consulting’s C9 Petroleum Resin Market Report turns opaque upstream dynamics and fragmented commercial signals into a clear set of strategic choices, modelled with scenario rigor and commercial immediacy. We present the analytical foundation you need to make defensible capital, procurement and product decisions — while reserving full proprietary segment tables and company‑level metrics for the complete report to preserve the actionable advantage for subscribers.
Access the full analysis
For access to the detailed datasets, proprietary segmentation, downloadable model, and the competitive dossiers referenced above, request the full C9 Petroleum Resin Market Report from PW Consulting. The full report contains the segment‑level splits, granular regional and application forecasts, and downloadable model files that support boardroom‑ready decision packages for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: C9 Petroleum Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pseudoboehmite Market Tops USD 654.6 Million in 2025, Forecast to Reach USD 934.7 Million by 2032 at a 5.22% CAGR
By pmarketresearch, 2026-07-07
Pseudoboehmite Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
Executive summary
PW Consulting's new Pseudoboehmite Market study (base year 2025; historical 2020–2025; forecast 2026–2032) frames a rapidly maturing specialty alumina market that is consequential for upstream feedstock managers, catalyst and adsorbent manufacturers, and downstream refiners and chemical producers planning capital and procurement decisions in 2026. Our analysis shows the global market expanding at a compound annual growth rate (CAGR) of 5.22% through 2032, with measured expansion from approximately USD 512.5 million in 2020 to USD 654.6 million in 2025 and a projected market size approaching USD 935 million by 2032.
Pseudoboehmite Market
Why this report matters for 2026 corporate decision-making
- Timing of investment: Producers and buyers must align capacity, product qualification and offtake agreements to the mid-cycle phase that begins in 2026 — when feedstock softness and demand rebalancing create both margin pressure and selective opportunity.
- Procurement and cost engineering: Procurement teams need forward-looking price decks and scenario-based hedges for aluminium hydroxide and bauxite inputs; this report provides the quantitative levers and risk matrices to operationalize that hedging across 12–36 month horizons.
- Product and portfolio strategy: The next 24 months separate commodity suppliers from specialty, high-purity or tailored-pore pseudoboehmite producers. Decisions on R&D, product certification, and co-development with catalyst formulators will determine premium capture.
- M&A and partnership roadmap: Mid-market consolidation and strategic alliances—especially between Western specialty manufacturers and Chinese capacity holders—are likely to accelerate. The report outlines target profiles and value-capture mechanics for active and passive investors.
Report scope and actionable content (what’s inside)
- Comprehensive market sizing and a validated top-down/bottom-up forecast (2026–2032) with scenario sensitivity to feedstock price shocks and downstream petrochemical cycles.
- Supply chain heat maps and capability assessments, including plant technology differentiation (alkoxide hydrolysis, PHS series upgrades, dispersion technologies) and typical qualification timelines for catalyst/adsorbent customers.
- Price-driver modelling for upstream inputs and a procurement playbook that translates raw-material pathways into margin-impact levers.
- Competitor benchmarking and strategic profiles of leading producers, with strengths, product portfolios, and go-to-market strategies synthesized into acquisition and partnership playbooks.
- Regulatory and ESG checklists tied to permitting, environmental audits, and social impact considerations that materially affect project timelines and insurance/capital costs.
- Executive-ready strategic recommendations and three investment/operational scenarios (Base, Upside, Downside) tailored for 2026 decision calendars.
Note: To preserve the utility of this public summary we intentionally withhold detailed regional and application splits, price decks and company-level revenue breakdowns; these are available in the full report.
Pseudoboehmite Market
Market dynamics and raw-material context driving 2026 outcomes
Pseudoboehmite sits at the intersection of refined alumina chemistry and downstream catalyst engineering; as such, midstream feedstock movements directly affect margins and strategic posture. Our short-term tracking identified a notable softening in aluminium hydroxide prices in early 2026, with Northeast Asia experiencing a pronounced decline versus late 2025 and European prices easing more moderately. Bauxite CIF flows into China and the U.S. import price index also reflect loosening upstream cost pressure.
Pseudoboehmite Market
These shifts create a tactical window in 2026: buyers can negotiate improved terms for multi-year supply contracts, while sellers must accelerate differentiation—either through higher-purity grades, enhanced dispersion technology, or integrated catalyst development—to defend pricing. At the same time, volatility in feedstock markets means capacity additions should be staged and underpinned by binding offtake or technology lock-ins to avoid mid-cycle oversupply.
Competitive landscape — who matters and why
The pseudoboehmite market displays moderate concentration: our competitive metrics show that the top three players hold a material portion of the market, with a top-five concentration approaching three-fifths of global volumes. This structure creates both strategic friction and opportunities:
- Sasol Limited — expert in high-dispersion, high-purity pseudoboehmite via alkoxide hydrolysis; well-positioned for catalyst carrier applications in refining and petrochemicals. Their DISPERAL capability underscores a technology-led premium route.
- CHALCO (Aluminium Corporation of China) — scale producer with recent major project certifications and an upgraded PHS series production approach targeting hydrocracking and related catalyst feedstocks. Recent environmental and social assessments and ASI audit outcomes indicate a focus on compliant capacity expansion.
- Honeywell UOP — supplies Versal and related alumina intermediates; strength lies in deep integration with adsorbent and catalyst OEMs, translating product spec control into supply stickiness.
- Nabaltec, Almatis, BASF — European specialty and premium-supply players focusing on niche grades, flame-retardant additives, and high-performance catalyst carriers, which command differentiated margins.
- Chinese and regional specialists — a cohort of dedicated producers concentrated in Shandong and other industrial clusters supplies significant volume and capability for rapid scale-up; their strategies range from commodity volume plays to targeted high-purity and macroporous variants for molecular sieves and catalysts.
Strategically, buyers should evaluate three supplier archetypes when structuring 2026 engagements: (1) Technology-led, premium suppliers with long qualification cycles; (2) Scale-focused producers offering competitive base-grade volumes; (3) Regional specialists providing fast-response capacity but variable long-term reliability. The full report ranks individual firms against these archetypes and includes readiness checklists for qualification and supplier risk.
Regulation, certification and ESG — an operational must for 2026
Environment and social governance considerations are increasingly gatekeepers for project greenlighting and bankable financing. An illustrative case: Chalco Shandong's 10,000 tpa PHS series upgrade completed environmental approvals and an Aluminium Stewardship Initiative audit, and maintained ISO 14001:2015 and ISO 45001:2018 certifications — steps that materially shorten commercial ramp timelines and broaden financing options. Buyers and investors should factor certification status into counterparty selection and contract terms.
Strategic playbook: five priorities for 2026
- Lock in flexible supply, not just price: Negotiate contracts with adaptive volume bands and material-replacement clauses tied to qualification status. Prioritize suppliers who offer staged delivery tied to performance milestones.
- Differentiation through specification: Invest in co-development with catalyst formulators to secure exclusivity on high-purity or tailored-pore grades; even modest specification premiums compound materially over multi-year contracts.
- Hedge feedstock exposure: Use the report’s price-driver models to design layered hedges for aluminium hydroxide and bauxite exposure, combining physical call options, indexed pricing collars and strategic inventory buffers.
- Selective M&A and JVs: Focus acquisition targets on technology (dispersion/alkoxide platforms) and regional capacity that fills logistical gaps; JV structures should embed technology transfer and binding offtake to de-risk greenfield capex.
- ESG and permitting as competitive advantage: Make environmental certification and human-rights due diligence a pre-requisite for strategic suppliers; engaging early reduces timeline uncertainty and can shorten payback periods by improving access to capital.
Methodology and confidence factors
This study synthesizes primary interviews, plant-level capacity audits, trade and customs data, and proprietary pricing models. We reconcile top-down macro indicators with bottom-up plant output and company-reported capacities to produce scenario-tested forecasts. Sensitivity testing highlights three principal levers that explain >80% of forecast variance: downstream petrochemical demand, aluminium hydroxide feedstock price, and the pace of specialty-grade adoption. Our confidence bands are disclosed in the full dataset and are calibrated to permit rolling updates as 2026 data materialize.
How to use this research
Market leaders and investors should treat this brief as a strategic primer: it identifies the decision points and time windows that will determine value capture through the 2026 cycle. For procurement teams, the report delivers the price decks and contract templates needed to convert analysis into defensible purchase strategies. For corporate development and investors, our M&A playbook and target scoring system convert market intelligence into executable deal lists.
Next steps — access to the full intelligence
This communiqué follows the "trailer" principle: it presents the analytical framework, strategic implications and validated market trajectory, while preserving the detailed segmentation tables, supplier revenue splits, and full price-deck models for subscribers. To operationalize the recommendations above — including supplier scorecards, region/application breakouts, and scenario-specific Excel models — please consult the full PW Consulting Pseudoboehmite Market report. The full report contains the granular data and transaction-ready appendices you will need to finalize 2026 budgets, procurement RFPs, and investment decisions.
For detailed analysis of this topic, please visit the official page: Pseudoboehmite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sulphur Pastilles Market Valued at USD 1,045.5 Million in 2025 to Expand at 4.12% CAGR (2026–2032)
By pmarketresearch, 2026-07-07
Sulphur Pastilles Market — 2026 Strategic Brief
Executive snapshot
PW Consulting’s latest market study on Sulphur Pastilles synthesizes five years of historical behaviour (2020–2025) and delivers a commercial roadmap for 2026–2032. The global market reached approximately USD 1,045.5 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 4.12% over the forecast period, with expected market size rising into the mid‑teens of hundreds of millions by 2032. For executives planning investments, procurement strategies, or M&A activity in 2026, the report frames the macro trajectory clearly while preserving the transaction‑level detail you need to act.
Sulphur Pastilles Market
Why 2026 is a strategic inflection year
-
Post‑pandemic demand normalization in core applications (fertilizer manufacturing, chemical processing and specialized industrial uses) has intersected with acute raw material price volatility, creating a period of compressed margins and selective opportunity.
Sulphur Pastilles Market -
Regulatory clarifications in major transport regimes have reduced logistics friction for formed sulphur products shipped in non‑bulk packaging — lowering barriers for rapid regional redeployment but increasing competition around service and reliability.
Sulphur Pastilles Market -
Market concentration remains meaningful: the top producers collectively hold a material share of supply, creating both risk of supply squeeze and pockets of competitive advantage for scale players. Our concentration analysis shows a moderate degree of consolidation among the highest‑volume suppliers, informing counterparty risk assessments and sourcing strategies.
What the PW Consulting report delivers (practical, transaction‑grade intelligence)
-
Market sizing and forecasting: validated top‑line market values (2020–2025 historical, 2026–2032 forecast with scenario bands) and growth drivers mapped to commercial KPIs.
-
Pricing & cost dynamics: rolling price curve analysis and sensitivity models that link feedstock sulphur prices to finished‑product margins and breakeven maps for different production technologies.
-
Supply chain heat‑maps: mill‑level and port‑level routing analytics, lead‑time distributions, and a supplier reliability index to prioritise sourcing lanes.
-
Commercial playbooks: procurement tactics (spot vs contract blend strategies), inventory thresholds tied to working capital optimization, and contract clause templates for volatility pass‑through and quality assurance.
-
Competitive & M&A landscape: strategic profiles, capability matrices, and a shortlist of opportunistic M&A targets and bolt‑on acquisition criteria for 2026 deployment.
-
Regulatory & logistics compendium: jurisdictional transport guidance, HSE triggers and a decision tree for packaging and movement that minimises compliance risk while retaining commercial flexibility.
-
Scenario playbooks: three executable scenarios (base, upside, downside) with actionable contingency plans for producers, traders and large‑scale consumers.
Data‑driven market dynamics you need to factor into 2026 plans
Our analysis synthesises price feeds, trade flows and plant utilisation to show how upstream sulphur feedstock moves through to pastilles. Price volatility has been pronounced in early 2026: regional price markers and spot indices show rapid month‑on‑month swings and significant year‑over‑year gains in several markets. This volatility materially affects cash margins for both industrial and agricultural grades, and it alters the economics of different product forms (e.g., pastilles vs. flakes) and logistics options (bulk vs. bagged shipments).
At the same time, transport regulation interpretations in multiple jurisdictions have effectively de‑risked certain non‑bulk shipments of formed sulphur, lowering compliance costs for bagged pastilles. This is a tactical lever: suppliers who can certify shape, moisture and packaging standards capture lower transport tariffs and faster customs clearances, improving delivery lead times for buyers willing to accept slightly higher unit prices for reliability.
Competitive landscape — who matters and why
The sector comprises established chemical producers, regionally dominant manufacturers and nimble specialist fabricators. PW Consulting evaluated operational footprints, product portfolios, technical differentiators and go‑to‑market models for leading firms. Highlights of companies covered in the study:
-
Martin Midstream Partners L.P. (USA) — Integrated production at multiple North American sites positions the company for domestic industrial supply and blended MP (Multipurpose Sulfur) offerings. The combination of multiple facilities and logistics assets is a defensive moat for large‑volume buyers seeking secure supply.
-
Coogee Chemicals (Australia) — Strong regional logistics and chemical handling expertise make Coogee a preferred partner for industrial consumers across Australasia, especially where inland distribution and regulatory know‑how are mission critical.
-
Tiger‑Sul (Tessenderlo Kerley Inc., USA) — A global footprint for industrial‑grade pastilles and value‑added forms (bentonite blends, micronutrient variants) that appeals to specialist end‑users and formulators. Their international processing and warehousing capability is a differentiator for global supply chains.
-
Georgia Gulf Sulfur Corporation (USA) — Known for rotoform technology producing uniform formed pastilles, Georgia Gulf’s technical capability serves buyers with strict particle‑size and flowability requirements.
-
Grupa Azoty (Poland) — An integrated producer with standardised product specs and outdoor handling systems suited to industrial supply contracts in Europe and neighbouring regions.
-
NEAIS / Said Ghodhran Group (Saudi Arabia) — Regionally significant producer using drop‑forming technologies targeted at agricultural and industrial markets in the Middle East and Africa.
-
Regional specialists and aggregators such as Swancorp, Devco Australia, Brimfert, Passion Ag, BTSCO and Petro Arkan — these companies deliver local market agility, niche technical propositions and cost‑efficient logistics for specific applications.
Strategic implications and recommended actions for 2026
-
Hedge selectively and design flexible contracts: Given price volatility, adopt a layered procurement approach — a base of contracted volumes with indexed clauses plus opportunistic spot purchases. Use the report’s pass‑through templates to reduce margin squeeze.
-
Prioritise supplier resilience over lowest price: The supplier reliability index in our study shows that small differences in on‑time performance can lead to disproportionate production downtime costs. For critical SKUs, prefer suppliers with diversified terminal access and established contingency stock arrangements.
-
Invest in packaging & logistics compliance: Where regulatory interpretations favour non‑bulk packaging, incremental CAPEX in certified bagging and QA reduces transport premiums and shortens lead times — a rapid ROI for mid‑sized traders and producers.
-
Targeted M&A and partnerships: For upstream players, acquire or partner with regional fabricators to secure downstream placement and faster market access; for traders, align with producers offering value‑added blends to capture higher margin segments.
-
Product & application diversification: Developers of micronutrient‑enhanced or tailored particle sizes can command premium pricing and lock in long‑term offtake contracts with agronomists and specialty chemical formulators.
-
Operational readiness for price spikes: Maintain a short list of alternate suppliers and pre‑negotiated transshipment options to manage sudden regional supply shocks driven by feedstock disruptions or logistic bottlenecks.
Why PW Consulting’s report becomes a 2026 decision‑making tool
Our study transforms raw market indicators into operational choices. It pairs top‑line forecasting with supplier‑level intelligence, contract templates, and tactical procurement playbooks — the elements business leaders need to convert market signals into defensible, cash‑accretive actions. The report is intentionally structured as a decision support system for 2026: not just numbers, but executable moves linked to measurable KPIs.
Next steps
-
For a complete set of segmented tables, supplier maps, pricing curves and the full set of tactical templates referenced in this brief, access the full Sulphur Pastilles Market report on the PW Consulting portal.
-
Contact our advisory desk for a tailored 90‑minute executive briefing where we overlay your P&L and procurement footprint on the report’s scenarios and deliver a customised action plan for Q2–Q4 2026.
PW Consulting — Bringing market clarity to strategic choices. For the full intelligence suite, supplier shortlists and modelled decision trees, visit our report page or request a direct briefing.
For detailed analysis of this topic, please visit the official page: Sulphur Pastilles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ocean Wave Energy Market Poised for Rapid Expansion — Forecasted 16.52% CAGR
By pmarketresearch, 2026-07-07
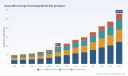
Ocean Wave Energy Technology Market — Strategic Preview for 2026 Decision-Makers
Executive summary
As governments and utilities accelerate decarbonization pathways, ocean wave energy is transitioning from niche pilots to commercially credible projects. PW Consulting’s new market study — grounded on a 2025 base year and projecting through 2032 — quantifies this transition and provides the operational playbooks that executives, project developers, investors, and policymakers need to make high‑confidence decisions in 2026.
Ocean Wave Energy Technology Market
At the macro level, the global ocean wave energy market has more than doubled in reported revenue since 2020 and is forecast to expand at a compound annual growth rate (CAGR) of approximately 16.5% across the 2026–2032 forecast window. This trajectory reflects a convergence of maturing device designs, targeted public funding, emerging commercial offtake mechanisms, and early evidence of sustainable operations cost profiles. Importantly, while the sector remains fragmented with a moderate degree of concentration among the leading technology providers, the pace of scale‑up in key markets creates clear windows for strategic entrants and incumbents alike.
Ocean Wave Energy Technology Market
Why the report matters for 2026 corporate strategy
- Timing: 2026 is a pivotal year for first commercial array deployments and test‑site commercialization. Decisions made this year on partner selection, site contracting, and supply‑chain commitments will materially influence 2027–2029 cost trajectories and equity returns.
- Capital allocation: The market profile in our study translates technology readiness and operational risk into investable scenarios. That enables CFOs and investment committees to compare probabilistic IRR outcomes across device classes, geographies, and business models.
- Policy leverage: New and scheduled public programs — including sizable competitive grants and infrastructure support — change the economics for early movers. Incorporating these into commercial negotiations and project timelines is now table stakes.
Market trajectory — the numbers that drive boardroom decisions
PW Consulting’s topline time series tracks the market from a modest commercial base in 2020 to accelerated commercial activity by 2025 (base year). The study documents a clear inflection: market revenue more than doubled during the 2020–2025 historical window and continues on an accelerated path into the forecast period. The report models this expansion under multiple scenarios, with a central case CAGR of ~16.52% for the forecast horizon. By tying market size, cost curves, and deployment schedules together, the analysis transforms headline growth rates into actionable timing for procurement, manufacturing scale‑up, and O&M planning.
Ocean Wave Energy Technology Market
What’s in the report — practical, decision‑grade content
- Investment framework: Deal‑ready financial models (sensitivity matrices, return profiles, and de‑risking mechanisms) tailored for equity, project finance, and blended finance structures.
- Technology and performance playbooks: Device‑agnostic acceptance criteria, site‑selection checklists, survivability testing protocols, and commissioning milestones mapped to commercial revenue triggers.
- Operational cost modeling: Benchmarks and drivers for CAPEX, OPEX, lifecycle replacement schedules, and logistics footprints; comparative scenarios for onshore/nearshore vs. offshore deployments.
- Supply chain mapping: Critical node analysis from composite hull manufacturing to PTO (power take‑off) systems and mooring/anchor supply, with supplier risk ratings and localization pathways.
- Policy & market readiness toolkit: Contract templates, PPA negotiation playbooks, regulatory roadmaps, and public funding capture strategies specific to marine energy corridors.
- Commercialization roadmaps: Step‑by‑step pathways to move from pilot to pilot‑plus to commercial array — including partner archetypes, staging timelines, and sample procurement schedules.
- Proprietary datasets and models: Interactive scenario tools that convert macro growth into project‑level demand, supply, and price forecasts — core subsegment data is excluded from this public summary to preserve the report’s subscription value.
Competitive landscape — who matters and why
The sector’s competitive map is characterized by a broad set of specialized device developers, several of whom have achieved meaningful operational milestones in the past 18–24 months. This creates a buyer’s market for offtake partners and a competitive pool for project developers seeking validated technologies.
- Eco Wave Power — With a practical onshore model that leverages existing marine infrastructure and recent U.S. pilot completion, Eco Wave demonstrates the near‑term commercial pathway for land‑connected approaches. Their automation and O&M metrics from recent projects point to tangible reductions in operational uncertainty.
- CorPower Ocean — CorPower’s compact point absorbers and demonstrated survivability at commercial test sites make it a candidate for high‑energy array deployments. Device efficiency and hull composite choices influence overall array productivity and lifecycle costs.
- Carnegie Clean Energy — CETO’s combined wave power and desalination capability represents a differentiated value proposition for co‑located utility and water‑security projects, particularly in water‑stressed coastal regions.
- Ocean Power Technologies , AW‑Energy , Mocean Energy — These established players span key device classes and have moved toward utility‑scale readiness, each offering alternative reliability and deployment profiles attractive to specific market niches.
- U.S. innovators (Oscilla Power, CalWave, ORPC) — Benefiting from domestic test sites and federal support, these companies are advancing drivetrain and multi‑degree‑of‑freedom capture technologies, which could shift cost curves if scaled rapidly.
- Seabased, NoviOcean, Marine Power Systems — Representing seabed, inverted hydropower, and hybrid platform approaches, these firms expand the technology mix available to project developers and system integrators.
Collectively, the top three companies account for a modest share of the market by revenue, and the top five capture under half of market revenues — a structure that favors strategic consolidation, selective partnership, and differentiated niche strategies.
Recent developments that change commercial calculus
- Deployment momentum: Multiple firms completed pilots and commercial‑scale tests in 2025–2026, including the first U.S. onshore project deployments and successful survivability trials in high‑energy environments.
- Offtake and revenue signaling: A landmark power purchase agreement for wave‑generated energy from a U.S. test facility (covering multi‑MW outcomes) establishes precedent for utility procurement terms and credit structures.
- Public funding & infrastructure: Major competitive programs are now resourcing device development and open‑water testing — including a dedicated multi‑year federal funding window that materially lowers early‑stage cost burdens for developers and sponsors.
- Operational cost evidence: Real project O&M results have begun to surface, with at least one onshore project reporting OPEX at a low single‑digit percentage of initial CAPEX in its inaugural full‑year operations, validating lifecycle cost assumptions used in many commercial models.
- Materials and manufacturing trends: Adoption of advanced composites (e.g., filament‑wound GFRP) and modular PTO designs is driving weight‑to‑cost improvements and improving manufacturability for serial production.
Policy and infrastructure outlook
Public programs and test infrastructure are now aligned to accelerate commercialization. The U.S. Department of Energy has launched a targeted funding opportunity over multiple years that allocates over one hundred million dollars to marine energy development, supporting device maturation, open‑water testing, and utility‑scale demonstrations. Complementary test sites are scheduled to host first prototype deployments in the near term, creating focal points for procurement, grid integration trials, and supply‑chain clustering.
Strategic recommendations — actions for 2026
- Prioritize early commercial PPAs and staged offtake: Secure staged offtake tied to commissioning milestones to share technology and grid‑integration risk with developers.
- Adopt a modular procurement strategy: Favor options that allow rapid substitution of PTO and mooring components as suppliers prove serial production metrics.
- Form hybrid consortia: Pair device developers with desalination, offshore energy, or port infrastructure partners to capture co‑value streams and improve IRR profiles.
- Lock in manufacturing partnerships now: Lead times for specialized composite hulls and PTO components will lengthen with scaling; early supplier agreements reduce schedule risk and improve pricing certainty.
- Use public funding as de‑risking capital: Blend grants and concessional capital into first arrays to improve bankability for private lenders.
- Invest in O&M intelligence: Remote monitoring, automation upgrades, and condition‑based maintenance can materially lower lifecycle costs — evidenced by operational pilots that have achieved sub‑4% OPEX-to‑CAPEX ratios in early operation.
Risk & concentration assessment
Market concentration metrics indicate that leadership is distributed among several specialized vendors rather than dominated by a single incumbent. This structure reduces single‑point technology risk for buyers but increases the importance of rigorous due diligence on supply chain capacity, failure modes, and retrieval/repair logistics. The report’s risk matrices convert technology, market, and regulatory risks into investable mitigation steps and reserving strategies.
Conclusion & how to use the full study
Our market study serves as a strategic playbook: it turns macro growth forecasts and public funding levers into operational plans and investment actions for 2026. Senior executives will find the report particularly valuable for timing capital calls, structuring PPAs, designing supply‑chain agreements, and prioritizing R&D pathways.
To preserve the report’s tactical value for subscribers, this public synopsis intentionally omits the granular subsegment breakdowns, regional and application‑level percentage allocations, and device‑level revenue schedules that underpin project‑specific financials. Organizations preparing procurement strategies, investment commitments, or regulatory engagement plans should access the full report for the proprietary datasets, interactive scenario models, and deal‑ready templates that convert sector growth into executable projects.
Contact PW Consulting to obtain the full Ocean Wave Energy Technology Market report and subscriber access to the interactive financial models and procurement playbooks designed specifically for 2026 commercial decision cycles.
For detailed analysis of this topic, please visit the official page: Ocean Wave Energy Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Polymer Reinforcing Filler Market to Reach USD 20,730 Million by 2032 — 5.5% CAGR from 2026 (Base Year 2025); Asia Pacific Leads with USD 6,394M
By pmarketresearch, 2026-07-07
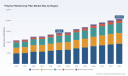
Polymer Reinforcing Filler Market: Strategic Imperatives for 2026 — PW Consulting Preview
PW Consulting today publishes a strategic preview of our upcoming Polymer Reinforcing Filler Market report (base year 2025). The market reached approximately USD 14.25 billion in 2025 and — driven by steady demand for reinforced polymers across transportation, packaging, construction and industrial applications — our central projection anticipates expansion at a 5.5% CAGR through the 2026–2032 forecast horizon, with the industry set to surpass USD 20.7 billion by 2032. This briefing summarizes the report’s practical value for 2026 decision cycles, highlights the competitive and sustainability dynamics reshaping the market, and outlines the executive actions we recommend. For the complete, granular segmentation data and company-level scorecards, access to the full report is required.
Polymer Reinforcing Filler Market
Why this matters in 2026: macro trends shaping near-term strategy
-
Demand resilience amid structural change: Polymer reinforcing fillers continue to be a core enabler of lightweighting, cost optimization, and performance uplift across multiple end markets. Although macrocycles introduce periodic volatility, underlying industrial and mobility trends (e.g., electrification, stricter fuel economy/CO2 targets, and expanded use of engineered plastics) are sustaining mid-single-digit growth.
Polymer Reinforcing Filler Market -
Supply-side shifts and pricing pressure: Raw material cost drivers remain a live issue for procurement and margin planning. For example, North American calcium carbonate pricing reached circa USD 0.32/kg in December 2025 — a reminder that feedstock swings can reshape substitution economics and force rapid reformulation choices at scale.
Polymer Reinforcing Filler Market -
Sustainability as a structural divider: Low-carbon and circular filler technologies are transitioning from niche to commercial. Notable developments include REACH-registered recycled reinforcing fillers that claim materially lower life-cycle emissions compared with conventional carbon black. Adoption will accelerate where OEMs and converters can quantify CO2 benefits without compromising mechanical performance.
-
Consolidation and competitive concentration: The market exhibits moderate concentration — the top three and top five suppliers account for material portions of global capacity — creating both stability in supply and clear levers for incumbents to pursue premiumization, capacity investments, or bolt-on M&A strategies.
What PW Consulting’s report delivers — practical, decision-ready components
Our full report is designed for commercial and technical leaders who must make tangible choices in 2026. The deliverables are intentionally operational rather than purely descriptive:
-
Robust market model (2020–2032) with sensitivity layers: total-market trajectories, unit demand drivers, and three explicit demand scenarios tied to mobility, construction cycles and packaging recovery rates.
-
Supplier capacity and risk map: plant-level footprints, announced expansions and near-term availability windows — enabling procurement to model supply shocks and lead-time exposure.
-
Material economics and substitution matrix: cross-material parity curves that quantify when silica, calcium carbonate, glass fibers or carbonaceous fillers become cost-effective substitutes given property targets and feedstock pricing.
-
Technology adoption roadmap: maturity curves for circular carbon and chemically recycled mineral blends, performance equivalency benchmarks, and adoption thresholds for OEMs and compounders.
-
Sustainability playbook: LCA comparators, compliance checklists (including REACH implications), and supplier scoring to fast-track low-emission sourcing decisions.
-
M&A and partnership playbook: target-screening filters, integration risk checklists, and deal valuation templates tailored to the materials space.
-
Interactive executive dashboard: scenario toggles (feedstock price, policy shocks, substitution rates) that translate market moves into P&L and balance-sheet impacts for buyers and producers.
Note: in keeping with our “preview” approach, we are intentionally withholding full regional, type and application breakdowns in this release — those detailed splits and the underlying database are accessible in the full report and accompanying models.
Competitive landscape — what to watch in 2026
The competitive terrain is defined by a blend of legacy majors scaling specialty grades, mineral producers optimizing cost positions, and new entrants commercializing circular or recycled reinforcing fillers. Key dynamics and company-level implications from our coverage include:
-
Cabot Corporation — recent acquisition activity and announcements around circular reinforcing carbon reflect a strategic pivot: secure feedstock and co-develop low-carbon product pathways with tire and rubber OEMs. Their Asia Pacific production capability expansion positions them to capture accelerating demand for circular carbons in high-volume applications.
-
Birla Carbon — capacity additions in Asia for ultra-high-performance carbon blacks indicate a two-pronged play: defend tire and mechanical rubber goods leadership while moving up the performance curve for polymer and coating specialties.
-
Imerys, Omya, MTI and other mineral majors — product launches targeting improved dispersion, thermal stability and bio-compatible chemistries show a shift from commodity selling to engineered solutions that enable higher filler loadings without compromising processability.
-
Plastic Energy and other circular innovators — the commercialization of chemically recycled reinforcing fillers (REACH-registered, with published carbon reduction claims) is a catalytic development. These entrants create an alternative sourcing pathway for buyers seeking lower-scope emissions footprints.
-
Composite specialist suppliers (e.g., Owens Corning, RTP Company) — glass fibers and specialty compounders remain critical where mechanical performance mandates fiber reinforcement. Their partnerships with OEMs create entry barriers for lower-cost mineral substitution in high-performance applications.
Strategically, these movements translate into three actionable implications: incumbents must accelerate product differentiation and circular capabilities; converters should run parallel qualification tracks for lower-carbon substitutes; and investors should re-evaluate target screens to include circular-chemistry IP and downstream compounding expertise.
Strategic actions we recommend for 2026 decision cycles
-
Procurement and supply chain: implement multi-sourced contracts for key filler families and build FLEX options with regional converters to mitigate single-point capacity risk. Use the report’s supplier-risk heatmap to prioritize contractual hedges and buffer inventory strategies.
-
R&D and product strategy: fast-track co-development with circular filler providers where LCA benefits are demonstrable and set joint validation timelines with OEMs to shorten go-to-market cycles.
-
Commercial and pricing: adopt differentiated pricing for low-carbon or high-performance grades; use substitution cost curves to defend margin while enabling customers to meet sustainability targets.
-
Investment and M&A: target bolt-ons that add surface-treatment capabilities, specialty mineral processing, or chemical-recycling feedstock access. The report’s M&A playbook prioritizes assets that accelerate either margin expansion or technological preemption.
-
Regulatory and sustainability: integrate REACH and regional EPR policy scenarios into long-range planning. Prioritize suppliers with certified lower-emission product pathways and transparent LCA data to de-risk downstream compliance demands.
How executives will use this report in 2026
-
Procurement teams will model supplier exposure under price shock and capacity shortfall scenarios and convert those into negotiated terms.
-
Product and formulation teams will use substitution matrices and performance benchmarks to decide when to switch filler chemistries without re-engineering entire platforms.
-
Corporate development teams will apply the M&A playbook to prioritize targets that either extend sustainable product portfolios or fill strategic gaps in processing and surface treatment.
-
Sustainability leads will deploy the report’s LCA comparators to quantify version-to-version emissions improvements and to prepare procurement specifications for low-carbon fillers.
Closing — the strategic value proposition
For 2026, the strategic calculus in the polymer reinforcing filler market hinges on three interlocking imperatives: securing resilient and flexible supply; differentiating via material performance and sustainability; and timing investments or partnerships to capture structural demand growth. PW Consulting’s full report combines a rigorous market model, plant-level supply mapping, technology-adoption roadmaps, and operational playbooks to move leaders from insight to action. This preview has highlighted the high-level implications and recent commercial milestones; the full dataset and company-level scorecards — including the granular regional, type and application splits that underpin scenario testing — are available through our report portal.
To obtain the full report, access the interactive dashboard, or arrange a bespoke executive briefing tailored to your business unit’s priorities for 2026, please visit PW Consulting’s report page or contact our industry team directly.
For detailed analysis of this topic, please visit the official page: Polymer Reinforcing Filler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Palm Kernel Shells Biomass Market to Expand at 8.5% CAGR, Reaching USD 2.32 Billion by 2032
By pmarketresearch, 2026-07-07
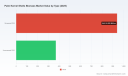
Palm Kernel Shells Biomass Market: Strategic Imperatives for 2026 — PW Consulting Insights
PW Consulting’s latest Palm Kernel Shells (PKS) Biomass Market report, with a 2025 base year and forecast horizon through 2032, is designed as a decision-useful tool for energy executives, commodity traders, project financiers and procurement leads preparing for a pivotal 2026. Our analysis shows the PKS market expanding from roughly USD 820.5 million in 2020 to about USD 1,310.0 million in 2025, and on a path to near USD 2.32 billion by 2032 — an 8.5% compound annual growth rate across the forecast period. This briefing outlines why the 2026 planning cycle requires recalibrated commercial strategies and what practical intelligence the full report delivers to support those choices.
Palm Kernel Shells Biomass Market
Why 2026 Is a Strategic Inflection Point
-
Policy and market demand are aligning. Accelerated decarbonization targets in major energy-consuming economies, combined with incentives for biomass co-firing and renewable power, are translating into steadier off-take commitments and longer lead-time purchase agreements. For buyers and suppliers alike, 2026 will be the year when short-term spot behavior gives way to contract portfolios that favour sustainability-compliant volumes.
Palm Kernel Shells Biomass Market -
Supply-side volatility is resurfacing as a commercial risk. Recent national measures — including Indonesia’s export tax framework tied to palm oil reference prices and additional levies, and Malaysia’s upward adjustment of export service tariffs — increase landed cost uncertainty for international buyers and nudge marginal supply back to domestic markets or higher-margin export channels.
Palm Kernel Shells Biomass Market -
Certification and traceability are non-negotiable for premium markets. Green Gold Label (GGL) and equivalent sustainability credentials are already gateway requirements for buyers in Japan, and will be a central negotiation point in long-term supply agreements. Firms without certified sourcing pathways risk price discounts or exclusion from priority tenders.
-
Consolidation signals and capacity moves are accelerating. Visible industry activity — from capacity expansions to multi-year offtake MOUs — indicates that incumbent suppliers and strategic entrants are racing to lock export-eligible, certified volumes ahead of anticipated demand growth.
What the Report Delivers — Practical, Actionable, and Ready for 2026
Our report is structured for immediate application in commercial planning and investment decision-making. Key deliverables include:
-
Robust market sizing and forward-looking scenarios. We provide a base model calibrated to 2020–2025 historicals and three stress-tested demand trajectories through 2032. The headline projection uses an 8.5% CAGR, but embedded scenario tools quantify downside risk (policy rollback, logistical disruption) and upside sensitivity (accelerated co-firing mandates).
-
Supply-chain heat maps and trade-flow analytics. Interactive modules identify chokepoints, principal export hubs, and seaborne routing options that materially affect freight lead times and landed price volatility — essential for procurement scheduling and LNG/coal co-firing retrofit planning.
-
Price benchmarking and procurement playbooks. We provide normalized pricing series, delivered-cost models, and sample contract terms that illustrate how to structure indexed contracts (CPO-linked, fixed+variable blends), credit support, and quality acceptance clauses that reflect real-world vessel sampling and moisture/ash tolerances.
-
Supplier scorecards and counterparty risk matrices. Each major supplier is assessed across production footprint, certification status, export compliance history, balance-sheet resilience and logistics competence — enabling prioritization in multi-supplier sourcing strategies.
-
Technical dossiers and combustion compatibility guidance. Concise engineering notes cover typical PKS fuel specifications (net calorific value, moisture, ash content) and co-firing integration considerations — essential when evaluating boiler modifications or switchgear tolerances.
-
Investment and M&A playbook. For investors, we include valuation benchmarks, capex/opex reference models for processing plants, and acquisition checklists tuned to the sector’s operating realities and regulatory exposures.
Competitive Landscape: What We Observed and What it Means
The PKS supply base remains commercially active but not fully consolidated. Our concentration analysis indicates the top three players account for roughly one‑third of market share, while the top five approach close to half — a structure that supports both continued competition and selective consolidation. Implications for market participants include:
-
For buyers: diversify counterparty exposure while prioritizing certified suppliers. Large suppliers are expanding capacity and securing multi-year offtakes; smaller suppliers can offer flexibility but may struggle to meet certification and volume stability requirements for premium markets.
-
For suppliers: scale and traceability are key differentiators. Recent corporate moves demonstrate that investments in processing capacity and GGL-style certifications materially improve access to high-value export markets. Securing mill-level feedstock and investing in consistent sizing/low-ash processing will command a premium.
-
For investors: look for vertically integrated platforms that combine feedstock control, processing, and logistics. Entities that can internalize the supply chain reduce exposure to export levy swings and freight shocks, while certified production brings price differentiation.
Representative corporate dynamics we examined include: BIO ENECO’s recent ramp-up of processing capacity and multi-year supply agreements to premium markets; global trading houses maintaining long-term arrangements with mills to secure supply and spread delivery risk; and specialized European and Asian players emphasizing product specification uniformity and low-ash output for industrial boiler and activated carbon applications. These developments underscore a market in which strategic partnerships and certification credentials are decisive commercial levers.
Regulatory and Cost Drivers to Watch in 2026
-
Export charges and domestic levies. Recent adjustments in export taxation and service tariffs have immediate implications for international arbitrage and landed cost structures. Procurement teams must incorporate tariff scenarios into contract negotiations and cost pass-through clauses.
-
Sustainability compliance. Certification regimes are evolving; buyers will increasingly require proof of traceability, chain-of-custody and sustainability adherence. Non-compliant volumes face discounting or market exclusion.
-
Technical standardization. Expect demand for screened/graded product and tighter moisture/ash limits, especially where PKS is used in co-firing or as feedstock for higher-value conversion (charcoal, activated carbon). Investments in quality control will reduce downstream operating risk.
Top-Line Strategic Recommendations for 2026 Planning
-
Buyers: negotiate staged multi-year agreements with flexible volume bands and indexation to CPO or an agreed composite index, coupled with a spot allocation strategy to capture short-term discounts without sacrificing security of supply.
-
Suppliers: prioritize certification and capacity investments that target export-grade product streams; develop export-ready logistics hubs to shorten lead times and mitigate port-side bottlenecks.
-
Investors and lenders: stress-test asset-level returns against tariff and certification scenarios; favour assets with integrated feedstock access or long-term take-or-pay offtakes to de-risk cashflow.
-
Project developers: quantify retrofit economics for co-firing projects using a range of fuel price paths; build contractual flexibility to switch fuel blends in periods of PKS scarcity or elevated premiums.
Conclusion — The Strategic Value of the Full Report
Our Palm Kernel Shells Biomass Market report is engineered to convert market observation into executable strategy. It pairs a quantitatively robust headline forecast (2025 base, 2026–2032 horizon, 8.5% CAGR) with operational tools — pricing models, counterparty due diligence templates, risk matrices and certification checklists — that leaders can deploy immediately during 2026 planning cycles. The market dynamics we document signal selective opportunity: those who move early to secure certified supply, hedge regulatory exposure, and invest in logistics and quality control will capture disproportionate value as demand scales.
PW Consulting intentionally withholds detailed regional and application sub-breakdowns in this summary to preserve the report’s full-scope commercial intelligence for subscribers. For the complete dataset, interactive models, supplier scorecards and the detailed annexes that support 2026 decision-making, access the full report on our website or contact PW Consulting’s advisory desk for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Palm Kernel Shells Biomass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Commercial Small Batteries Market to Expand at 6.79% CAGR, Reaching USD 23,108 Million by 2032
By pmarketresearch, 2026-07-07
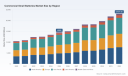
Commercial Small Batteries Market 2026 Strategic Briefing — PW Consulting
PW Consulting’s new market intelligence on the Commercial Small Batteries Market has been produced to equip executives with the forward-looking, decision-ready analysis necessary for 2026. Our base-year market sizing shows a market of USD 14,580 Million in 2025. Built on a consistent historical series and scenario modelling, the analysis demonstrates a compounded annual growth rate (CAGR) of 6.79% across the forecast window, with the market trajectory pointing toward materially higher scale by the end of the decade. This briefing highlights the strategic takeaways from the full report, the practical modules included, and the near-term actions corporate leaders should prioritize — while preserving the report’s proprietary segmentation and tactical tables to encourage direct access to the full intelligence package.
Commercial Small Batteries Market
Why this matters for 2026 decision-makers
-
Demand inflection and margin pressure converge: Commercial small batteries are transitioning from a stable commodity to a value-rich product class defined by performance, regulatory compliance and upstream volatility. From a buyer and OEM perspective, the near-term imperative is balancing product differentiation with cost control.
Commercial Small Batteries Market -
Regulation and safety are no longer niche compliance items: New standards and supplier obligations are raising the bar on product design, labeling, and extended producer responsibility. These have direct implications for time-to-market and packaging/assembly costs.
Commercial Small Batteries Market -
Concentration and competitive positioning matter: The market shows a moderate level of concentration among the largest producers. Our competitive concentration analysis signals both defensive moves by incumbents and opportunistic entry points for specialized suppliers and regional champions.
-
Raw-material volatility is a strategic risk: Price swings in key feedstocks propagate into procurement, pricing and product roadmaps — requiring companies to embed commodity scenarios into commercial planning.
What the PW Consulting report delivers — practical, operational intelligence
-
Proprietary market sizing and validated forecasting: A transparent methodology with scenario envelopes that capture base, upside and downside outcomes for the 2026–2032 window. We present topline market trajectory, drivers and leading indicators to watch, without disclosing the proprietary sub-segmentation matrices in this release.
-
Supplier and competitor playbooks: Strategic profiles and capability maps for the market’s leading firms, with actionable recommendations for partnering, co-development, and competitive defense. Profiles cover manufacturing footprint, product breadth, and commercial strengths.
-
Go-to-market frameworks for OEMs and distributors: Tactical playbooks for channel selection, pricing architecture, private-label vs. branded strategies, and bundling options that protect margin while accelerating adoption in commercial channels.
-
Procurement and cost-modelling toolkit: A downloadable, parametric cost model that lets procurement teams run sensitivity tests (including commodity price swings, freight, and regulatory compliance costs) and derive contract breakpoints and hedging alternatives.
-
Regulatory and safety compliance checklist: Step-by-step remediation paths to comply with new and evolving standards and requirements relevant to small and button/coin cells, including packaging and ingestion-risk mitigations.
-
M&A and partnership screening matrix: Criteria and scorecards for identifying bolt-on targets, strategic JV partners or contract manufacturers that can close capability gaps in chemistry, safety testing or geographic reach.
-
Case studies and supplier negotiation templates: Real-world examples of cost takeout, speed-to-market accelerations, and safety-driven design changes that materially reduced product risk or opened incremental commercial channels.
Key dynamics shaping 2026
-
Commodity swings: Lithium carbonate exhibited significant volatility in 2025 — rebounding sharply during the second half of the year — and is expected to remain in a wide trading band through 2026. PW Consulting’s procurement scenarios explicitly model a range of price outcomes and their pass-through to small lithium battery production costs.
-
Regulatory tightening: A combination of new standards and updated regulations is changing product design constraints. Notable developments include UL 4200A addressing physiological hazards from button and coin cells, the updated IEC safety provisions for primary button cells, and regional batteries regulations that increase labeling and producer obligations. These translate into longer product qualification cycles and higher compliance costs if not actively managed.
-
Safety-first product evolution: Child-ingestion risk has catalyzed both product-level and packaging innovations (mechanical barriers, bitter coatings, tamper-evident features). Vendors introducing these features are seeing faster acceptance in healthcare, medical device and other safety-sensitive end markets.
-
Commercial convergence and targeted innovation: Incumbent battery brands, diversified electronics manufacturers and industrial power specialists are expanding product sets to capture adjacent commercial use-cases — from IoT sensors to emergency lighting — increasing competition on product performance and lifecycle services.
Competitive landscape — who to watch and why
The report includes strategic profiles of the market’s primary participants and synthesizes their likely near-term moves. Among the names that executives should monitor closely:
-
Major global brands with deep retail and B2B channels — these firms continue to leverage brand trust and broad distribution to protect premium positions across multiple chemistries.
-
Japanese and European technology-focused manufacturers — players with capabilities in precision coin and micro cells are capitalizing on medical and high-reliability segments.
-
Industrial and backup specialists — firms serving UPS, standby and motive applications position differently from consumer-oriented suppliers, often competing on system integration and lifecycle services rather than unit-cost.
-
Regional and niche players — agile manufacturers are capturing specific commercial applications by optimizing local supply chains and compliance know-how.
Recent market developments underscore these dynamics: product line expansions by battery system manufacturers, global trade-show showcases of small-format battery technologies, and safety-driven product innovations such as bitter coatings for coin cells. These events are consistent with a market that is both expanding and maturing in terms of technical and regulatory complexity.
Actionable implications and recommended next steps for 2026
-
Embed commodity scenarios into commercial plans: Procurement and product teams should run three-tier commodity sensitivity tests (base/volatile/stretch) and translate outcomes into pricing contracts, pass-through clauses and inventory policy.
-
Prioritize compliance-readiness: Map product portfolios to emerging standards and regulations, and fast-track redesigns for SKUs targeting safety-sensitive channels. Delays in adaptation materially increase time-to-revenue.
-
Rebalance supplier strategies: Move from single-sourcing to a dual-track approach that secures capacity while enabling competitive price discovery. For high-risk chemistries, consider toll-manufacturing or captive production as hedges.
-
Invest in value-added differentiation: In commercial segments where safety, longevity and service matter, invest in certification, extended warranties and integrated lifecycle services to justify premium pricing.
-
Use M&A selectively to fill capability gaps: Targets with specific chemistry expertise, testing infrastructure or regulatory know-how can accelerate entry into higher-margin commercial subsectors.
-
Design a compliance-driven go-to-market timeline: Regulatory changes impose calendar constraints. Map certification timelines against product launches to avoid costly delays.
How PW Consulting’s intelligence supports your 2026 playbook
The full PW Consulting report packages market forecasts, supplier maps, tactical playbooks and procurement tools into a single deliverable calibrated for commercial decision-makers. It connects macro growth trajectories and concentration metrics with operational levers — from sourcing and manufacturing to product safety and after-sales service — enabling executives to convert market growth into sustainable margin expansion.
To preserve the commercial value of our proprietary segmentation, stratified scenarios and the detailed supplier scorecards, this briefing has intentionally avoided disclosure of core breakouts. Clients and stakeholders who need the full, actionable dataset — including region and application breakouts, chemistry-specific roadmaps, and downloadable cost-model assets — are invited to access the full report and accompanying tools on PW Consulting’s portal.
Next steps
-
Book a strategic briefing with PW Consulting to receive a tailored executive summary aligned to your portfolio and priority markets.
-
Request the procurement sensitivity model to run your own scenario tests against the lithium price bands, freight and compliance cost assumptions used in our base and stress cases.
-
Engage our M&A and partnership advisory to identify targets and construct integration roadmaps that preserve product integrity while accelerating market entry.
PW Consulting’s Commercial Small Batteries Market report is designed for senior executives, procurement leads, product managers and corporate development teams who must make confident, defensible decisions in 2026. With the market at a strategic inflection point — higher regulation, raw-material volatility, and demand for safer, differentiated products — firms that combine rigorous scenario planning with decisive operational moves will capture the disproportionate share of growth. Contact PW Consulting to access the full report and the complete dataset.
For detailed analysis of this topic, please visit the official page: Commercial Small Batteries Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Polyelectrolyte Market Set to Grow at a 5.31% CAGR During 2026–2032
By pmarketresearch, 2026-07-06
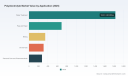
Polyelectrolyte Market 2026 Strategic Outlook — Tactical Intelligence for Decision-Makers
PW Consulting’s newest market research provides a strategic roadmap for executives, investors, and technical leaders preparing for 2026 and beyond. Built on a 2025 base year and a 2020–2025 historical foundation, the study delivers a 2026–2032 forecast that is both granular and execution-oriented. At the macro level, the global polyelectrolyte market is on a steady expansion trajectory: from approximately USD 3.12 billion in 2023 to USD 3.45 billion in 2025, with a modeled compound annual growth rate (CAGR) of 5.31% that projects the market to nearly USD 4.95 billion by 2032. These headline numbers form the quantitative spine of our analysis; the remainder of the report translates them into near-term strategic actions.
Polyelectrolyte Market
The Strategic Imperative for 2026
-
From procurement to product development, 2026 will be a year in which marginal performance and supply-chain resilience determine winners. A mid-single-digit market expansion masks structural reallocation across applications, feedstocks, and geographies — dynamics that require targeted responses rather than generic volume plays.
Polyelectrolyte Market -
Key commercial and technical choices — localization of supply, premiumization of product portfolios, and alignment with tightening environmental standards — will have outsized impact on profitability given the market’s measured growth rate. The PW report converts the macro CAGR and multi-year projections into break-even matrices, margin sensitivity tables, and prioritized investment scenarios.
Polyelectrolyte Market -
Because the industry is not homogenous, 2026 is the year to choose focus: optimization (operations, cost) or differentiation (specialty chemistries, sustainability). Our findings identify which bets are likely to offer leadership-level returns within the forecast window.
What the Report Contains — Practical, Transaction-Ready Content
-
Demand and revenue model (2020–2032): a bottoms-up build that links end-market drivers to volume and pricing outcomes.
-
Scenario analysis: three forward-looking scenarios (base, upside, downside) with trigger conditions, tactical playbooks, and portfolio impact assessments.
-
Raw-material cost and pricing toolkit: sensitivity matrices that translate acrylamide and related feedstock swings into margin and contract pricing implications.
-
Manufacturing and logistics playbook: plant-utilization benchmarks, break-even scales, and recommendations for localized versus centralized manufacturing footprints.
-
Commercial acceleration assets: procurement negotiation templates, value-based pricing blueprints, and customer segmentation for premium offerings.
-
M&A and partnership framework: acquisition screening criteria, integration checklists, and synergy estimation templates for roll-ups or technology buys.
-
Regulatory and compliance matrix: jurisdiction-level obligations, compliance roadmaps, and capex implications for 2026–2028 planning.
Key Market Dynamics Shaping 2026 Decisions
-
Raw-material volatility: In 2025, regional polyacrylamide pricing exhibited divergent trends driven by demand variability and capacity moves. China saw price pressure over the year, while prices in Northeast Asia and Europe showed modest upward adjustments toward year-end. More fundamentally, acrylamide production depends on acrylonitrile — a petroleum-derived feedstock — exposing producers to crude-oil driven volatility and supply-chain shocks. Our cost models quantify the margin exposure for typical product formulations and recommend hedge ratios and contract structures for 2026 procurement cycles.
-
Regulatory tightening: Stricter wastewater discharge and chemical-safety standards are accelerating adoption of higher-performance polyelectrolytes and premium formulations that enable tighter treatment limits and easier compliance. The report maps regulatory trajectories and identifies the technical attributes buyers will demand (e.g., lower residual monomer, improved dewatering performance) and the capex implications for suppliers.
-
Demand-side shifts: Water reuse, circular-economy initiatives, and the digitalization of dosing and monitoring are changing how end-users buy chemistry — shifting value from commodity price to service, performance guarantees, and total cost of ownership. We quantify the premium pools emerging from service-oriented commercial models and the investment needed to capture them.
-
Capacity and regional competition: Capacity additions in certain markets have produced price pressure in recent cycles. Our analyses identify where overcapacity is most likely to compress margins and where differentiated chemistries will insulate pricing power.
Competitive Landscape — Players, Positioning, and Strategic Moves to Watch
The polyelectrolyte industry is characterized by a mix of global integrators, specialty chemical players, and regional producers. Overall market concentration metrics indicate meaningful space for scale players while leaving room for regional champions and specialized entrants.
-
Global leaders such as SNF Floerger, BASF SE, Kemira, Solenis, and Ecolab (Nalco Water) compete on scale, breadth of formulation, and integrated service offerings. Their common playbook is to combine large-volume manufacturing with application engineering and digital dosing capabilities — a combination that raises switching costs for large industrial customers.
-
Traditional chemical majors (e.g., Dow, Arkema) bring broad raw-material integration and global sales networks, enabling them to protect margins through sourcing advantages and portfolio bundling.
-
Regional producers and contract manufacturers — including several China- and India-based firms — emphasize cost-competitiveness and local service. Some operate high-capacity plants dedicated to commodity grades; others are pivoting toward specialty formulations to escape commodity-style margin pressure.
-
Strategic implications: Scale players will continue to invest in premium products and service models; regional players should prioritize differentiation or cost leadership. M&A is likely to feature tuck-ins that add application know-how, localized footprint, or complementary product lines.
Strategic Playbook for 2026 — Actions by Role
-
For global producers: accelerate development of higher-value formulations that reduce total-treatment costs for end users; expand digital dosing services; and selectively localize production where logistics and regulatory complexity justify it.
-
For regional producers: prioritize niche specialization (e.g., mining tailings, advanced sludge dewatering) and formalize partnerships with global players to access technology and premium customers.
-
For end-users and water utilities: renegotiate contracts to include performance SLAs and indexed pricing clauses tied to feedstock benchmarks; pilot service-based procurement models that shift supplier incentives toward performance.
-
For investors and M&A teams: focus on targets that combine application expertise with demonstrable customer retention; value extraction is highest where bolt-on acquisitions bring immediate cross-selling and procurement synergies.
-
For R&D teams: prioritize low-residual-monomer chemistries, biodegradable options where possible, and polymer formulations that reduce sludge volume and energy demand during dewatering.
How PW Consulting’s Analysis Converts Insight into Decisions
Beyond top-line projections, our report supplies the decision-support assets that convert market insight into executable plans: plant-level economics (including capex/back-of-envelope returns), customer segmentation by value-to-supplier, procurement templates indexed to raw-material cost drivers, and a time-phased investment roadmap. We intentionally keep this press briefing at a strategic level — omitting the granular segment-level tables and regional/application revenue splits that are included in the licensed report. That detailed intelligence is the fulcrum for capital deployment, pricing strategy, and M&A diligence, and it is available in the full study.
Conclusion — What Leaders Should Do Next
2026 will be a year of selective consolidation and premiumization in polyelectrolytes. With a projected mid-single-digit CAGR and a market approaching the USD 5 billion mark by the early 2030s, the opportunity is substantial but nuanced: scale still matters, but so does specialization, regulatory alignment, and service-model execution. PW Consulting’s report is designed to shorten the path from insight to decision — providing the playbooks, models, and risk matrices that corporate leaders need to allocate capital, negotiate contracts, and prioritize R&D for maximum return.
To access the full dataset, segmented forecasts, supplier scorecards, and downloadable toolkits that underpin these conclusions, request the complete Polyelectrolyte Market Report and executive dashboards from PW Consulting’s publications page or contact our advisory desk for a briefing tailored to your strategic questions.
For detailed analysis of this topic, please visit the official page: Polyelectrolyte Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Cold Roof Coating Market to Reach USD 8,611.45 Million by 2032, Growing at a 7.15% CAGR
By pmarketresearch, 2026-07-06
Cold Roof Coating Market — Strategic Preview for 2026: Why PW Consulting’s New Report Is a Decision-Maker’s Playbook
As building owners, manufacturers, and investors position for the next growth cycle in energy-efficient building materials, cold roof coatings have emerged from niche retrofit solutions into a mainstream category with measurable impact on operating costs, regulatory compliance, and sustainability commitments. PW Consulting’s latest market study — covering historical performance (2020–2025), a 2025 base year, and a detailed forecast horizon (2026–2032) — distills what corporate leaders must know now to make defensible decisions across product development, sourcing, pricing, and M&A throughout 2026.
Cold Roof Coating Market
Macroeconomic Trajectory: Growth that Pays Attention
The cold roof coating market is on a sustained expansion path. PW Consulting’s model positions the global market at approximately USD 5.31 billion in 2025, growing at a compound annual growth rate (CAGR) of 7.15% over the forecast period. By 2026, the market is projected to exceed USD 5.6 billion, and the base-case scenario carried through our sector models reaches beyond USD 8.6 billion by 2032. These topline dynamics are driven by a mix of regulatory adoption, building-code requirements tied to solar reflectance and SRI performance, accelerated retrofit pipelines in commercial portfolios, and increasing specification activity for new-build projects prioritizing thermal performance.
Cold Roof Coating Market
What the Report Contains — Practical, Executable Insight (Not Just Charts)
- Integrated market-size and demand-driver modeling that translates macro policy levers and climatic exposure into quantifiable demand scenarios.
- Segmentation-focused playbooks (by product chemistry, end-use application, and channel) that prioritize where to invest R&D, where to defend, and where to harvest.
- Raw-material and cost-pass-through frameworks that link petrochemical feedstock volatility and pigment pricing to margin outcomes under realistic contract structures.
- Regulatory-compliance mapping that overlays the latest ANSI/CRRC S100-2025 testing protocols and CRRC program developments onto product development and labeling roadmaps.
- Commercial execution tools: specification templates, procurement negotiation levers for large accounts, installer certification and warranty program design principles, and a six- to 18-month go-to-market sprint plan.
- M&A and partnership diagnostics: valuation premia drivers, integration risk checklists, and a short-listing methodology for bolt-on targets based on technological fit and route-to-market synergies.
Importantly, the report is structured to be used in boardrooms and by business-unit leaders: each chapter concludes with “Decision Points” and a one-page action plan tailored to either an incumbent manufacturer, an investor evaluating entry, or a large specifier seeking to accelerate rooftop conversions.
Cold Roof Coating Market
Competitive Landscape — Who’s Shaping the Market and How
Competition in the cold roof coating sector balances large, diversified chemical companies with specialized niche formulators. Market concentration is moderate: the top three players account for roughly one-third of market revenue, while the top five approach the mid-forties percentile. This structure creates both room for scale advantages (procurement, distribution, cross-selling) and opportunities for targeted differentiation (product performance, certification, installer networks).
- Sherwin-Williams — leverages global architectural channels and high-performance infrared-reflective pigment systems. Their scale in commercial and industrial coatings makes them a go-to for integrated roofing system specifications.
- PPG Industries — focuses on high solar-reflectivity formulations and global distribution reach; delivers solutions that exceed aggressive reflectance thresholds sought by white-paper led sustainability teams.
- AkzoNobel — pushes elastomeric and durability-led offerings, emphasizing long-life solutions for commercial roofs in variable climates.
- RPM (Tremco and others) — operates at the intersection of liquid-applied systems and restoration economics; positions warranty and system-level performance as a commercial differentiator.
- BASF, Dow, and Sika — supply base chemistries, dispersions, and system components; their role is critical in upstream innovation and scale manufacturing economics.
- GAF, Henry (Carlisle), Gardner-Gibson, Karnak, Western Colloid — regional and specialty brands that compete on substrate compatibility, installer relationships, and cost-effective restoration solutions.
- Niche innovators (NanoTech Materials, Castagra, Neogard) — targeting high-value points with ceramic-insulative technologies, VOC-free systems, and high-performance urethanes that meet CRRC listings and regional regulatory standards.
Recent industry moves underscore competitive dynamics: new product launches combining fiber reinforcement and low-VOC chemistry; extended warranty programs tied to installer certification; and standards evolution with CRRC updating ANSI/CRRC S100-2025 and accrediting the first international independent testing lab. These developments alter the barrier-to-entry calculus: product performance alone no longer suffices without certified testing and clearly articulated lifecycle economics.
Key Market Dynamics and Risks for 2026 Decision-Making
- Raw-material volatility: Acrylics, silicones, and pigment inputs remain linked to petrochemical cycles and titanium dioxide supply chains. Our scenario models show margin sensitivity when price spikes occur and when product portfolios skew heavily toward premium chemistries without price-protection mechanisms.
- Premiumization vs. Cost-Accessibility: Silicone-based systems command a notable price premium versus acrylic alternatives due to longevity and weathering performance. Manufacturers and specifiers need playbooks for justifying higher upfront costs via lifecycle TCO and warranty transferability.
- Standards and certification: ANSI/CRRC S100-2025 reshapes testing expectations for liquid-applied coatings and composite materials. Producers who are early to secure CRRC listings and who can demonstrate test-to-spec performance on rough substrates will gain faster entry into code-driven procurement streams.
- Installer and warranty ecosystems: Extended warranties backed by installer certification are becoming table stakes in commercial retrofit contracts. Programs that combine training, serial-quality audits, and conditional warranty economics materially reduce project risk for large building owners.
- Consolidation potential: With CR3 and CR5 concentration levels indicating moderate dominance by a handful of firms, M&A remains a strategic lever for both market incumbents seeking technology and channel for new entrants searching scale.
Top Strategic Moves for 2026 — What Leaders Should Do Now
- Prioritize certification and testing: Allocate R&D and lab budgets to secure CRRC-compliant listings under the S100-2025 framework. Factor third-party lab timelines into product launch calendars — the recently accredited international testing capacity shortens time-to-market for globally distributed SKUs.
- Design warranty-linked commercial offers: Build installer certification pathways tied to multi-tiered warranty products. Our financial models show that warranty programs, when coupled with performance-based pricing, accelerate procurement inclusion with national contractors.
- Hedge raw-material exposure: Implement multi-source procurement and index-linked supply contracts for pigments and base polymers. Consider strategic inventory cushions for titanium dioxide and specialty resins to avoid costly production halts during feedstock shocks.
- Rebalance portfolio for lifecycle value: Segment offerings into “performance longevity” and “cost-accessible” lines. Use targeted pilots to validate TCO narratives in different climates and asset classes, and capture case studies that justify premium positioning.
- Expand retrofit-as-a-service pilots: For manufacturers and service providers, co-develop financing and performance-guarantee offers with building owners to lower adoption friction and demonstrate near-term energy savings.
- Use M&A as capability-buying: Target bolt-ons that bring proprietary chemistries, localized installer networks, or testing lab capacity instead of purely acquiring incremental volume.
Why This Matters for 2026 Budgets and Boardroom Priorities
Decisions made in 2026 will influence several years of revenue mix and margin profile. The market’s steady CAGR supports growth investments, but the operational execution — certification timing, warranty economics, and raw-material management — determines which players capture durable value. PW Consulting’s study equips leaders with the quantitative scenarios and executable playbooks needed to convert regulatory momentum and sustainability commitments into repeatable business models.
Next Steps — Accessing the Full Intelligence
This preview reflects the strategic contours of PW Consulting’s Cold Roof Coating Market report. The full dossier contains the granular scenario models, procurement negotiation templates, product-specification matrices, and the proprietary financial model that underpins our forecasts. For executives who require board-ready briefing decks, supply-chain simulations, or tailored M&A screening lists, PW Consulting offers bespoke workshops and implementation sprints aligned with the report.
Contact PW Consulting or visit our website to download the executive summary and to arrange a briefing. Our clients use the report to de-risk 2026 product launches, shape warranty-backed commercial offers, and prioritize capex and M&A that produce measurable, near-term returns.
For detailed analysis of this topic, please visit the official page: Cold Roof Coating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High-Barrier MDO-PE Film Market Poised for 14.5% CAGR as Food Packaging Fuels Demand
By pmarketresearch, 2026-07-06
High-Barrier MDO-PE Film Market: Strategic Imperatives for 2026 — PW Consulting Preview
The High-Barrier MDO-PE Film market is transitioning from a technically interesting niche to a strategic vector for packaging resiliency and circularity. Our new PW Consulting market study — based on a 2020–2025 historical base and a 2026–2032 forecast horizon — shows a sustained double‑digit expansion trajectory, underpinned by regulatory pressure, materials substitution and targeted product innovation. The total market, which approximately doubled over the 2020–2025 period, is projected to grow at a robust compound annual growth rate (CAGR) of about 14.5% through the forecast window, outpacing many conventional flexible packaging segments and signaling material strategic choices for 2026 planning cycles.
High Barrier Mdo Pe Film Market
Why this report matters for 2026 decisions
-
Regulatory inflection points are compressing timelines. Packaging requirements in major markets are accelerating adoption of mono‑material, recyclable structures; brand owners and converters must reconcile performance needs (oxygen and moisture protection, aroma retention, heat resistance) with compliance and recyclability targets.
High Barrier Mdo Pe Film Market -
Technology substitutions are materializing. Developments in EVOH co‑extrusion, vacuum coatings (AlOx/SiOx) and optimized MDO processing are enabling PE‑based constructions to replace multi‑material films and even aluminum foil in selected use cases—changing lifecycle economics and recycling pathways.
High Barrier Mdo Pe Film Market -
Commercial dynamics are noisy but directional. Resin price volatility and regional resin availability are affecting landed costs and arbitrage opportunities for converters. Meanwhile, practical product launches and collaborations from leading suppliers are lowering the technical and commercial barriers to broader adoption.
What the PW Consulting report delivers (practical, executable content)
-
Market sizing and scenario forecasts: multi‑scenario total market forecasts through 2032 with sensitivity to resin price cycles, regulatory adoption rates and downgauging potential.
-
Technology playbook: side‑by‑side technical comparisons of EVOH co‑extrusion vs. vacuum coatings vs. specialty polyamide/PE structures, including performance envelopes (OTR/WVTR ranges), process implications, and quality‑control checklists for scale‑up.
-
Commercial models and ROM (run‑of‑model) cost decks: unit cost drivers, contract negotiation levers, and blended landed cost scenarios under different resin price regimes.
-
Supplier and competitive maps: capability heatmaps, technology roadmaps of key producers, and a diligence checklist for qualification of new suppliers or partnerships.
-
Go‑to‑market playbooks: pilot design templates, validation protocols for barrier performance and shelf‑life studies, and retailer‑facing sustainability narratives that align with recyclability claims.
-
M&A & investment screening: thresholds and bet sizes for vertical integration (coating lines, EVOH compounding) versus long‑term supply agreements.
Competitive landscape—who is shaping the market now
The competitive picture blends multinational film specialists, regional champions and technology‑driven newcomers. Several firms have moved from concept to commercial scale in 2024–2025, demonstrating both product credibility and emerging commercial traction. Our study includes detailed profiles and strategic assessments of leading players and market entrants, with pragmatic advice for partnership, sourcing and competitive response.
-
RKW Group (Mannheim, Germany) — RKW’s RKW Horizon® MDO‑PE family exemplifies the co‑extruded EVOH approach that targets mono‑material recyclability without sacrificing oxygen protection. For brand owners seeking rapid substitution of multi‑material structures, RKW represents a low‑integration partner with strong marketing and application support. Risk: premium positioning and supply constraints during ramp phases.
-
Polifilm (Germany) — With solutions that can function as print substrates or barrier layers, Polifilm is focused on enabling converters to replace traditional PET/OPP/OPA laminates while improving recyclability and stiffness. Opportunity: converters seeking a drop‑in optics/print solution; watch for how Polifilm balances price and availability.
-
CloudFilm (Qingdao, China) — A supplier of high‑barrier MDO‑PE grades and AlOx coated variants aimed at food, pet food and pharmaceutical laminates. Strengths include local supply density and coating capability that supports 100% PE recyclable constructions—critical for APAC demand growth.
-
TOPESOL (Guangdong, China) — Producing high‑barrier grades that in some cases rival traditional aluminum foil, TOPESOL’s portfolio is notable for extremely low OTR/WVTR performance. Strategic consideration: these grades enable brand owners to pursue high‑barrier mono‑PE pack formats for aroma‑sensitive goods but may require altered sealing and form‑fill processes.
-
Longdapac (Hebei, China) — Positioned as a large‑scale producer of single‑material, high‑barrier MDO‑PE films, Longdapac is important for buyers prioritizing scale and cost‑efficiency, especially for commodity packaging categories.
-
Novel Packaging, Silvalac, ISOFlex — Each brings differentiated value—competitive pricing and polymer film expertise (Novel), rigidity‑focused mono‑material films (Silvalac), and BOPP/PET to MDO‑PE transition services with How2Recycle alignment (ISOFlex). Suppliers like these are closing technical gaps and expanding converter choices.
Signals from the field: product launches and collaborations
-
RKW’s mid‑2025 launch of integrated EVOH MDO‑PE films signals that high‑functionality mono‑material options are commercially viable and available to converters and brand owners.
-
Strategic collaborations like the late‑2025 TotalEnergies partnership to develop downgauged unlaminated MDO‑PE for deep‑freeze applications illustrate the industry focus on downgauging and line‑speed optimization—both critical to reduce mass per pack while maintaining barrier performance.
Market dynamics and risk map
Three structural dynamics will dominate boardroom debates in 2026:
-
Regulatory cadence: Tightening packaging regulations in major markets are making recycled‑content mandates and recyclability claims business‑critical, not optional. Adoption speed will differ by market segment, but timing risk is real for businesses delaying material transition.
-
Input cost volatility: Resin price swings and regional HDPE availability continue to inject cost uncertainty into conversion economics. Procurement strategies that incorporate indexed contracts, regional sourcing diversification and value‑share conversations with suppliers will materially de‑risk margins.
-
Performance vs. circularity tradeoffs: While MDO‑PE solutions close many functional gaps, some ultra‑high‑barrier applications still require hybrid or metallic layers. The strategic choice is whether to accept incremental performance differences in return for clear recyclability and simplified end‑of‑life pathways.
2026 playbook — recommended executive actions
-
Mandate cross‑functional pilots: procurement, R&D and sustainability must jointly run application pilots to quantify shelf‑life, downgauging potential and total cost of ownership within 12 months.
-
Supplier qualification with staged commitments: prefer flexible offtake agreements that reward incremental volume growth and include technical KPI clauses (OTR/WVTR, seal integrity, optics).
-
Hedge resin and logistics risk: adopt blended procurement approaches, including regional contracts, strategic safety stock and indexed pricing to protect gross margins.
-
Invest in capability vs. outsourcing analysis: evaluate capex thresholds for installing coating lines or EVOH compounding against strategic supplier partnerships and long‑term cost models.
-
Align brand claims with verification: create consumer‑facing narratives tied to measurable recyclability outcomes and validated by third‑party recyclers to avoid greenwashing risk.
-
Prepare for consolidation and M&A: prioritize targets that fill capability gaps (coating capability, EVOH compounding, regional footprint) to accelerate time to market.
What we deliberately withhold here and why
This preview emphasizes strategic implications and actionable frameworks while intentionally withholding the granular segment tables, regional and application split percentages, and the full price‑sensitivity matrices that drive procurement contracts. Those detailed inputs — including interactive dashboards, downloadable financial models and supplier share analyses — are contained in the full PW Consulting report and our supporting data portal. This “preview” approach is designed to show the analysis depth and practical utility without replacing the full dataset that commercial decision‑makers require for execution.
Conclusion — positioning for 2026
For executives setting 2026 priorities, High‑Barrier MDO‑PE is not merely a product innovation; it is a strategic lever that addresses regulatory compliance, sustainability targets and unit cost pressures simultaneously. The technology is sufficiently mature to support scaled commercialization in many packaging segments, but success will depend on disciplined supplier qualification, joint piloting, and careful cost‑risk management. Our full study contains the granular market splits, supplier scorecards and financial models needed to convert these strategic priorities into operational roadmaps.
To access the complete report, interactive datasets and a tailored briefing for your executive team, visit the PW Consulting research portal or contact our High Barrier MDO‑PE practice lead. The next 12 months will separate companies that merely discuss circularity from those that operationalize it—make 2026 the year your packaging strategy shifts from compliance risk to commercial advantage.
For detailed analysis of this topic, please visit the official page: High Barrier Mdo Pe Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com