

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Pseudoboehmite Market Tops USD 654.6 Million in 2025, Forecast to Reach USD 934.7 Million by 2032 at a 5.22% CAGR

Pseudoboehmite Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
Executive summary
PW Consulting's new Pseudoboehmite Market study (base year 2025; historical 2020–2025; forecast 2026–2032) frames a rapidly maturing specialty alumina market that is consequential for upstream feedstock managers, catalyst and adsorbent manufacturers, and downstream refiners and chemical producers planning capital and procurement decisions in 2026. Our analysis shows the global market expanding at a compound annual growth rate (CAGR) of 5.22% through 2032, with measured expansion from approximately USD 512.5 million in 2020 to USD 654.6 million in 2025 and a projected market size approaching USD 935 million by 2032.
Pseudoboehmite Market
Why this report matters for 2026 corporate decision-making
- Timing of investment: Producers and buyers must align capacity, product qualification and offtake agreements to the mid-cycle phase that begins in 2026 — when feedstock softness and demand rebalancing create both margin pressure and selective opportunity.
- Procurement and cost engineering: Procurement teams need forward-looking price decks and scenario-based hedges for aluminium hydroxide and bauxite inputs; this report provides the quantitative levers and risk matrices to operationalize that hedging across 12–36 month horizons.
- Product and portfolio strategy: The next 24 months separate commodity suppliers from specialty, high-purity or tailored-pore pseudoboehmite producers. Decisions on R&D, product certification, and co-development with catalyst formulators will determine premium capture.
- M&A and partnership roadmap: Mid-market consolidation and strategic alliances—especially between Western specialty manufacturers and Chinese capacity holders—are likely to accelerate. The report outlines target profiles and value-capture mechanics for active and passive investors.
Report scope and actionable content (what’s inside)
- Comprehensive market sizing and a validated top-down/bottom-up forecast (2026–2032) with scenario sensitivity to feedstock price shocks and downstream petrochemical cycles.
- Supply chain heat maps and capability assessments, including plant technology differentiation (alkoxide hydrolysis, PHS series upgrades, dispersion technologies) and typical qualification timelines for catalyst/adsorbent customers.
- Price-driver modelling for upstream inputs and a procurement playbook that translates raw-material pathways into margin-impact levers.
- Competitor benchmarking and strategic profiles of leading producers, with strengths, product portfolios, and go-to-market strategies synthesized into acquisition and partnership playbooks.
- Regulatory and ESG checklists tied to permitting, environmental audits, and social impact considerations that materially affect project timelines and insurance/capital costs.
- Executive-ready strategic recommendations and three investment/operational scenarios (Base, Upside, Downside) tailored for 2026 decision calendars.
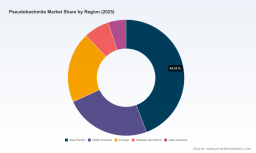
Note: To preserve the utility of this public summary we intentionally withhold detailed regional and application splits, price decks and company-level revenue breakdowns; these are available in the full report.
Pseudoboehmite Market
Market dynamics and raw-material context driving 2026 outcomes
Pseudoboehmite sits at the intersection of refined alumina chemistry and downstream catalyst engineering; as such, midstream feedstock movements directly affect margins and strategic posture. Our short-term tracking identified a notable softening in aluminium hydroxide prices in early 2026, with Northeast Asia experiencing a pronounced decline versus late 2025 and European prices easing more moderately. Bauxite CIF flows into China and the U.S. import price index also reflect loosening upstream cost pressure.
Pseudoboehmite Market
These shifts create a tactical window in 2026: buyers can negotiate improved terms for multi-year supply contracts, while sellers must accelerate differentiation—either through higher-purity grades, enhanced dispersion technology, or integrated catalyst development—to defend pricing. At the same time, volatility in feedstock markets means capacity additions should be staged and underpinned by binding offtake or technology lock-ins to avoid mid-cycle oversupply.
Competitive landscape — who matters and why
The pseudoboehmite market displays moderate concentration: our competitive metrics show that the top three players hold a material portion of the market, with a top-five concentration approaching three-fifths of global volumes. This structure creates both strategic friction and opportunities:
- Sasol Limited — expert in high-dispersion, high-purity pseudoboehmite via alkoxide hydrolysis; well-positioned for catalyst carrier applications in refining and petrochemicals. Their DISPERAL capability underscores a technology-led premium route.
- CHALCO (Aluminium Corporation of China) — scale producer with recent major project certifications and an upgraded PHS series production approach targeting hydrocracking and related catalyst feedstocks. Recent environmental and social assessments and ASI audit outcomes indicate a focus on compliant capacity expansion.
- Honeywell UOP — supplies Versal and related alumina intermediates; strength lies in deep integration with adsorbent and catalyst OEMs, translating product spec control into supply stickiness.
- Nabaltec, Almatis, BASF — European specialty and premium-supply players focusing on niche grades, flame-retardant additives, and high-performance catalyst carriers, which command differentiated margins.
- Chinese and regional specialists — a cohort of dedicated producers concentrated in Shandong and other industrial clusters supplies significant volume and capability for rapid scale-up; their strategies range from commodity volume plays to targeted high-purity and macroporous variants for molecular sieves and catalysts.
Strategically, buyers should evaluate three supplier archetypes when structuring 2026 engagements: (1) Technology-led, premium suppliers with long qualification cycles; (2) Scale-focused producers offering competitive base-grade volumes; (3) Regional specialists providing fast-response capacity but variable long-term reliability. The full report ranks individual firms against these archetypes and includes readiness checklists for qualification and supplier risk.
Regulation, certification and ESG — an operational must for 2026
Environment and social governance considerations are increasingly gatekeepers for project greenlighting and bankable financing. An illustrative case: Chalco Shandong's 10,000 tpa PHS series upgrade completed environmental approvals and an Aluminium Stewardship Initiative audit, and maintained ISO 14001:2015 and ISO 45001:2018 certifications — steps that materially shorten commercial ramp timelines and broaden financing options. Buyers and investors should factor certification status into counterparty selection and contract terms.
Strategic playbook: five priorities for 2026
- Lock in flexible supply, not just price: Negotiate contracts with adaptive volume bands and material-replacement clauses tied to qualification status. Prioritize suppliers who offer staged delivery tied to performance milestones.
- Differentiation through specification: Invest in co-development with catalyst formulators to secure exclusivity on high-purity or tailored-pore grades; even modest specification premiums compound materially over multi-year contracts.
- Hedge feedstock exposure: Use the report’s price-driver models to design layered hedges for aluminium hydroxide and bauxite exposure, combining physical call options, indexed pricing collars and strategic inventory buffers.
- Selective M&A and JVs: Focus acquisition targets on technology (dispersion/alkoxide platforms) and regional capacity that fills logistical gaps; JV structures should embed technology transfer and binding offtake to de-risk greenfield capex.
- ESG and permitting as competitive advantage: Make environmental certification and human-rights due diligence a pre-requisite for strategic suppliers; engaging early reduces timeline uncertainty and can shorten payback periods by improving access to capital.
Methodology and confidence factors
This study synthesizes primary interviews, plant-level capacity audits, trade and customs data, and proprietary pricing models. We reconcile top-down macro indicators with bottom-up plant output and company-reported capacities to produce scenario-tested forecasts. Sensitivity testing highlights three principal levers that explain >80% of forecast variance: downstream petrochemical demand, aluminium hydroxide feedstock price, and the pace of specialty-grade adoption. Our confidence bands are disclosed in the full dataset and are calibrated to permit rolling updates as 2026 data materialize.
How to use this research
Market leaders and investors should treat this brief as a strategic primer: it identifies the decision points and time windows that will determine value capture through the 2026 cycle. For procurement teams, the report delivers the price decks and contract templates needed to convert analysis into defensible purchase strategies. For corporate development and investors, our M&A playbook and target scoring system convert market intelligence into executable deal lists.
Next steps — access to the full intelligence
This communiqué follows the "trailer" principle: it presents the analytical framework, strategic implications and validated market trajectory, while preserving the detailed segmentation tables, supplier revenue splits, and full price-deck models for subscribers. To operationalize the recommendations above — including supplier scorecards, region/application breakouts, and scenario-specific Excel models — please consult the full PW Consulting Pseudoboehmite Market report. The full report contains the granular data and transaction-ready appendices you will need to finalize 2026 budgets, procurement RFPs, and investment decisions.
For detailed analysis of this topic, please visit the official page: Pseudoboehmite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com