

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Chemical & Materials
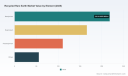
PW Consulting: Recycled Rare Earths to Surge at 12.7% CAGR from USD 550.6M in 2025 to USD 1.27B by 2032 — NdFeB Magnets Lead with USD 384.9M
By pmarketresearch, 2026-07-06
Recycled Rare Earth Market 2026: Strategic Imperatives for Corporate Decision‑Makers
As global supply chains and technology roadmaps pivot toward sustainability and resilience, recycled rare earths have moved from niche sustainability projects to core strategic assets for manufacturers, refiners, and governments. PW Consulting’s latest market study—anchored on 2025 as the base year with a historical review from 2020–2025 and forecasts through 2032—frames recycled rare earths as a rapidly scaling market that will materially influence sourcing, investment, and policy choices in 2026. The market reached roughly USD 550 million in 2025 and, with a compound annual growth rate (CAGR) of 12.7% in our base-case projection, is expected to exceed USD 1.2 billion by 2032. This trajectory creates both opportunity and urgency for corporate strategy teams.
Recycled Rare Earth Market
Why 2026 Is a Pivotal Year
Several convergent forces elevate recycled rare earths to board-level consideration in 2026. First, regulatory and trade dynamics have accelerated supply‑chain realignment: export controls and policy shifts are prompting governments and OEMs to secure non-primary sources of neodymium, dysprosium and related elements. Second, a growing evidence base shows recycled magnet feedstock can offer substantial cost advantages versus primary mining routes—an important commercial lever as manufacturers face margin pressure and decarbonization targets. Third, a wave of capacity expansions and vertically integrated initiatives—from hydrometallurgical hubs to short‑loop magnet-to-magnet processors—is reshaping the competitive map.
Recycled Rare Earth Market
What PW Consulting’s Report Delivers
Our study is designed as an operational playbook for 2026 decisions. Highlights include:
Recycled Rare Earth Market
- Market sizing and scenario forecasts (2026–2032) under alternative policy and demand paths, showing a robust mid‑case growth trajectory at a 12.7% CAGR and downside/upside sensitivities tied to regulatory access and feedstock availability.
- Commercial readiness assessment of recovery and refining technologies—hydrometallurgical routes, hydrogen processing for magnet reconditioning, and short‑loop magnet-to-magnet techniques—mapped to CAPEX intensity, time‑to‑commercial, and impurity tolerance profiles.
- Supply‑chain risk matrices that combine geopolitical exposure, feedstock quality variability, and logistics constraints to produce prioritized mitigation options for OEMs and converters.
- Unit‑economics templates and a price‑scenario engine that translate TREO cost inputs into plant-level margin outcomes—enabling finance teams to stress-test investments and off‑take arrangements.
- A practical M&A and partnership playbook with diligence checklists, technology validation criteria, and contractual safeguards tailored to recycled REE operations.
- Regulatory and incentives tracker that assesses policy levers across major markets and their implications for project economics and procurement strategies.
To preserve competitive value for subscribers, the report omits public disclosure of the granular geographic or application splits and proprietary company-level recovery curves; those are included in the full report and data annex.
Competitive Landscape: Who’s Moving First—and How
The industry is maturing from dispersed pilots into a concentrated set of industrial actors and vertically integrated projects. Current market concentration reflects a moderate level of aggregation—top three firms control a meaningful share of capacity and brand influence, while a broader set of specialized recyclers and technology providers account for expanding processing capability.
- Cyclic Materials (Toronto): Operating North America’s first facility commercializing Mixed Rare Earth Oxide (MREO) from end‑of‑life magnets, Cyclic’s Mag‑Cycle and REEPure hydrometallurgical suite position the company as a hub‑centric processor. Its announced campus expansion in the U.S. signals a scale-up strategy focused on integrated spoke‑and‑hub networks designed to secure feedstock and downstream partnerships.
- MP Materials Corp. (Mountain Pass): As an integrated rare earth producer, MP is pivoting to commercial-scale magnet recycling with closed‑loop ambitions. High-profile offtake commitments and sustainability partnerships underline a model combining primary and recycled feedstocks to serve domestic magnet casters.
- American Resources Corporation (Electrified Materials) : Expansion of pre‑processing at domestic facilities exemplifies the move toward near‑source sorting, demagnetization and pre‑concentration—capabilities that materially affect logistics and yield for downstream refiners.
- HyProMag / Mkango Resources and University of Birmingham partnerships : Short‑loop hydrogen processing and magnet‑to‑magnet recycling offer rapid turnaround for remanufactured magnetic products, reducing reliance on deep chemical refining for certain magnet grades.
- Established recyclers and technology specialists such as Umicore, Geomega, Hitachi Metals, Accurec, REEcycle and Carester: These players bring diverse approaches—ranging from industrial-scale metal recovery to specialized separation and remanufacture—creating an ecosystem where strategic partnerships are as important as outright M&A.
Recent 2025–2026 developments—capacity announcements, hub launches, and commercial offtake commitments—underline a market transitioning to industrial scale. These moves are not merely incremental; they indicate strategic positioning to capture feedstock economics and to lock in OEM relationships as supply chains reconfigure.
Policy, Cost and Supply: Practical Implications for Strategy
Three dynamics will dominate corporate boardroom conversations in 2026:
- Policy-driven re‑routing of supply chains. Export controls and trade measures implemented in recent years are heightening the value of domestically controlled or allied recycling capacity. Companies should model scenarios for restricted access to primary material and quantify the role recycled streams play in hedging supply interruptions.
- Cost arbitrage between recycled and primary TREO. Recycled magnet routes can present materially lower TREO production costs under many feedstock quality assumptions. Our report includes a modular cost model that allows procurement teams to test procurement strategies and to quantify how incremental recycled content improves gross margins across product lines.
- Siting, logistics and feedstock aggregation. The economics of recycling scale with consistent feedstock throughput and pre‑processing quality. Expect a premium on assets and partnerships that can secure municipal and industrial end‑of‑life streams, and on logistics nodes that reduce contamination and handling losses.
Actionable Recommendations for 2026 Decision Timelines
For C‑suite and corporate strategy teams, PW Consulting recommends a prioritized set of actions for 2026:
- Run a rapid supply‑security assessment: quantify how much recycled content is required to meet 2026–2028 product roadmaps under stress‑test scenarios (export controls, tariffs, demand spikes).
- Develop near‑term offtake and feedstock aggregation pilots: lock bilateral supply agreements with electronics recyclers and motors remanufacturers, with staged options to scale into longer‑term off‑takers.
- Consider minority equity or strategic JV stakes in regional processors to secure preferential access and technology transfer—especially where short‑loop magnet refurbishment reduces processing complexity.
- Align procurement and product design: embed design‑for‑disassembly standards that increase recovery yields and lower recycling costs, and update procurement contracts to reward recycled content.
- Update capital allocation frameworks to include recycling projects: assign higher strategic value to lower‑CO2, lower‑risk feedstock projects even when payback profiles differ from primary mining investments.
- Engage proactively with regulators: shape incentive schemes and tariffs and influence standards for recycled REE content and testing protocols.
What the Full Report Contains (Subscriber‑Only)
PW Consulting’s full report expands on the themes above with exclusive content that includes: plant‑level cost build‑ups; proprietary recovery yield curves by technology; company‑specific capability matrices; commercial case studies of closed‑loop supply agreements; and an interactive scenario dashboard that lets users model price and policy shocks. We intentionally withhold proprietary regional and application splits, and detailed company revenue breakdowns from this summary to preserve the actionable value for subscribing organizations.
Final Considerations
2026 will be the year when recycled rare earths stop being a sustainability talking point and become a strategic supply‑chain instrument. Firms that move early to secure feedstock, validate processing partners, and embed recycled content into product roadmaps will reap downstream benefits—price resilience, lower Scope 3 exposure, and access to premium procurement pools. Conversely, organizations that defer may face higher sourcing costs and constrained flexibility as policy and market forces accelerate.
PW Consulting stands ready to support boards, strategy teams, and investment committees with tailored workshops, scenario modeling, and due‑diligence support packages built on the dataset and frameworks in our Recycled Rare Earth Market report. For access to the full analysis, datasets, and interactive tools, please consult PW Consulting’s market research portal or contact our industry team directly.
For detailed analysis of this topic, please visit the official page: Recycled Rare Earth Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sulphur Pastilles Market to Reach USD 1,045.5 Million in 2025, Poised for 4.12% CAGR Through 2032
By pmarketresearch, 2026-07-06
Sulphur Pastilles Market — Strategic Outlook for 2026: Actionable Intelligence from PW Consulting
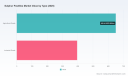
PW Consulting’s new Sulphur Pastilles Market report (base year 2025; forecast period 2026–2032) translates granular market observation into an executable playbook for executive teams planning for 2026. Our analysis shows the market continuing its recovery and structural expansion, with a compounded annual growth rate (CAGR) of 4.12% through the forecast window. The industry grew from an estimated USD 855.2 Million in 2020 to USD 1,045.5 Million in 2025, and is projected to reach USD 1,386.96 Million by 2032 — a trajectory that creates distinct opportunities and tactical risks for producers, distributors and large consumers alike.
Sulphur Pastilles Market
Why this report matters for 2026 decision-making
-
Operational resilience is now a competitive advantage. Rapid raw-material price swings and logistics frictions have compressed margins and elevated working-capital risk; firms that embed volatility into commercial contracts and inventory policy will outpace peers.
Sulphur Pastilles Market -
Regulatory nuances around transport and packaging materially affect cost-to-serve and route-to-market economics. Understanding how formed sulphur is treated across jurisdictions can unlock lower-cost distribution channels.
Sulphur Pastilles Market -
Market structure is neither fully atomized nor tightly oligopolistic: the top-three players account for a significant portion of supply while the top-five increase that concentration — leaving scope for regional champions, premium niche providers and consolidation plays.
-
Product differentiation — through particle form, moisture control, low fines, and micronutrient blends — is becoming a primary margin lever rather than a secondary feature.
What the report delivers (practical & operational)
We designed the report as a decision support toolkit rather than a descriptive survey. Key deliverables include:
-
Transparent forecast models (2026–2032) with scenario toggles for price, demand elasticity and feedstock availability.
-
Commercial playbooks for procurement and pricing including sample contract clauses, indexation strategies and blended-sourcing templates.
-
Supply-chain heat maps identifying pinch points (liquid sulphur bottlenecks, forming capacity, packaging & warehousing constraints) and practical mitigations.
-
Competitive benchmark dossiers (supplier capabilities, technology footprints, logistics networks, and value-add product lines) for buy-side rationalization or sell-side positioning.
-
Risk matrices and investment filters for greenfield capacity, brownfield upgrades and M&A that quantify payback timing under multiple raw-material price paths.
Near-term dynamics shaping 2026 strategy
Two dynamics deserve immediate attention from boards and procurement committees.
-
Raw-material price volatility: Sulphur pricing demonstrated sharp short-term movements in 2026. Market sources recorded a sharp intramonth rally in early April (Trading Economics, April 2026), and region-specific benchmarks in early 2026 show meaningful dispersion across global FOB/CIF points (Analysts Insights, Jan–Mar 2026). Put simply, cost volatility is elevated and regional spreads will materially affect sourcing choices.
-
Regulatory and transport treatment: Formed sulphur—including pastilles—benefits from favorable transport classifications in many jurisdictions when shipped in non‑bulk packaging (PHMSA DOT clarification, June 2021), and equivalent provisions are recognized in other regions (per industry SDS references updated through 2025). That regulatory treatment reduces compliance costs for packaged supply chains and changes the economics of distributed, multi-node warehousing versus centralized bulk shipments.
These dynamics interact with demand drivers that remain durable: fertilizer production, industrial chemical processes and specialty applications such as rubber vulcanization continue to underpin base demand, while incremental gains come from higher-purity and micronutrient-enhanced products used in specialty agriculture and food-grade processes.
Competitive landscape — who moves the market
Industry concentration metrics indicate meaningful presence of large, vertically integrated suppliers while leaving material share for regional specialists and niche innovators (CR3 ≈ 38.5%; CR5 ≈ 52.3%). The practical implication: strategic playbooks should be tuned to both scale advantages and local agility.
-
Martin Midstream Partners L.P. (USA) — Integrated pastille manufacturing in Texas and Illinois; their multi-purpose sulfur offerings and logistics footprint make them a go-to partner for large fertilizer and industrial customers ( https://mmlp.com).
-
Coogee Chemicals (Australia) — Strong chemicals and logistics expertise supporting both industrial and agricultural flows ( https://www.coogee.com.au).
-
Tiger-Sul / Tessenderlo Kerley Inc. (USA) — A global leader in industrial-grade pastilles and value-added blends (sulphur bentonite, micronutrient-enhanced), with processing plants and international warehouses ( https://www.tigersul.com).
-
Georgia Gulf Sulfur Corporation (USA) — Notable for rotoform technology and a long track record in formed pastilles and flakes, providing consistent, higher-uniformity particle forms ( https://www.georgiagulfsulfur.com).
-
Grupa Azoty Siarkopol (Poland) — European supply anchor with industry-standard specifications and large-scale storage solutions ( https://grupaazoty.com).
-
NEAIS / Said Ghodhran Group (Saudi Arabia) — Regional supplier using drop-forming technologies with a focus on agricultural and industrial segments ( https://www.neais.net).
-
Other regionally significant players include Swancorp, Devco Australia Holdings, Brimfert, Passion Ag, BTSCO and Petro Arkan — each offering differentiated supply models, from low‑fines drop-formed pastilles to blended, food-grade variants (company sites and public profiles).
Across the vendor set we see three recurring competitive moves: (1) logistics-led differentiation (packaging, warehousing, freight optimization), (2) product-led differentiation (moisture control, particle size uniformity, micronutrient blends), and (3) commercial-led expansion (long-term offtake agreements with fertilizer producers and large agricultural distributors).
Priority actions for executives in 2026
-
Hedge and index intelligently: Move beyond simple fixed-price contracts. Use blended indexation tied to regional sulphur references, with collar/floor structures to cap extreme downside/upside while preserving upside capture for suppliers.
-
Build optionality in feedstock sourcing: Create multi-hub procurement strategies that can ramp regional supply quickly when local spreads widen. Non-bulk packaging advantages reduce some of the transport cost penalty of multi-node supply.
-
Invest in product differentiation: Premium pastilles with low fines, controlled moisture and micronutrient options command stronger margins and lock in offtake relationships—prioritize R&D and co‑development with anchor customers.
-
Operationalize regulatory opportunity: Exploit favorable transport classifications in commercial routing and distribution economics; align packaging investments to the shape-specific thresholds regulators use.
-
Pursue targeted M&A: Look for bolt-on formations and regional distributors that add immediate route-to-market and storage capacity rather than large-scale greenfield builds; run every target through scenario P&L including 3x raw-material stress tests.
-
Embed scenario-based planning: Adopt three practical scenarios (baseline, price-surge, demand-down) and maintain ready-to-execute playbooks for each—cover procurement, pricing, inventory and customer communications.
-
Operational resilience metrics: Shift KPIs from static inventory days to “service cost-per-ton” and “margin at risk” under price shocks; tie executive incentives to resilience improvements.
How the report supports tactical execution
For teams moving from strategy to execution in 2026, the report provides downloadable tools: Excel models that allow you to re-run forecasts under custom price and demand assumptions, sample supplier contract language, a logistics checklist keyed to packaging thresholds, and a prioritized M&A target list with acquisition filters. We intentionally withhold the full segmentation tables here to preserve the commercial value for report subscribers — the report contains complete regional and application-level breakdowns, supplier-level benchmarking and a clickable interactive model to test your specific scenarios.
Download the full intelligence
PW Consulting’s Sulphur Pastilles Market report is designed for executives who need actionable, defensible and executable guidance for 2026 and beyond. If your board, procurement team or M&A function needs a compact set of tools — forecasts, scenario models, and an operational playbook — the full report and model suite are available for licensed download. For immediate inquiries or tailored briefings, our industry specialists are available to run bespoke sessions that apply the model to your cost base and supply footprint.
Contact PW Consulting to arrange a briefing and obtain the full dataset, supplier benchmarking and downloadable scenario workbooks that will empower your 2026 strategy.
For detailed analysis of this topic, please visit the official page: Sulphur Pastilles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Small-Volume Personal Care Packaging Market Set to Grow at a 4.4% CAGR, New Insights Reveal
By pmarketresearch, 2026-07-06
Small Volume Personal Care Packaging Market: Strategic Outlook for 2026
PW Consulting’s latest market study on Small Volume Personal Care Packaging presents a focused, actionable intelligence package designed to influence executive decisions through 2026 and beyond. Built on a six‑year historical base and a seven‑year forecast horizon, this release synthesizes revenue modeling, supplier mapping, regulatory scenario analysis, and go‑to‑market playbooks—enabling packaging manufacturers, brand owners, and procurement teams to prioritize investments, manage risk, and capture value in a market characterized by steady expansion and accelerating sustainability requirements.
Small Volume Personal Care Packaging Market
Executive snapshot
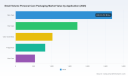
The small volume personal care packaging market recorded steady recovery and growth through the early 2020s and reached a material inflection point by the base year 2025. Our bottom‑up modeling shows the market size at the 2025 base, with a compound annual growth rate (CAGR) of approximately 4.4% across the 2026–2032 forecast period. By 2032 the market is projected to be materially larger than the 2025 baseline, reflecting a combination of premiumization, increased trial and travel formats, and regulatory-driven material transitions.
Small Volume Personal Care Packaging Market
Why 2026 is a strategic inflection point
- Sustainability as a commercial requirement: Regulatory trajectories in multiple U.S. states and other jurisdictions are tightening post‑consumer recycled (PCR) content requirements and expanding producer responsibilities. These rules are shifting cost‑to‑serve and supplier selection calculus for small, rigid and flexible formats alike.
- Material cost volatility: Early‑2026 upward pressure on polyethylene (PE) and polypropylene (PP) feedstocks has increased unit costs for plastic‑dominant small formats, compressing margins for low‑price, high‑volume SKUs while advantaging premium, recyclable or mono‑material designs that command pricing power.
- Format innovation and premium miniaturization: Brands continue to use small‑volume formats to support experiential marketing (sample kits, travel, subscriptions) and premiumization (mini serums, concentrated treatments). Advances in micro‑dispensing, airless systems, and low‑MOQ tooling make new SKU economics viable.
- Fragmented supply landscape: Market concentration is low; the top three suppliers account for less than one fifth of market revenues and the top five for roughly one quarter—creating room for specialist entrants, white‑label manufacturers, and localized players to grow rapidly through service differentiation and niche capabilities.
What the PW Consulting report delivers (practical, board‑ready outputs)
- Strategic playbooks: Scenario‑based recommendations for material strategies (PCR adoption paths, mono‑material transitions), SKU rationalization, and format roadmaps for travel, sample, subscription, and premium segments.
- Commercial modeling tools: Interactive cost‑to‑serve matrices and margin sensitivity models that allow procurement and finance teams to test price, resin, and tooling scenarios against regulatory compliance timelines.
- Supplier intelligence and scorecards: Vendor benchmarking across capability clusters—micro‑dispensing, low‑MOQ runs, sustainable material offerings, and global vs. regional manufacturing footprints—highlighting where to partner, insource, or consolidate.
- Regulatory & compliance playbook: A prioritized map of regional regulatory risks and timelines with compliance pathways and capex/Opex implications for converters and brand owners.
- Market sizing & forecast: Historic performance (2020–2025) and detailed forecasts through 2032 with scenario sensitivity to raw material prices and regulatory adoption rates. (Note: the public summary intentionally omits granular sub‑segment revenue splits; these are included in the full report.)
- Innovation and IP scan: Rapid assessment of emergent dispensing technologies, mono‑material closures, and refill systems that reduce life‑cycle costs and support claims of recyclability and lower carbon intensity.
Competitive landscape: where incumbents and challengers are placing their bets
Our vendor analysis identifies a diverse mix of global leaders, regional specialists and niche innovators. Large multinational converters and system providers have pursued two parallel strategies: (1) broaden product breadth to supply full packaging ecosystems for beauty and personal care; and (2) introduce modular small‑volume platforms (airless micro‑systems, pocket sprays, mini pumps) to capture higher margin, higher frequency SKUs. At the same time, niche players are exploiting low‑MOQ manufacturing, unit‑dose expertise, and close co‑development with indie brands.
Small Volume Personal Care Packaging Market
- Albéa Group (France): Strength in beauty‑grade tubes and bottles with low‑MOQ offerings and r‑material options positions Albéa to win serums, travel sets, and gift‑size SKUs where aesthetic finish and sustainability are decisive.
- Aptar Beauty (U.S.): Deep competency in micro‑dispensing and airless technologies, reinforced by recent product introductions targeted at precision dosing and hygiene, makes Aptar a first call for premium dermocosmetic and high‑viscosity applications.
- Silgan Dispensing (U.S.): Strengths in travel dispensers, foamers and fragrance minis match the sampling and trial strategies of fast‑moving consumer brands.
- Berry Global (U.S.): Investment in smaller stick and refill sizes plus recycled content options reflects a play for mass‑market personal care with sustainability parity.
- HCP Packaging (U.K.): Specialist in color cosmetics compacts and pocket designs—a logical partner for brands prioritizing premium pocketability and makeup refills.
- Amcor (Switzerland): Flexible packaging expertise and paper‑based sachet solutions are central to cost‑efficient sampling and single‑use product strategies with recyclability claims.
- Gerresheimer (Germany): Glass and lightweight decorative solutions appeal to premium skincare and fragrance segments that prioritize perceived quality and recyclability.
- Unit Pack & JP Packaging (U.S.): Unit‑dose and sachet specialists supporting trial, clinical samples and precise topical dosing—key partners for dermatological and technical personal care lines.
Recent vendor activity tracked in our research—product launches expanding mini formats, new automated micro‑fillers, and regional sustainability collections—underscores a fast‑moving competitive dynamic. For decision‑makers, the practical question is not only who can supply, but which supplier reduces regulatory and sourcing risk while improving speed to consumer.
Strategic implications and recommended actions for 2026
- Adopt a PCR transition roadmap now: With state and regional targets escalating over the next decade, brands should model staggered adoption of PCR and identify formats where early conversion yields the best trade‑off between price and consumer credibility.
- Prioritize mono‑material and refillable architectures: Design choices that simplify end‑of‑life processing reduce compliance cost and futureproof claims; these choices also create premium marketing differentiation when backed by verified chain‑of‑custody for recycled content.
- Hedge feedstock exposure: Build multi‑supplier resin agreements and qualify alternative materials (paper laminates, post‑consumer feedstocks) to soften margin shocks from PE/PP price swings.
- Leverage small‑run economics: Use low‑MOQ tooling and regional micro‑factories to support DTC, subscription, and limited‑edition launches while keeping working capital requirements manageable.
- Run prioritized pilot programs: Test high‑value small formats (micro‑dispensing, premium trial kits) in controlled markets to validate unit economics before full rollout.
- Explore consolidation and partnerships: Given the fragmented supplier base, acquisitive strategies and strategic JV models can accelerate capability build versus organic investment—especially for firms lacking micro‑filling or PCR capacity.
Use cases and commercial upside
Small volume packaging is no longer only a sampling tool; it underpins multiple revenue levers. Successful use cases we model in the report include travel and trial formats that increase conversion rates, subscription and refill ecosystems that improve lifetime value, and premium minis that command price premiums in prestige skincare. Each use case is accompanied by a profitability model showing payback periods for tooling and packaging redesign under realistic adoption rates.
Methodology & data integrity
The report’s conclusions are grounded in a hybrid methodology: bottom‑up revenue aggregation, supplier interviews, brand buyer surveys, patent and product launch tracking, and price benchmarking conducted across the 2020–2025 historical window and extended through 2032 using scenario drivers for raw material prices and regulatory adoption. Market concentration metrics and provider scorecards are triangulated with primary supplier disclosures and public filings to ensure defensible strategic guidance.
What is intentionally withheld (and why)
Consistent with the report’s role as a commercial advisory product, this public summary intentionally presents the high‑value strategic frameworks, macro market sizing, and competitive direction without disclosing granular sub‑segment revenue splits and confidential supplier contracts. These detailed sub‑segment matrices, regional/application-by‑format tables, and downloadable modeling workbooks are available in the full report package and are essential for transaction diligence and SKU‑level portfolio decisions.
How to use the full report
- Download the report to access interactive dashboards and the scenario model and to see the full sub‑segment breakdowns that inform SKU rationalization and pricing.
- Use the supplier scorecards to accelerate vendor qualification and to prioritize pilots with partners who can meet PCR and low‑MOQ needs.
- Engage our consulting team for a 90‑day implementation sprint: redesign a pilot SKU, secure pilot tooling, and validate final consumer and cost outcomes ahead of a scaled launch.
PW Consulting’s Small Volume Personal Care Packaging Market study is designed to be an operational catalyst: not just to inform, but to change how packaging teams, procurement, and brand strategy align around formats, materials, and commercial models for 2026. For access to the full data tables, segment granularity, interactive models, and supplier decks, please visit our report page or contact your PW Consulting account lead.
For detailed analysis of this topic, please visit the official page: Small Volume Personal Care Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Essential Rose Oil Market Poised to Grow at a 6.5% CAGR, New Insights Reveal
By pmarketresearch, 2026-07-06
Essential Rose Oil Market: Strategic Imperatives for 2026 — Executive Preview
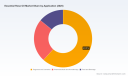
PW Consulting’s latest Essential Rose Oil Market report (base year 2025, forecast 2026–2032) distils five years of historical tracking and a rigorous seven‑year forecast into a decision-ready briefing for strategy teams, procurement heads, and private equity investors. The global market we modelled has expanded materially over 2020–2025 and continues to show resilient growth: the addressable market reached approximately USD 568 million in 2025 and, under our central case, progresses at a compound annual growth rate (CAGR) of 6.5% through the 2026–2032 forecast window.
Essential Rose Oil Market
Why this matters for 2026 decision-makers
- Market momentum: With mid‑single digit CAGR and clear premiumization trends across fragrance, cosmetics and aromatherapy, rose oil is moving from a niche artisanal commodity to a strategic aromatic ingredient with asset‑like supply risks and margin leverage.
- Supply-side concentration and seasonal risk: Production remains geographically concentrated and highly seasonal, which amplifies short-term supply shocks and strategic value for firms that secure differentiated sourcing or upstream exposure.
- Value capture opportunities: Premium traceable and certified organic streams are commanding relative price resilience. Firms that can combine traceability, certification and product development will capture disproportionate margin upside.
- Portfolio implications: For fragrance houses, CPG brands and ingredient distributors, rose oil is no longer a simple raw material — it requires integrated sourcing strategies, risk management, and sustainability programming to support brand claims and regulatory compliance in major markets.
What the report contains — practical, implementable outputs
- Proprietary market model: annualized global market size (historical 2020–2025), topline forecasts to 2032, and scenario analysis (base, upside, downside) to stress-test procurement and pricing strategies.
- Supply‑chain maps: origin country overlays, processing routes, typical quality vectors (otto vs absolute), and traceable pathway design options for premium programs.
- Commercial playbooks: contract templates for forward purchases, clauses to mitigate adulteration risk, indexation approaches to manage price spikes, and negotiation levers for spot versus term business.
- Supplier due‑diligence toolkit: audit checklists, certification matrix, third‑party lab testing protocols, and a methodology to score suppliers on quality, traceability and ESG readiness.
- Competitive benchmarking: strategic profiles of upstream producers, regional industrial processors and global integrators, with capability heatmaps and likely M&A/partnership vectors for 2026–2028.
- Risk heatmaps and scenario playbooks: climate, labour, regulatory and geopolitical stress tests with contingent action plans that scale from tactical (single-season shortages) to strategic (multi-year supply contraction).
- Commercial case studies: procurement and innovation case studies illustrating how leading fragrance houses and brands turned sourcing investments into product premiumization and margin uplift.
Competitive landscape — who matters and why
The competitive set falls into three broad groups: origin‑based growers/distillers, independent processors and distributors, and global fragrance/flavor integrators. Our fieldwork and supplier interviews (Bulgaria, Turkey, France, India and the USA) highlight recurring strategic archetypes:
Essential Rose Oil Market
- Origin growers and distillers (traceability and authenticity): Bulgarian specialists operating from the Rose Valley remain influential due to pedigree, land control and proprietary extraction know‑how. Firms with on‑farm control and modern distillation capacity present premium, traceable supply that commands strategic value for brands seeking provenance claims.
- Independent processors and exporters (scale & documentation): Established exporters and bulk suppliers provide logistical depth and quality documentation supporting flavour and fragrance houses that require validated QC for formulation work.
- Fragrance & flavour integrators (demand shaping): Large fragrance houses and global integrators wield downstream demand and product development muscle; their sustainability and sourcing strategies increasingly set market norms and create pull for certified, verifiable rose oil streams.
Representative companies profiled in the report include origin specialists with field‑to‑bottle models that deliver traceability and organic certification, niche distilleries that supply high‑grade natural fractions, and multinational houses that combine sourcing programs with R&D to capture finished‑goods value. Our competitor profiles assess operational footprint, certification status, sustainability investments, and likely strategic moves — such as direct sourcing partnerships, minority stakes in origin producers, or bolt‑on acquisitions to secure critical volumes.
Essential Rose Oil Market
Recent strategic moves that reshape 2026 playbooks
- Large integrators publicly aligning medium‑term strategies around sustainable, ethically sourced ingredients — an explicit signal that premium, verifiable rose oil will be built into next‑generation perfumery and skincare platforms.
- Origin players increasing investment in certified organic acreage and traceability systems — buyers should expect to pay a premium for predictable, certified tonnage, and should build budget and procurement timelines accordingly.
- Distribution consolidation and cross‑regional acquisitions — distributors are aggregating complementary portfolios to provide national and regional security of supply while offering documented quality chains to global buyers.
Supply dynamics and structural constraints
Rose oil production is inherently labour‑intensive and concentrated in short harvest windows. The combination of seasonal labour dependency, origin concentration and high extraction intensity creates a structural supply elasticity problem: marginal changes in acreage or labour availability translate quickly into price movements. In parallel, certification and traceability requirements — driven by end‑market regulatory scrutiny and consumer expectations — increase the cost of goods delivered for compliant suppliers.
From a market structure perspective, the industry displays limited concentration at the very top: the largest three suppliers together account for roughly one‑third of global supply, and the top five for just under half. That distribution creates room for mid‑market suppliers to influence pricing and for nimble buyers to source differentiated streams through targeted partnerships.
Risks you must price into 2026 plans
- Supply shocks from weather, crop disease or labour constraints during the harvest window.
- Price volatility driven by abrupt shifts in demand from luxury perfumery or large aromatherapy contract wins.
- Sustainability and provenance scrutiny leading to rework costs if documentation or certification is inadequate.
- Adulteration and quality dilution risks that can impair brand claims and result in costly recalls or reformulations.
- Geopolitical and trade flow risks if export policies or preferential treatment change in key origin countries.
Strategic recommendations for 2026 (actionable, prioritized)
- Secure diversified access: Combine long‑term offtake agreements with selective equity or JV exposures in origin producers to lock in certified tonnage for core SKUs.
- Invest in traceability now: Implement supplier scoring and blockchain or batch‑level traceability pilots for premium lines — the near‑term cost is outweighed by enhanced pricing power.
- Hedge tactically: Use a mix of forward contracts and options indexed to quality grades rather than spot exposure to manage seasonal spikes.
- Design premium product architectures: Create tiers (standard, certified organic, fully traceable) with differentiated GTM and margin structures to capture new consumer willingness to pay.
- Build supplier resilience: Co‑finance mechanization, training and certification programs with origin partners to reduce labour risk and improve yield consistency.
- Prioritize quality assurance: Strengthen lab capacities and independent testing clauses in procurement contracts to deter adulteration and protect brand claims.
- Monitor M&A signals: Watch for distributor consolidation and targeted acquisitions by integrators — these will set windows for opportunistic buys or strategic partner approaches.
How PW Consulting’s report supports execution
The report is written for practitioners who must translate market intelligence into executable initiatives. It contains the quantitative backbone (validated market model and scenario outputs), tactical templates (contracts, RFP checklists, supplier audits), and strategic playbooks (sourcing, M&A, product premiumization). We combine primary field interviews across origin regions with third‑party lab validations and a transparent modelling framework so executives can move from insight to procurement and product decisions within a 90‑day planning horizon.
Next steps — access to full intelligence
This executive preview highlights the macro direction and the critical decision levers for 2026. For teams preparing budgets, designing sourcing strategies, or evaluating M&A targets, the full PW Consulting Essential Rose Oil Market report delivers the detailed segmentation, supplier scorecards, contract language and price sensitivity analyses required to act with confidence. To access the complete dataset, granular regional and application splits, and the procurement templates referenced above, please visit our official report landing page and request the full report.
PW Consulting remains available to brief executive teams, run bespoke scenario workshops, and support supplier due diligence or transaction diligence workstreams tailored to 2026 priorities.
For detailed analysis of this topic, please visit the official page: Essential Rose Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts C9 Petroleum Resin Market to Expand at a 4.85% CAGR During 2026–2032
By pmarketresearch, 2026-07-06
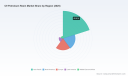
C9 Petroleum Resin Market: Strategic Playbook for 2026 — A PW Consulting Executive Brief
As PW Consulting’s Chief Industry Analyst, I present a concise strategic briefing drawn from our forthcoming C9 Petroleum Resin Market research. This analysis synthesizes an exhaustive assessment of the hydrocarbon-resin value chain, competitive dynamics, and supply-side risk vectors to illuminate the choices facing executives in 2026. Our base-year snapshot indicates the global C9 petroleum resin market reached approximately USD 1.725 billion in 2025 and, given current trajectories, is projected to approach roughly USD 2.40 billion by 2032 — representing a compounded annual growth rate of about 4.85% across the 2026–2032 forecast horizon. These headline numbers frame a market that is mature but still offers selective pockets of expansion, especially for players who act decisively on feedstock strategy, product differentiation, and downstream partnerships.
C9 Petroleum Resin Market
Why 2026 Is a Strategic Inflection Point
Several concurrent trends converge to make 2026 a decision year for producers, converters, and investors:
C9 Petroleum Resin Market
- Feedstock reconfiguration in steam-cracking networks is changing the availability profile of the aromatic C9 fraction, the essential precursor to C9 resins. Decisions now about feedstock sourcing and cracker contracting will determine margin stability for years.
- End-market evolution — notably in adhesives, coatings, and inks — is placing a premium on tailored resin grades (performance, compatibility, and sustainability attributes). The winners will be those who secure technical differentiation rather than compete solely on price.
- Regulatory and reporting clarity on high-molecular-weight hydrocarbon resins reduces a layer of compliance uncertainty in major markets, but downstream customers increasingly expect traceability and low-impact footprints.
Market Dynamics & Supply-Chain Sensitivities
At a high level, the C9 resin market is shaped by a tight interplay between ethylene-cracker feedstock choices and resin production economics. C9 petroleum resin is produced from the aromatic C9 fraction — a byproduct of steam cracking of naphtha and other hydrocarbons. Operators that lean toward ethane cracking reduce their C9 byproduct output versus naphtha crackers, creating localized supply constraints when cracker utilization or feedstock mixes shift.
C9 Petroleum Resin Market
Key implications for 2026 strategy:
- Feedstock exposure matters. Companies with integrated access to naphtha-sourced C9 fractions or long-term offtake agreements will see superior margin resilience compared with spot-dependent converters.
- Price volatility will persist. Upstream feedstock swings transmit quickly to resin margins; scenario planning and hedging instruments should be routine elements of commercial planning.
- Regulatory posture is relatively benign for C9 resins at present: many hydrocarbon resins are assessed as low hazard under chemical assessment frameworks due to their high molecular weight and low volatility. Nevertheless, sustainability and supply transparency are now commercial differentiators even where regulatory risk is limited.
Competitive Landscape — Strategic Profiles and Implications
The competitive field mixes integrated majors, regional specialists, and nimble Chinese producers. Rather than enumerate market shares, our analysis focuses on strategic positioning and capability sets that will determine winners and losers in 2026–2032.
- Kolon Industries (South Korea) — Domestic scale plus product innovation. Kolon’s dual C5/C9 capability and its history of commercializing crosslinkable hydrocarbon resins make it a compelling partner for adhesive and advanced-coating formulators. Strategic implication: Kolon is well placed to pursue premiumization strategies and co-development agreements with formulators seeking performance differentiation.
- Neville Chemical Company (USA) — Secure domestic supply and legacy know-how. With a long track record in C9 aromatic resins, Neville is a preferred supplier where supply security and consistent quality are paramount. Strategic implication: Neville’s positioning plays well to customers seeking onshore alternatives amid global supply uncertainty.
- Eastman Chemical Company (USA) — Portfolio breadth and technical service. Eastman’s integrated hydrocarbon-resin offering, combined with strong downstream technical support, supports value-based selling. Strategic implication: Eastman can extract premium pricing through application engineering and bundled service models.
- Cray Valley / TotalEnergies (France/USA) — Global reach and investment capacity. As part of a larger energy-chemical ecosystem, Cray Valley can optimize feedstock logistics and scale niche grades for inks and adhesives. Strategic implication: look for targeted capacity investments and selective backward integration moves.
- Exxon Mobil (USA) — Feedstock integration advantage. Exxon’s upstream-to-chemical integration gives it low-cost access to C9 feedstocks in certain regions. Strategic implication: aggressive commercial offers in key segments could pressure standalone resin margins unless competitors secure differentiated propositions.
- Chinese manufacturers (multiple specialized players) — Cost-competitive, agile supply. Regional producers deliver flexible grade portfolios and fast-to-market responsiveness. Strategic implication: incumbents in developed markets should expect continued competitive pressure on commodity grades while pursuing higher-margin specialty applications.
Taken together, the competitive field fosters a market dynamic where scale and feedstock integration matter for cost leadership, and technical service and tailored grades matter for premium positioning. The market is neither a pure commodity race nor entirely premiumized — it rewards hybrid strategies.
What Our Full Report Delivers — Practical, Executable Intelligence
PW Consulting’s C9 Petroleum Resin Market report is built as an operator’s toolkit for 2026 decision-making. Key practical modules include:
- Demand model and forecast (2026–2032) with scenario outputs calibrated to feedstock shifts, regional cracker utilization scenarios, and end-use adoption curves.
- Price and margin sensitivity analysis that quantifies the impact of naphtha and C9 fraction price swings on producer economics under multiple contracting structures.
- Supply-risk heatmap and mitigation playbook mapping cracker outages, logistics chokepoints, and alternative feedstock options.
- Go-to-market playbooks for producers and converters: segmentation strategies, premium-grade development roadmap, and value-selling templates tailored to adhesives, coatings, inks, and rubber compounding customers.
- M&A and CapEx decision frameworks with target screening criteria, valuation heuristics for bolt-on resin assets, and integration checklists to preserve margins post-acquisition.
- Sustainability and compliance pathway: lifecycle hotspots, low-impact sourcing levers, and customer-facing disclosure templates that reduce procurement friction in large end-use accounts.
- Competitive dossiers on the leading producers, highlighting strategic intent, capacity levers, and likely moves through 2028.
We intentionally designed the deliverables as tools that senior management, supply-chain leaders, and corporate development teams can adopt immediately — not just as descriptive market commentary.
High-Value Strategic Recommendations for 2026
For executives preparing 2026 plans, our advice is sharply actionable and prioritized by impact and lead time:
- Secure feedstock optionality now. Negotiate flexible offtakes or co-invest in cracker-linked C9 streams. Even limited upstream integration or multi-year naphtha-linked contracts materially reduce margin volatility.
- Differentiate through formulation partnerships. Sponsor co-development projects with key adhesive and coatings customers to lock in demand for specialty grades and capture price premiums.
- Optimize commercial contracts. Move away from pure spot indexation where possible. Introduce hybrid pricing clauses that share upstream cost movements, protecting margins while remaining competitive.
- Target bolt-on capacity where it accelerates access to strategic customers. Small, focused acquisitions that add technical capability or customer intimacy often create outsized value compared with greenfield builds in this sector.
- Invest in traceability and disclosure. Even though regulatory risk is low today, sustainability transparency unlocks procurement programs with multinational formulators and reduces commercial friction.
- Institutionalize scenario-based planning. Embed C9 fraction availability cases into annual planning cycles to ensure procurement, operations, and commercial teams are aligned for stress conditions.
How Executives Should Use the Report
The report is designed for four primary use cases:
- Corporate Strategy: baseline market sizing, growth corridors, and valuation assumptions for capital allocation decisions.
- Commercial Leadership: pricing playbooks, contract templates, and customer segmentation to drive short-term margin recovery and long-term premium growth.
- Supply-Chain & Procurement: feedstock risk matrices, supplier-scorecard frameworks, and contingency planning to reduce exposure to cracker feedstock shifts.
- M&A & Investor Teams: opportunistic acquisition maps, integration checklists, and scenario-based valuations aligned with 2026 market realities.
Accessing the Full Intelligence
This briefing highlights our depth and the kinds of decision-ready outputs we deliver. We intentionally withheld granular regional splits, application-level share tables, and company-level volume data from this note to preserve the report’s role as a strategic asset. The full report contains those core segmented data tables, downloadable models, and interactive scenario dashboards that executives and their teams can apply directly to 2026 planning cycles.
For firms preparing capital plans, contract negotiations, or M&A activity in 2026, the difference between a reactive and a proactive approach will hinge on feedstock control and differentiated product positioning. PW Consulting’s C9 Petroleum Resin report provides the roadmap to convert market insight into executable advantage. To obtain the full dataset, scenario models, and company dossiers, please visit our report page or contact our advisory desk to arrange a briefing.
— PW Consulting, Strategic Insights Team
For detailed analysis of this topic, please visit the official page: C9 Petroleum Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pseudoboehmite Market Set to Expand at 5.22% CAGR, Surpassing USD 934.74 Million by 2032
By pmarketresearch, 2026-07-06
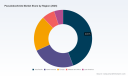
Pseudoboehmite Market — Strategic Brief for 2026 Decision Makers
Executive snapshot
PW Consulting’s latest market study on pseudoboehmite frames a market that has materially expanded over the past half-decade and is set for steady, structurally driven growth through the next planning cycle. Using 2025 as the base year, the market stood at USD 654.64 Million and — under our central-case assumptions — will expand at a compound annual growth rate (CAGR) of 5.22% across the 2026–2032 forecast window, reaching roughly USD 934.74 Million by 2032. Between 2020 and 2025 the market demonstrated resilience, growing from the low hundreds of millions to the current base, and the profile of demand is shifting toward higher-performance grades and more complex value chains.
Pseudoboehmite Market
Why this matters for 2026 strategic planning
Pseudoboehmite is a material enabler for high-value applications (notably catalyst carriers, adsorbents, and advanced speciality materials). For companies that rely on process catalysts, adsorbent media, or engineered alumina products, the market’s trajectory has direct implications for plant economics, product roadmaps, and procurement strategies. The 5.22% CAGR masks a more nuanced reality: growth is concentrated in applications that demand higher-purity and engineered microstructures, while legacy, commodity-grade demand is more exposed to cyclical end-markets.
Pseudoboehmite Market
Market dynamics and supply‑side considerations
- Demand composition is evolving. Advances in hydrocracking, emissions mitigation, and adsorbent formulations are increasing demand for high-dispersity and high-purity pseudoboehmite grades. End-user engineers increasingly specify narrow material property windows (surface area profiles, pore structure, impurity ceilings), which elevates the value of supplier technical services.
- Feedstock and cost pass‑through. Input costs for alumina precursors and upstream bauxite regimes are exerting pressure on producer margins, but regional differences in feedstock access and logistics mean localized cost dynamics are increasingly relevant to sourcing decisions. In short: feedstock volatility matters, but its impact is mediated by a supplier’s access to captive alumina/aluminum hydroxide, scale, and hedging policies.
- Regulatory and sustainability drivers. Environmental and social governance (ESG) factors are now a procurement filter in many of the large refiners and chemical majors. Producers that can demonstrate certified supply chains, environmental assessments, and occupational health standards capture an increasingly large share of new-specification business.
- Technology and grade differentiation. Performance differentiation — not just price — is becoming the decisive procurement variable in many hydroprocessing and adsorbent applications. Suppliers that combine material science expertise with reliable scale-up pathways command premium positioning.
Competitive landscape: who matters and why
The industry remains characterized by a mix of global technology-oriented suppliers, large integrated mineral players, and regional specialty producers. The competitive map matters because suppliers differ along four strategic axes: technological differentiation, scale/capacity, regional footprint, and ESG/compliance credentials.
Pseudoboehmite Market
- Sasol Limited — A technology-driven supplier with strong capabilities in producing highly dispersed, high-purity pseudoboehmite (including established product families). Sasol’s processes and brand recognition in catalyst carrier applications make it a go‑to partner for refiners seeking performance predictability.
- CHALCO / Chalco Shandong Advanced Material — A large-volume producer that has moved aggressively to upgrade capacity for hydrocracking-grade pseudoboehmite. The company’s recent major project approvals and certification activity have signaled a strategic shift toward higher-end refinery applications and an emphasis on audited sustainability credentials.
- Honeywell UOP — Offers branded alumina families that serve both catalyst intermediates and adsorbents; Honeywell’s end-user relationships in refining and petrochemicals provide downstream pull-through for new material specifications.
- Nabaltec AG, Almatis, BASF SE — Positioned as premium suppliers with niche specialities: flame retardant formulations, specialty catalysis, and advanced materials. These firms compete on formulation expertise, consistent quality, and technical support.
- Regional Chinese players and smaller specialists — Several mid-sized Chinese producers and niche firms supply tailored pseudoboehmite variants for local industrial markets and for global customers seeking cost-competitive alternatives. Their strategic relevance is growing where proximity, price, or bespoke product formats matter.
Notably, Chalco Shandong’s move to commission and certify upgraded production lines for hydrocracking applications — including the environmental and social assessments associated with large-capex projects — exemplifies the dual commercial and compliance investment path that incumbent producers are now walking.
Implications for supply risk and procurement
- Supplier selection is multi-dimensional. Price alone will not secure long-term feedstock reliability or product conformity for high-end applications. Procurement must incorporate technical qualification cycles, on-site audits, and contractual SLA mechanisms tied to material performance.
- Diversify by capability, not only by geography. A portfolio approach that spans a technology‑focused global supplier, a high-volume regional producer, and at least one specialty independent will mitigate operational and specification risks.
- Lock in innovation through strategic partnerships. Co-development agreements (R&D collaborations, pilot-run commitments, toll-processing) are effective levers to secure preferential access to advanced grades and to accelerate qualification timelines.
- Sustainability clauses are table stakes. Buyers should integrate upstream audit requirements and supplier remediation roadmaps into RFPs to avoid downstream supply interruptions tied to regulatory or reputational incidents.
Recommended strategic moves for 2026
For corporate leaders scheduling capital allocation and sourcing decisions this year, PW Consulting recommends a three‑tiered action plan that balances defensive and offensive moves.
- Immediate (0–12 months)
- Conduct supplier stress-tests: scenario-run supplier capacity, delivery, and quality resilience under feedstock shock and regulatory tightening.
- Initiate technical qualification with at least two alternative suppliers for critical grades, with explicit performance acceptance criteria and failure remediation pathways.
- Include ESG audit requirements as a mandatory component of procurement contracts for new supply lines.
- Medium (12–36 months)
- Evaluate backward integration or long-term off-take agreements with primary alumina/hydroxide suppliers where margin capture and security of feedstock matter.
- Pursue selective co‑development agreements with a technology partner to secure preferential access to next‑generation pseudoboehmite formulations.
- Consider bolt-on acquisitions or JV structures to secure regional manufacturing footprints where market access bottlenecks or trade frictions exist.
- Organizational
- Build an internal material science assessment cell to reduce time-to-qualify for new grades and to better translate lab metrics into operational guarantees.
- Create cross-functional CAPEX decision frameworks that capture long-term feedstock scenarios, regulatory risk premiums, and carbon/ESG impacts.
What PW Consulting’s full report delivers (high level)
We designed the Pseudoboehmite Market report to be an operational playbook for commercial, procurement, and corporate development teams. Key deliverables include:
- Proprietary demand-sensing model covering 2020–2032 with scenario-paths and sensitivity to feedstock, regulation, and technology adoption.
- Supplier benchmarking and scorecards that evaluate technology, capacity, compliance, and delivery risk.
- Price and margin scenario analysis and an operator-focused CAPEX/OPEX model for greenfield and retrofit lines.
- Supply‑chain risk heatmaps, including logistics and single‑source exposure matrices.
- M&A and partnership playbook: target screening criteria, valuation moats, and a commercial due diligence checklist for buyers and investors.
- Procurement negotiation templates including technical acceptance criteria, SLA language, and ESG audit clauses.
To preserve actionable advantage for subscribers, the report’s full segmentation tables, supplier market shares, and unit-cost schedules are available in the complete release. This executive brief highlights the strategic takeaways while reserving the granular intelligence for the full deliverable.
Closing perspective
As the pseudoboehmite market matures, the winners will be companies that combine materials expertise with robust supply-chain constructs and demonstrable sustainability credentials. The underlying market story is one of steady growth underpinned by structural adoption in higher-value applications — a dynamic that rewards proactive partnering, disciplined procurement, and targeted capital deployment. PW Consulting’s full market study equips decision-makers with the models, supplier intelligence, and transaction playbooks needed to act confidently in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Pseudoboehmite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Diphenylmethanol Market to Rise from USD 398.15 Million in 2025 to USD 552.07 Million by 2032 at a 4.78% CAGR — Asia Pacific Leads with USD 184.94M
By pmarketresearch, 2026-07-06
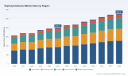
Diphenylmethanol Market Outlook 2026: Strategic Imperatives for Decision-Makers
Executive Snapshot
As PW Consulting’s lead industry analysis for the Diphenylmethanol market, this briefing translates our new market study into targeted strategic guidance for 2026 decision-makers. The global market for diphenylmethanol has shown steady expansion through the historical window and is projected to continue growing across the 2026–2032 forecast horizon at a mid-single-digit compound annual growth rate (CAGR) of approximately 4.78%. Our 2025 base-year modelling signals a clear, investable trajectory: predictable growth with pockets of margin upside for firms that proactively manage feedstock exposure, product-grade differentiation, and regulatory compliance.
Diphenylmethanol Market
Why this matters for 2026 planning
-
Predictability with nuance: A CAGR near 4.8% indicates demand stability rather than hypergrowth — an environment where operational excellence, cost control, and targeted differentiation drive returns more reliably than broad capacity bets.
Diphenylmethanol Market -
Concentration and competition: Market concentration metrics show a moderate level of consolidation: the top three and top five suppliers account for a meaningful share of the market, leaving an accessible runway for specialized or regional players to win niche positions through quality, service, or integrated solutions.
Diphenylmethanol Market -
Feedstock and process exposure: Benzophenone is the dominant upstream feedstock and conventional reduction chemistries remain the production mainstay; raw material dynamics and process selection are therefore principal levers for cost structure and sustainability narratives.
Market trajectory — what the numbers imply
Our analysis integrates historic demand patterns and an exhaustive set of primary and secondary inputs to produce a forward view that balances macro drivers (pharmaceutical production and specialty chemical applications) with micro dynamics (supplier capabilities and feedstock supply). The market in 2025 represents the platform from which near-term strategic choices will compound: modest, predictable growth means companies can capture disproportionate value via margin improvement and selective vertical integration rather than relying solely on volume expansion.
Operational and commercial dynamics to watch in 2026
-
Feedstock security and cost management: Because benzophenone is the primary upstream feedstock and established reduction routes (catalytic hydrogenation, metal-reduction processes such as aluminum/caustic or zinc/alkaline systems) remain standard, procurement strategies that lock favorable benzophenone terms or diversify feedstock pathways will materially reduce volatility.
-
Process choice and CAPEX prioritization: Firms deciding between conventional metal-based reductions and hydrogenation options should weigh capital intensity against unit-cost trajectory and environmental compliance. Investments in hydrogenation catalysts and selective processes can unlock long-term cost and environmental advantages, but require disciplined CAPEX phasing to match demand growth.
-
Grade differentiation: The market rewards clear quality segmentation — pharmaceutical-grade and technical-grade product streams each follow distinct purchasing behaviours. Companies that codify QC workflows, certifications, and supply-chain traceability will extract premium pricing in regulated end-markets.
-
Regulatory posture: Current classification under CLP identifies diphenylmethanol as a skin and eye irritant with specific target organ considerations. It is not presently listed under the most restrictive REACH annexes for authorisation or restriction, a fact that informs near-term go-to-market and export planning but does not eliminate the need for stringent SDS and handling protocols.
Competitive landscape — what differentiates winners
The supplier universe comprises custom synthesis specialists, regional-volume manufacturers, and global laboratory reagent houses. Our qualitative assessment of incumbent players reveals three dominant pathways to competitive advantage:
-
Specialty and custom-synthesis excellence: Companies that offer scale-up capabilities from grams to kilograms with tight purity profiles and bespoke service models hold strong appeal to pharmaceutical developers and specialty end-users.
-
Cost leadership through localized scale: Regional producers that optimize feedstock sourcing and cost structures can serve industrial and agrochemical channels effectively where price sensitivity is higher.
-
Brand trust and distribution reach: Established laboratory and reagent suppliers maintain value in R&D and analytical markets via global distribution networks and trusted standards/grades.
Representative company profiles in our coverage illustrate these archetypes — from Asia-based custom synthesis and specialty-chemical manufacturers to global reagent suppliers with multi-format packaging and quality stewardship. Each profile within the full report includes capability maps, strategic intent indicators, and a supplier-fit framework to align vendor selection with buyer priorities.
Supply chain and manufacturing insights
Operational case work in the study details common process routes and practical implications. Documented production methods include catalytic hydrogenation and metal/alkali reduction chemistries; one mature industrial route uses aluminum powder with caustic soda in methanol as a reductive pathway with subsequent work-up and drying steps. These process choices impact waste streams, operator safety requirements, and capex/opex mixes — and therefore should influence plant design, environmental permitting, and margin modelling in 2026 decisions.
Regulatory and safety context
From a compliance perspective, diphenylmethanol is classified under CLP as Skin Irrit. 2 (H315), Eye Irrit. 2 (H319), and STOT SE 3 (H335). Importantly for exporters and formulators, it is not currently subject to REACH Annex XIV authorisation or Annex XVII restriction listings. While that reduces immediate regulatory friction in relevant jurisdictions, the compound’s hazard profile necessitates robust SDS management, worker-protection programs, and customer-facing documentation — all of which are evaluated in our supplier scorecards.
What the full report contains — pragmatic assets for 2026 execution
-
Actionable scenario analyses: upside/downside demand cases tied to pharmaceutical product pipelines, agrochemical cycles, and specialty formulation trends.
-
Price and margin modelling: input-cost sensitivity analyses that let commercial teams stress-test price floors and corridor strategies under feedstock and energy shocks.
-
Supplier scorecards and diligence templates: standardized assessment tools for procurement and M&A teams to evaluate manufacturing quality, regulatory hygiene, and strategic fit.
-
Investment case frameworks: decision matrices for greenfield versus brownfield expansion, retrofitting hydrogenation capability, and acquisition screening criteria.
-
Go-to-market playbooks: differentiated value propositions and channel strategies for high-purity pharmaceutical intermediates versus industrial-grade supply.
Note: This press summary highlights the practical outputs available in the full study. Detailed segment-level data, regional and application splits, and company market shares are reserved for the report itself to preserve the context and comparability that buyers require when making commercial decisions.
Strategic recommendations for 2026
-
For producers: Prioritize feedstock security and evaluate incremental investments in cleaner hydrogenation technology where feasible. Adopt formalized grade-segmentation commercial strategies to capture higher-margin pharmaceutical demand.
-
For buyers (pharma and specialty formulators): Lock multi-year supply terms with quality clauses and audit rights. Favor suppliers that demonstrate process transparency and upstream-benzophenone traceability.
-
For investors and corporate development teams: Target bolt-on acquisitions that add high-purity production capability or regional distribution footprints. Use the market’s steady CAGR to model disciplined, cash-flow-focused returns rather than aggressive volume expansion.
-
For sustainability and operations leads: Quantify emissions and waste differentials between reduction chemistries and prioritize projects that reduce hazardous byproducts and improve energy efficiency.
How PW Consulting’s study supports 2026 decisions
Our Diphenylmethanol market study is intentionally structured as an operational playbook: it translates market sizing and growth modelling into procurement tools, capex prioritization roadmaps, and supplier-fit diagnostics. It equips C-suite leaders, strategy teams, and commercial heads with the context and instruments needed to translate the market’s predictable growth into sustainable margin and share gains during 2026.
Next steps
For access to the complete dataset, granular segmentation, supplier market shares, and downloadable commercial templates referenced above, please visit PW Consulting’s report portal. The full report contains the detailed regional and application breakdowns, primary interview excerpts, and proprietary pricing models omitted from this summary to preserve comparative integrity for clients and subscribers.
For detailed analysis of this topic, please visit the official page: Diphenylmethanol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ocean Wave Energy Market Poised for Rapid Growth — 16.52% CAGR Projected Through 2032
By pmarketresearch, 2026-07-06
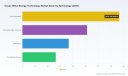
Ocean Wave Energy Technology Market — Strategic Imperatives for 2026
PW Consulting’s latest market research report on Ocean Wave Energy Technology presents a forward-looking playbook for executives, investors, utilities, and technology providers preparing to make consequential decisions in 2026. The wave-energy sector is moving from experimentation to early commercialisation: after growing from an estimated USD 48.5 million in 2020 to USD 95.5 million in 2025, our base-year analysis projects continued expansion to roughly USD 278.5 million by 2032 at a compound annual growth rate (CAGR) of 16.52%. This briefing highlights the report’s strategic value — illustrating where operator economics, policy levers, and technology trajectories intersect — while intentionally withholding granular segmentation tables to encourage direct access to the full dataset and financial models available on our site.
Ocean Wave Energy Technology Market
Executive summary — what this means for 2026 decision-makers
- Market maturation is accelerating: The sector’s high double-digit CAGR through 2032 reflects improving device reliability, larger demonstration projects, and a tightening pathway to utility-scale offtake. The transition from single-unit pilots to modular arrays is now an addressable strategic priority.
- Commercial readiness is technology-specific: Certain device classes have moved into robust grid-connected testing while others remain dependent on further materials and drivetrain innovation. Technology selection now drives near-term partner and procurement strategies.
- Public capital is catalytic: Targeted funding programs and test-facility PPAs have materially de-risked early projects by underwriting R&D, open-water testing, and first-of-a-kind grid connections.
- Unit economics are approaching bankability: Recent field deployments demonstrate meaningful reductions in OPEX relative to CAPEX expectations and highlight operational strategies that materially change project finance assumptions.
- Competitive landscape is moderately concentrated: A small cohort of technology firms is emerging as system integrators and platform providers, but the market still contains room for consolidation, strategic alliances, and vertical integration.
What’s inside the PW Consulting report — practical, transaction-ready content
- Proprietary market-sizing methodology and forecast model (2026–2032) with scenario analysis calibrated to device-class learning curves and sensitivity to CAPEX/OPEX, discount rates, and PPA pricing assumptions.
- Technology readiness and survivability assessments across major device families, including failure-mode analysis, lifecycle maintenance profiles, and retrieval/repair logistics frameworks.
- Project bankability playbook: templated financial models, lender and insurance criteria, typical covenant structures, and staged de-risking milestones that bridge grant-supported demonstrations to commercial lending.
- Operational benchmarks and unit-economics matrices (CAPEX/OPEX presets, availability targets, payload-to-power ratios) informed by recent pilots and commercial tests.
- Regulatory and permitting map aligned to major test facilities and national funding programs, including funding timelines, PPA templates, and grid interconnection challenges.
- Supply-chain heatmaps and procurement strategies for composite structures, power take-off systems, mooring and subsea electrical infrastructure, and logistics for heavy-lift operations.
- Strategic growth options: M&A templates, JV and licensing frameworks, and market-entry pathways for utilities and OEMs seeking to diversify into marine renewables.
- Risk register and mitigation playbook covering environmental impact, survivability under severe weather, material fatigue, and counterparty risk.
Competitive landscape — who is shaping the near-term market
The industry is populated by specialised technology developers and emerging platform players. Our analysis profiles firms that have demonstrated operational traction, differentiated technology concepts, or strategic partnerships that materially shorten the commercialization path.
Ocean Wave Energy Technology Market
- Eco Wave Power (Sweden / Tel Aviv operations) — Commercial onshore wave solutions that retrofit existing marine structures. Recent achievements include the successful U.S. onshore pilot at the Port of Los Angeles and automation upgrades that improved low-wave generation thresholds and data fidelity. The company’s demonstrated OPEX performance on a full operations year has important implications for operational-cost projection assumptions used by lenders and off-takers.
- CorPower Ocean (Sweden) — Compact point absorber technology with high wave-to-wire efficiency and demonstrable survivability in severe storms following deployments at an established European test site. Their biological-inspired hydraulic approach tightens the trade-off between scale and efficiency for arrayed deployments.
- Carnegie Clean Energy (Australia) — Integrated wave-desalination proposition that couples energy generation and water production — an important use-case where co-located demand and avoided grid transport costs can materially improve project IRRs.
- Ocean Power Technologies (United States) — PowerBuoy systems focused on rugged PTO innovations for both utility and remote applications, targeting reliability and modular deployment economics.
- AW-Energy (Finland) — Bottom-mounted oscillating surge converters designed for nearshore operations; their technology’s installation and maintenance profile affects permitting and coastal-use trade-offs.
- Mocean Energy, Oscilla Power, CalWave, ORPC, Seabased, NoviOcean, Marine Power Systems — These firms represent a mix of utility-scale machines, drivetrain innovation, submerged multiphase capture approaches, seabed linear generators, and hybrid platform concepts. Each brings specific advantages for particular geography, water depth, and grid-integration use-cases.
Recent market milestones reinforce the practical pathway to commercialisation. Notably, a U.S. utility-scale PPA covering wave-generated energy from a West Coast test site was executed in late 2025 — a first-of-its-kind contract in the continental U.S. that provides a replicable offtake model for future projects. At the same time, national funding frontiers, such as the U.S. Department of Energy’s multi-year oceans program, are directing meaningful R&D capital toward open-water testing and device maturation.
Ocean Wave Energy Technology Market
Policy, funding and material dynamics — non-technology levers that shape strategy
- Public funding that targets device development and open-water testing is proving catalytic: dedicated multi-year programs have unlocked test-facility build-out and first-of-a-kind PPAs that materially reduce offtaker and lender risk. The presence of dedicated funds improves the expected shaping of market timelines for developers and sponsors.
- Raw-material choices — particularly the growing use of GFRP composites and advanced filament-winding processes — are impacting hull and structural design trade-offs. Procurement strategies for composite fabrication capacity and quality assurance will be differentiators for system cost and durability.
- Test-facility availability and grid access timelines are the binding constraints for 2026 pilots converting to commercial-scale arrays; early access to accredited test sites and long-term offtake commitments will accelerate commercial investment decisions.
Strategic implications — recommended actions for 2026
- For technology developers: Prioritise survivability testing and O&M automation to compress learning curves. Shape pilot contracts that include staged performance milestones and operational-data covenants attractive to lenders.
- For utilities and offtakers: Use early-stage PPAs and offtake options to secure preferential pricing and siting rights while sharing staged performance risk with developers; embed flexibility for technology upgrades.
- For investors and project financiers: Underwrite portfolios of diverse device classes to hedge device-specific risk and accelerate returns via staged equity tranches conditioned on demonstrable OPEX improvements and grid availability.
- For OEMs and supply-chain players: Lock in composite fabrication and PTO supply agreements with scalability clauses that reflect expected volume ramps and evolving design standards.
- For policymakers and regulators: Prioritise test-facility infrastructure, streamlined permitting corridors, and transparent interconnection frameworks to lower transaction costs and attract private capital.
Why this report matters to you
Decisions made in 2026 will determine who captures value as the wave-energy sector moves into the commercial phase. This PW Consulting report equips leadership teams with not only a defensible market forecast and technology assessment, but with executable transaction-level tools — financial models, contractual playbooks, supplier strategies, and regulatory navigators — that bridge demonstrations and scalable projects.
Next steps — access and engagement
The executive summary above distils the actionable judgment clients tell us is most valuable when shaping near-term strategy. Our full report includes the complete forecast model, device-class segmentation, regional demand scenarios, and downloadable financial templates for project-level underwriting. To review the full dataset and obtain bespoke advisory services — including scenario modelling tailored to corporate balance sheets and offtake strategies — visit the PW Consulting Ocean Wave Energy report page or contact our industry team directly.
PW Consulting remains committed to translating marine-innovation potential into investable outcomes. As the industry shifts from pilots to projects, the choices of 2026 will define who leads the wave-energy value chain in the decade ahead.
For detailed analysis of this topic, please visit the official page: Ocean Wave Energy Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Palm Kernel Shells Biomass Market Set to Surge at an 8.5% CAGR to Reach USD 2,318.9 Million by 2032
By pmarketresearch, 2026-07-06
Palm Kernel Shells Biomass Market — Strategic Imperatives for 2026
As global decarbonisation accelerates and thermal generation portfolios are restructured, palm kernel shells (PKS) have emerged from the palm-oil value chain as a strategically important biomass feedstock. PW Consulting’s latest Palm Kernel Shells Biomass Market report (base year 2025) frames the PKS opportunity with a rigorous, forward-looking lens: the market was worth roughly USD 1.31 billion in 2025 and our demand-supply model projects an 8.5% compounded annual growth rate through the forecast window, reaching institutional-scale market sizes by the early 2030s. For decision-makers planning 2026 roadmaps, the report converts this macro momentum into operational actions, risk maps and investment-ready scenarios — while reserving the granular cell-level datasets and company-level volume tables for the full report.
Palm Kernel Shells Biomass Market
Why 2026 Is an Inflection Year
-
Policy and procurement are aligning. A suite of sustainability-driven procurement filters—most visibly certification regimes required for export markets—has shifted buyer behaviour toward traceable, certified PKS. This is changing offtake dynamics and elevating premiums for compliant supply chains.
Palm Kernel Shells Biomass Market -
Supply-side restructuring is underway. Processing capacity additions, plant rationalisations and the emergence of dedicated PKS aggregators have made feedstock availability more market-responsive, but not uniformly so across trading corridors. Logistics chokepoints (port capacity, seasonal vessel availability and inland trucking) remain decisive cost drivers.
Palm Kernel Shells Biomass Market -
Commercial concentration sits in a middle band: the sector is not hyper-consolidated, but neither is it atomised. The competitive geometry leaves room for scale players to secure advantage through integrated supply chains, and for nimble intermediaries to capture margins through logistics and quality arbitrage.
-
Price and risk transmission are intensifying. Macroeconomic variables—including palm oil reference pricing, local export levies and currency movements—feed quickly into PKS export economics. Buyers and producers face several months of lagged, but material, pricing effects as these variables evolve.
What the Report Delivers — Practical, Transaction-Ready Intelligence
The PW Consulting report is built for commercial teams, buyers, asset owners and investors who must convert sector momentum into defensible decisions. Key deliverables include:
-
Proprietary market sizing and a reconciled demand-supply model covering historical 2020–2025 dynamics and forward projections across the 2026–2032 forecast window (methodology, input assumptions and sensitivity runs included).
-
Price-driver decomposition that isolates origin fundamentals, logistics cost components and sustainability-premium mechanics — and translates these into forward price envelopes under alternative macro scenarios.
-
Regulatory and certification matrix connecting country-level export measures, sustainability standards and buyer compliance requirements to offtake and insurance considerations.
-
Operational playbooks for procurement and inbound logistics — tender templates, quality specs and sample contract clauses calibrated to typical PKS grading (net calorific values, ash and moisture specifications) and international shipping practices.
-
Supplier benchmarking and a competitive landscape module: company profiles, capability heatmaps, processing footprints and capacity-change trackers. (Note: granular company volumes and regional/applications splits are only available in the full report.)
-
Transaction support tools: valuation checklists for acquisition targets, due-diligence scorecards for offtake counterparties, and scenario-based investment cases for processing plants and port-side logistics hubs.
Competitive Dynamics — Who Matters and Why
The market ecology is shaped by three archetype players: certified export-focused processors, regional aggregators with buyer linkages, and diversified palm-oil groups that monetise residues as energy feedstock. Leading examples illustrate these roles:
-
Export-focused processors who emphasise certified, traceable product and have expanded processing capacity to serve demanding buyers. Their advantage: faster market access to sustainability-conscious buyers and the ability to capture contract premiums.
-
Regional trading houses and industrial buyers that combine long-term supplier relationships with flexible delivery nodes across Southeast Asia. Their advantage: lower logistical friction and the ability to tailor delivery schedules to utility ramp profiles.
-
Integrated plantation and milling groups that treat PKS as a closed-loop complement to their core operations, supplying both domestic industrial boilers and export markets. Their advantage: feedstock security and internal price arbitrage opportunities.
Recent industry actions illustrate the strategic choices companies are making: capacity additions in strategic coastal locations, multi-year offtake agreements with sustainability clauses, and new long-haul shipments into established biomass markets. These moves confirm two structural themes: certification and logistics access are the immediate value multipliers; and scale in processing plus export capability materially improves negotiating leverage with large buyers and utilities.
Regulatory and Quality Constraints — Operational Realities
-
Certification requirements in key import markets have real economic consequences. Compliance regimes that verify origin and processing chain integrity shape which tonnes are contractable on long-term terms.
-
Origin-level trade measures and export administration changes can tighten or loosen realisable export economics. Even modest changes to export tariffs or service fees materially shift the margin calculus for both exporters and buyers.
-
Technical specifications matter in procurement: calorific value bands, ash content and moisture drive boiler performance, handling systems and downstream emission profiles. Buyers increasingly specify these parameters to reduce plant risk and maintenance costs.
Strategic Actions for 2026 — Tactical Steps with Immediate Payback
For corporate leaders planning budgets and contracts in 2026, the report recommends a focused set of executable steps that can be initiated in quarters rather than years.
-
Secure multi-year offtake frameworks that include flexibility clauses for modal choice and force majeure calibrated to seasonality. Prioritise counterparties that accept staggered pricing collars rather than rigid floor/ceiling structures.
-
Invest in certification and traceability early. The incremental operational cost of documented chain-of-custody is often exceeded many times over by the price premium and counterparty access it unlocks.
-
Conduct logistics-to-market audits. Small reductions in port dwell time and vessel scheduling uncertainty can yield outsized margin improvements across contracted volumes.
-
Calibrate procurement to quality tiers. A deliberate blend of screened and unscreened product, matched to buyer technical tolerance, can optimise yield while avoiding costly downgrades at delivery.
-
Prepare contingency sourcing corridors. Diversifying supply nodes, even within the same country, reduces exposure to localized levies, mill outages and transport disruptions.
Investment & M&A Radar
Investors and strategic buyers should prioritise assets that combine three attributes: processing capacity with modular scalability, deep buyer offtake relationships (preferably with sustainability clauses), and resilient port/rail access. Our transaction playbook—which includes due diligence templates and valuation sensitivities—targets these attributes, emphasising the need to stress-test projections against alternative palm oil price paths and regional trade-policy shifts.
Risk Management — What Keeps CFOs Awake
-
Policy volatility in originating countries that can change export economics quickly.
-
Quality divergence between batch receipts and contractual specs that can trigger penalties or rejection risk at destination boilers.
-
Logistics and vessel availability, where a single bottleneck can cascade into missed offtake deliveries and credit exposure.
Why PW Consulting’s Report Is Different
We combine a granular operational view (tender templates, QC checklists, port-rotation maps) with a robust macro model that produces scenario-weighted forecasts. Our market-concentration metrics and company capability matrices offer a diagnostic not found in commodity-only studies: we show where value accrues in the commercial chain and provide the implementation tools commercial teams need to capture it.
How to Use This Insight in 2026
-
Procurement teams: use the modelled price envelopes and tender templates to design contracts that reduce basis risk and lock in certified capacity.
-
Asset owners: use the scenario toolset to validate investments in processing or port-capacity expansions and to quantify payback under different demand-growth trajectories.
-
Investors and M&A advisers: apply the due diligence scorecards and consolidation playbook to prioritise targets that are most likely to deliver accretive margin expansion.
Next Steps
The summary here highlights the structural logic and actionable directions for corporates and investors considering PKS in 2026. To access the full intelligence — including detailed regional and application breakouts, company-level benchmarking, contract clause templates and the complete dataset underpinning our forecast — please consult the full Palm Kernel Shells Biomass Market report. PW Consulting offers bespoke briefings and implementation support packages to translate this market-level view into transactional milestones and operational change programs.
In a market growing at a mid-single-digit to high-single-digit compound rate and shifting under the twin forces of sustainability and logistics, 2026 is the year to convert strategic intent into measurable advantage. Our report gives you both the high-level map and the on-the-ground tools required to act with speed and conviction.
For detailed analysis of this topic, please visit the official page: Palm Kernel Shells Biomass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Robust Growth for Polymer Reinforcing Filler Market — From USD 14,250.6 Million in 2025 to USD 20,730.1 Million by 2032 at a 5.5% CAGR
By pmarketresearch, 2026-07-06
Polymer Reinforcing Filler Market — Strategic Outlook for 2026
Executive summary
PW Consulting’s latest Polymer Reinforcing Filler Market report delivers a pragmatic, decision-focused view of a market that has moved from niche engineering inputs to strategic raw materials for polymer value chains. The global market reached a robust base in 2025 (reported in USD Million terms) and — under a set of plausible demand, supply and technology scenarios — is projected to grow at a compound annual growth rate (CAGR) of approximately 5.5% through the 2026–2032 forecast window. By 2032 the market is expected to be substantially larger than its 2025 base, reflecting continued substitution, composite adoption, and parallel developments in circular feedstocks and specialty grades.
Polymer Reinforcing Filler Market
Why this matters for 2026 corporate decision-making
- Strategic sourcing: Reinforcing fillers are no longer commodity line items: variations in grade, surface treatment, and carbon footprint directly affect polymer performance, regulatory compliance and the lifecycle impact of finished goods.
- CapEx and footprint planning: Supply-side moves — capacity investments, regional expansions, and new processing technologies — require buyers and compounders to rethink single-sourcing strategies and lead times.
- Product roadmaps and differentiation: R&D choices around filler selection (e.g., glass fiber vs. specialty silica vs. engineered carbon blacks) are becoming a primary means to tune stiffness, durability and recyclability — and therefore to differentiate in automotive, construction and packaging end-markets.
- ESG and circularity: Emerging low‑carbon, recycled and chemically recycled reinforcing fillers are changing supplier selection criteria — procurement teams must integrate lifecycle assessments into commercial scoring and specifications.
Market snapshot (what the numbers say)
PW Consulting’s model synthesizes five years of historic performance (2020–2025) and projects through 2032. The market exhibited resilience through recent volatility, and our scenario-driven forecasting indicates steady expansion through the forecast period at an average CAGR of ~5.5%. This growth is fuelled by continuous innovation in specialty grades, rising composite penetration in weight-sensitive applications, and incremental substitution toward engineered mineral fillers and advanced carbon-based solutions.
Polymer Reinforcing Filler Market
Competitive landscape — who shapes the market
The reinforcing filler market sits between oligopoly and fragmented supply: the largest three players account for a meaningful share of the market but there remains a long tail of regional and specialty producers. PW Consulting’s concentration analysis shows a mid-range consolidation dynamic: the top three and top five players together hold a dominant yet non-controlling slice of global supply, leaving room for agile entrants and technology-driven disrupters.
Polymer Reinforcing Filler Market
- Cabot Corporation (Boston, MA) — A global leader in reinforcing carbons and specialty carbon blacks. Cabot is extending circular and low‑carbon offerings and pursuing partnerships to accelerate commercial adoption of circular reinforcing carbons.
- Birla Carbon (Aditya Birla Group) (Mumbai) — A major vertically integrated carbon black supplier with recent capacity moves to support polymer reinforcement demand and specialty grades for high-performance applications.
- Imerys S.A. (Paris) — A leading mineral filler supplier, focusing on engineered calcium carbonates, kaolin and talc variants that improve stiffness and dimensional stability in polymers.
- Omya AG (Oftringen) and Minerals Technologies Inc. (New York) — Both emphasize optimized mineral fillers and surface treatments to improve dispersion and reinforce mechanical properties in plastics and elastomers.
- Owens Corning and specialty compounders such as RTP Company — Key for glass-fiber reinforcement and custom compound solutions that bridge raw-material capability and application-level performance.
- Specialty and emerging players such as Plastic Energy, Huber, Hoffmann Mineral, LKAB Minerals and 20 Microns bring differentiated chemistries, recycled feedstocks and regional market access — all of which matter for tailored product strategies.
Recent competitive moves illustrate the market’s dual dynamic: incumbents expanding capacity and specialty portfolios while new entrants commercialize lower‑carbon or recycled fillers. These developments create immediate procurement and partnership opportunities for firms willing to move early.
Recent developments shaping 2026 strategy
- Major carbon black suppliers announced capacity and partnership initiatives to accelerate circular carbon adoption and broaden geographic production capability, indicating an industry pivot toward lower‑emission carbon fillers.
- Specialty mineral suppliers launched new silica and calcium carbonate product lines optimized for automotive polymers and packaging — a direct response to demand for better thermal stability and recyclability compatibility.
- Commercialization of recycled and chemically recycled reinforcing fillers has reached market entry stage in several jurisdictions, and one such product has secured regulatory registration enabling commercial use in Europe.
What the PW Consulting report contains — practical assets for executives
Beyond narrative, the report is structured as an operational toolkit for commercial, R&D and procurement leaders. Highlights include:
- Bottom‑up market sizing and consensus forecasts with scenario toggles for demand shocks, substitution and regulatory impacts.
- Supplier scorecards and an objective benchmarking framework combining technical capability, sustainability metrics, geographic reach and commercial terms.
- Price and margin sensitivity matrices that map raw‑material price moves to compounder and OEM P&L under multiple pass‑through regimes.
- Go‑to‑market playbooks for launching new filler-enabled compounds, including target customer segments, sample-pack strategies, and trial-to-qualification timelines.
- CapEx decision models and decision trees for capacity partnerships, greenfield versus brownfield expansion, and toll-processing options.
- M&A and JV blueprints identifying acquisition targets by technology, geography and capability band, with high-level valuation heuristics and integration risk checklists.
- Regulatory and sustainability roadmap including lifecycle assessment templates, compliance checkpoints and communications guidance for supplier contracts.
Strategic implications and actionable recommendations for 2026
We translate the market view into six priority actions that should inform board-level and executive decisions in 2026:
- Reclassify filler selection as a strategic lever: Move filler selection upstream into product design and procurement scorecards to capture performance and sustainability value rather than treating it as a last‑mile commodity choice.
- Secure flexible supply and engage in capacity partnerships: Hedge against regional supply risk by qualifying multiple suppliers across different technology nodes (e.g., engineered mineral, specialty silica, recycled carbon) and negotiate volume-flex contracts that include quality and carbon metrics.
- Invest selectively in co‑development: Pursue co‑development pilots with suppliers to tailor surface treatments or hybrid filler systems that enable weight reduction, cost down, or easier recycling — seek commercial options that convert pilot success into scaled supply agreements.
- Fast‑track low‑carbon alternatives where value accrues: Prioritize adoption of validated recycled and chemically recycled reinforcing fillers in product lines where carbon intensity commands a premium or where regulatory pressure is acute.
- Build a price‑sensitivity playbook: Model pass‑through impacts in your segments and set trigger-points for renegotiation, hedging or formula indexation tied to raw‑material benchmarks.
- Use M&A strategically: Consider tuck‑ins for specialty grades and regional players to accelerate technical capability, or JVs with recyclers to secure circular feedstock in markets with elevated sustainability requirements.
Near-term (0–90 days) and medium-term (6–12 months) action plans
PW Consulting recommends a two-horizon activation approach to convert insight into outcomes.
- 0–90 days: Conduct supplier risk mapping and qualify at least two alternative suppliers per high‑risk polymer line; launch lifecycle audits for top 3 SKUs by volume; initiate pilot discussions with one recycled filler provider.
- 6–12 months: Execute co‑development pilots converting at least one product family to a lower‑carbon filler where technical parity is achievable; finalize at least one strategic supply agreement with contractual SLAs on quality and carbon reporting; incorporate filler choices into product cost models and customer value propositions.
Risk factors and mitigations
Key risks include raw-material pricing swings, regulatory shifts related to additives and recycled content, and technology risk around scale-up of novel filler chemistries. PW Consulting’s report supplies probabilistic scenario maps and mitigation playbooks — from strategic inventory buffers and contractual indexation to accelerated qualification protocols and insurance-backed logistics solutions.
How to use the full report
This market brief is intentionally selective — offering the analytical framing and strategic recommendations you need to act in 2026 while limiting granular segment tables and price series to the full report. PW Consulting’s complete dataset and appendices include detailed regional and application-level forecasts, supplier-by-grade benchmarking, raw-material price time series and downloadable decision-support models that operational teams can drop directly into procurement, R&D and corporate planning workflows.
Conclusion — where value will be captured in 2026
The next 12–18 months will separate winners and laggards. Companies that treat reinforcing fillers as strategic inputs — integrating technical selection, supplier partnerships and carbon metrics into product roadmaps — will capture margin, customer‑facing differentiation and regulatory resilience. PW Consulting’s Polymer Reinforcing Filler Market report is designed to be the playbook for those decisions: rigorous, actionable and tailored to the operational realities facing procurement, R&D and corporate strategy teams in 2026.
To access the full dataset, supplier scorecards and decision-support tools referenced here, visit our report landing page — the granular segmentation and downloadable models are available there for subscription clients and enterprise licenses.
For detailed analysis of this topic, please visit the official page: Polymer Reinforcing Filler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com