

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Sulphur Pastilles Market to Reach USD 1,045.5 Million in 2025, Poised for 4.12% CAGR Through 2032

Sulphur Pastilles Market — Strategic Outlook for 2026: Actionable Intelligence from PW Consulting
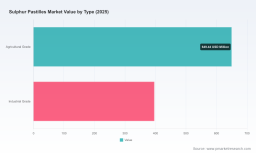
PW Consulting’s new Sulphur Pastilles Market report (base year 2025; forecast period 2026–2032) translates granular market observation into an executable playbook for executive teams planning for 2026. Our analysis shows the market continuing its recovery and structural expansion, with a compounded annual growth rate (CAGR) of 4.12% through the forecast window. The industry grew from an estimated USD 855.2 Million in 2020 to USD 1,045.5 Million in 2025, and is projected to reach USD 1,386.96 Million by 2032 — a trajectory that creates distinct opportunities and tactical risks for producers, distributors and large consumers alike.
Sulphur Pastilles Market
Why this report matters for 2026 decision-making
-
Operational resilience is now a competitive advantage. Rapid raw-material price swings and logistics frictions have compressed margins and elevated working-capital risk; firms that embed volatility into commercial contracts and inventory policy will outpace peers.
Sulphur Pastilles Market -
Regulatory nuances around transport and packaging materially affect cost-to-serve and route-to-market economics. Understanding how formed sulphur is treated across jurisdictions can unlock lower-cost distribution channels.
Sulphur Pastilles Market -
Market structure is neither fully atomized nor tightly oligopolistic: the top-three players account for a significant portion of supply while the top-five increase that concentration — leaving scope for regional champions, premium niche providers and consolidation plays.
-
Product differentiation — through particle form, moisture control, low fines, and micronutrient blends — is becoming a primary margin lever rather than a secondary feature.
What the report delivers (practical & operational)
We designed the report as a decision support toolkit rather than a descriptive survey. Key deliverables include:
-
Transparent forecast models (2026–2032) with scenario toggles for price, demand elasticity and feedstock availability.
-
Commercial playbooks for procurement and pricing including sample contract clauses, indexation strategies and blended-sourcing templates.
-
Supply-chain heat maps identifying pinch points (liquid sulphur bottlenecks, forming capacity, packaging & warehousing constraints) and practical mitigations.
-
Competitive benchmark dossiers (supplier capabilities, technology footprints, logistics networks, and value-add product lines) for buy-side rationalization or sell-side positioning.
-
Risk matrices and investment filters for greenfield capacity, brownfield upgrades and M&A that quantify payback timing under multiple raw-material price paths.
Near-term dynamics shaping 2026 strategy
Two dynamics deserve immediate attention from boards and procurement committees.
-
Raw-material price volatility: Sulphur pricing demonstrated sharp short-term movements in 2026. Market sources recorded a sharp intramonth rally in early April (Trading Economics, April 2026), and region-specific benchmarks in early 2026 show meaningful dispersion across global FOB/CIF points (Analysts Insights, Jan–Mar 2026). Put simply, cost volatility is elevated and regional spreads will materially affect sourcing choices.
-
Regulatory and transport treatment: Formed sulphur—including pastilles—benefits from favorable transport classifications in many jurisdictions when shipped in non‑bulk packaging (PHMSA DOT clarification, June 2021), and equivalent provisions are recognized in other regions (per industry SDS references updated through 2025). That regulatory treatment reduces compliance costs for packaged supply chains and changes the economics of distributed, multi-node warehousing versus centralized bulk shipments.
These dynamics interact with demand drivers that remain durable: fertilizer production, industrial chemical processes and specialty applications such as rubber vulcanization continue to underpin base demand, while incremental gains come from higher-purity and micronutrient-enhanced products used in specialty agriculture and food-grade processes.
Competitive landscape — who moves the market
Industry concentration metrics indicate meaningful presence of large, vertically integrated suppliers while leaving material share for regional specialists and niche innovators (CR3 ≈ 38.5%; CR5 ≈ 52.3%). The practical implication: strategic playbooks should be tuned to both scale advantages and local agility.
-
Martin Midstream Partners L.P. (USA) — Integrated pastille manufacturing in Texas and Illinois; their multi-purpose sulfur offerings and logistics footprint make them a go-to partner for large fertilizer and industrial customers ( https://mmlp.com).
-
Coogee Chemicals (Australia) — Strong chemicals and logistics expertise supporting both industrial and agricultural flows ( https://www.coogee.com.au).
-
Tiger-Sul / Tessenderlo Kerley Inc. (USA) — A global leader in industrial-grade pastilles and value-added blends (sulphur bentonite, micronutrient-enhanced), with processing plants and international warehouses ( https://www.tigersul.com).
-
Georgia Gulf Sulfur Corporation (USA) — Notable for rotoform technology and a long track record in formed pastilles and flakes, providing consistent, higher-uniformity particle forms ( https://www.georgiagulfsulfur.com).
-
Grupa Azoty Siarkopol (Poland) — European supply anchor with industry-standard specifications and large-scale storage solutions ( https://grupaazoty.com).
-
NEAIS / Said Ghodhran Group (Saudi Arabia) — Regional supplier using drop-forming technologies with a focus on agricultural and industrial segments ( https://www.neais.net).
-
Other regionally significant players include Swancorp, Devco Australia Holdings, Brimfert, Passion Ag, BTSCO and Petro Arkan — each offering differentiated supply models, from low‑fines drop-formed pastilles to blended, food-grade variants (company sites and public profiles).
Across the vendor set we see three recurring competitive moves: (1) logistics-led differentiation (packaging, warehousing, freight optimization), (2) product-led differentiation (moisture control, particle size uniformity, micronutrient blends), and (3) commercial-led expansion (long-term offtake agreements with fertilizer producers and large agricultural distributors).
Priority actions for executives in 2026
-
Hedge and index intelligently: Move beyond simple fixed-price contracts. Use blended indexation tied to regional sulphur references, with collar/floor structures to cap extreme downside/upside while preserving upside capture for suppliers.
-
Build optionality in feedstock sourcing: Create multi-hub procurement strategies that can ramp regional supply quickly when local spreads widen. Non-bulk packaging advantages reduce some of the transport cost penalty of multi-node supply.
-
Invest in product differentiation: Premium pastilles with low fines, controlled moisture and micronutrient options command stronger margins and lock in offtake relationships—prioritize R&D and co‑development with anchor customers.
-
Operationalize regulatory opportunity: Exploit favorable transport classifications in commercial routing and distribution economics; align packaging investments to the shape-specific thresholds regulators use.
-
Pursue targeted M&A: Look for bolt-on formations and regional distributors that add immediate route-to-market and storage capacity rather than large-scale greenfield builds; run every target through scenario P&L including 3x raw-material stress tests.
-
Embed scenario-based planning: Adopt three practical scenarios (baseline, price-surge, demand-down) and maintain ready-to-execute playbooks for each—cover procurement, pricing, inventory and customer communications.
-
Operational resilience metrics: Shift KPIs from static inventory days to “service cost-per-ton” and “margin at risk” under price shocks; tie executive incentives to resilience improvements.
How the report supports tactical execution
For teams moving from strategy to execution in 2026, the report provides downloadable tools: Excel models that allow you to re-run forecasts under custom price and demand assumptions, sample supplier contract language, a logistics checklist keyed to packaging thresholds, and a prioritized M&A target list with acquisition filters. We intentionally withhold the full segmentation tables here to preserve the commercial value for report subscribers — the report contains complete regional and application-level breakdowns, supplier-level benchmarking and a clickable interactive model to test your specific scenarios.
Download the full intelligence
PW Consulting’s Sulphur Pastilles Market report is designed for executives who need actionable, defensible and executable guidance for 2026 and beyond. If your board, procurement team or M&A function needs a compact set of tools — forecasts, scenario models, and an operational playbook — the full report and model suite are available for licensed download. For immediate inquiries or tailored briefings, our industry specialists are available to run bespoke sessions that apply the model to your cost base and supply footprint.
Contact PW Consulting to arrange a briefing and obtain the full dataset, supplier benchmarking and downloadable scenario workbooks that will empower your 2026 strategy.
For detailed analysis of this topic, please visit the official page: Sulphur Pastilles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com