

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Ocean Wave Energy Market Poised for Rapid Growth — 16.52% CAGR Projected Through 2032

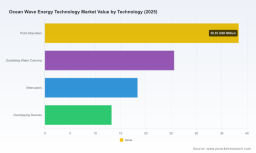
Ocean Wave Energy Technology Market — Strategic Imperatives for 2026
PW Consulting’s latest market research report on Ocean Wave Energy Technology presents a forward-looking playbook for executives, investors, utilities, and technology providers preparing to make consequential decisions in 2026. The wave-energy sector is moving from experimentation to early commercialisation: after growing from an estimated USD 48.5 million in 2020 to USD 95.5 million in 2025, our base-year analysis projects continued expansion to roughly USD 278.5 million by 2032 at a compound annual growth rate (CAGR) of 16.52%. This briefing highlights the report’s strategic value — illustrating where operator economics, policy levers, and technology trajectories intersect — while intentionally withholding granular segmentation tables to encourage direct access to the full dataset and financial models available on our site.
Ocean Wave Energy Technology Market
Executive summary — what this means for 2026 decision-makers
- Market maturation is accelerating: The sector’s high double-digit CAGR through 2032 reflects improving device reliability, larger demonstration projects, and a tightening pathway to utility-scale offtake. The transition from single-unit pilots to modular arrays is now an addressable strategic priority.
- Commercial readiness is technology-specific: Certain device classes have moved into robust grid-connected testing while others remain dependent on further materials and drivetrain innovation. Technology selection now drives near-term partner and procurement strategies.
- Public capital is catalytic: Targeted funding programs and test-facility PPAs have materially de-risked early projects by underwriting R&D, open-water testing, and first-of-a-kind grid connections.
- Unit economics are approaching bankability: Recent field deployments demonstrate meaningful reductions in OPEX relative to CAPEX expectations and highlight operational strategies that materially change project finance assumptions.
- Competitive landscape is moderately concentrated: A small cohort of technology firms is emerging as system integrators and platform providers, but the market still contains room for consolidation, strategic alliances, and vertical integration.
What’s inside the PW Consulting report — practical, transaction-ready content
- Proprietary market-sizing methodology and forecast model (2026–2032) with scenario analysis calibrated to device-class learning curves and sensitivity to CAPEX/OPEX, discount rates, and PPA pricing assumptions.
- Technology readiness and survivability assessments across major device families, including failure-mode analysis, lifecycle maintenance profiles, and retrieval/repair logistics frameworks.
- Project bankability playbook: templated financial models, lender and insurance criteria, typical covenant structures, and staged de-risking milestones that bridge grant-supported demonstrations to commercial lending.
- Operational benchmarks and unit-economics matrices (CAPEX/OPEX presets, availability targets, payload-to-power ratios) informed by recent pilots and commercial tests.
- Regulatory and permitting map aligned to major test facilities and national funding programs, including funding timelines, PPA templates, and grid interconnection challenges.
- Supply-chain heatmaps and procurement strategies for composite structures, power take-off systems, mooring and subsea electrical infrastructure, and logistics for heavy-lift operations.
- Strategic growth options: M&A templates, JV and licensing frameworks, and market-entry pathways for utilities and OEMs seeking to diversify into marine renewables.
- Risk register and mitigation playbook covering environmental impact, survivability under severe weather, material fatigue, and counterparty risk.
Competitive landscape — who is shaping the near-term market
The industry is populated by specialised technology developers and emerging platform players. Our analysis profiles firms that have demonstrated operational traction, differentiated technology concepts, or strategic partnerships that materially shorten the commercialization path.
Ocean Wave Energy Technology Market
- Eco Wave Power (Sweden / Tel Aviv operations) — Commercial onshore wave solutions that retrofit existing marine structures. Recent achievements include the successful U.S. onshore pilot at the Port of Los Angeles and automation upgrades that improved low-wave generation thresholds and data fidelity. The company’s demonstrated OPEX performance on a full operations year has important implications for operational-cost projection assumptions used by lenders and off-takers.
- CorPower Ocean (Sweden) — Compact point absorber technology with high wave-to-wire efficiency and demonstrable survivability in severe storms following deployments at an established European test site. Their biological-inspired hydraulic approach tightens the trade-off between scale and efficiency for arrayed deployments.
- Carnegie Clean Energy (Australia) — Integrated wave-desalination proposition that couples energy generation and water production — an important use-case where co-located demand and avoided grid transport costs can materially improve project IRRs.
- Ocean Power Technologies (United States) — PowerBuoy systems focused on rugged PTO innovations for both utility and remote applications, targeting reliability and modular deployment economics.
- AW-Energy (Finland) — Bottom-mounted oscillating surge converters designed for nearshore operations; their technology’s installation and maintenance profile affects permitting and coastal-use trade-offs.
- Mocean Energy, Oscilla Power, CalWave, ORPC, Seabased, NoviOcean, Marine Power Systems — These firms represent a mix of utility-scale machines, drivetrain innovation, submerged multiphase capture approaches, seabed linear generators, and hybrid platform concepts. Each brings specific advantages for particular geography, water depth, and grid-integration use-cases.
Recent market milestones reinforce the practical pathway to commercialisation. Notably, a U.S. utility-scale PPA covering wave-generated energy from a West Coast test site was executed in late 2025 — a first-of-its-kind contract in the continental U.S. that provides a replicable offtake model for future projects. At the same time, national funding frontiers, such as the U.S. Department of Energy’s multi-year oceans program, are directing meaningful R&D capital toward open-water testing and device maturation.
Ocean Wave Energy Technology Market
Policy, funding and material dynamics — non-technology levers that shape strategy
- Public funding that targets device development and open-water testing is proving catalytic: dedicated multi-year programs have unlocked test-facility build-out and first-of-a-kind PPAs that materially reduce offtaker and lender risk. The presence of dedicated funds improves the expected shaping of market timelines for developers and sponsors.
- Raw-material choices — particularly the growing use of GFRP composites and advanced filament-winding processes — are impacting hull and structural design trade-offs. Procurement strategies for composite fabrication capacity and quality assurance will be differentiators for system cost and durability.
- Test-facility availability and grid access timelines are the binding constraints for 2026 pilots converting to commercial-scale arrays; early access to accredited test sites and long-term offtake commitments will accelerate commercial investment decisions.
Strategic implications — recommended actions for 2026
- For technology developers: Prioritise survivability testing and O&M automation to compress learning curves. Shape pilot contracts that include staged performance milestones and operational-data covenants attractive to lenders.
- For utilities and offtakers: Use early-stage PPAs and offtake options to secure preferential pricing and siting rights while sharing staged performance risk with developers; embed flexibility for technology upgrades.
- For investors and project financiers: Underwrite portfolios of diverse device classes to hedge device-specific risk and accelerate returns via staged equity tranches conditioned on demonstrable OPEX improvements and grid availability.
- For OEMs and supply-chain players: Lock in composite fabrication and PTO supply agreements with scalability clauses that reflect expected volume ramps and evolving design standards.
- For policymakers and regulators: Prioritise test-facility infrastructure, streamlined permitting corridors, and transparent interconnection frameworks to lower transaction costs and attract private capital.
Why this report matters to you
Decisions made in 2026 will determine who captures value as the wave-energy sector moves into the commercial phase. This PW Consulting report equips leadership teams with not only a defensible market forecast and technology assessment, but with executable transaction-level tools — financial models, contractual playbooks, supplier strategies, and regulatory navigators — that bridge demonstrations and scalable projects.
Next steps — access and engagement
The executive summary above distils the actionable judgment clients tell us is most valuable when shaping near-term strategy. Our full report includes the complete forecast model, device-class segmentation, regional demand scenarios, and downloadable financial templates for project-level underwriting. To review the full dataset and obtain bespoke advisory services — including scenario modelling tailored to corporate balance sheets and offtake strategies — visit the PW Consulting Ocean Wave Energy report page or contact our industry team directly.
PW Consulting remains committed to translating marine-innovation potential into investable outcomes. As the industry shifts from pilots to projects, the choices of 2026 will define who leads the wave-energy value chain in the decade ahead.
For detailed analysis of this topic, please visit the official page: Ocean Wave Energy Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com