

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts C9 Petroleum Resin Market to Expand at a 4.85% CAGR During 2026–2032

C9 Petroleum Resin Market: Strategic Playbook for 2026 — A PW Consulting Executive Brief
As PW Consulting’s Chief Industry Analyst, I present a concise strategic briefing drawn from our forthcoming C9 Petroleum Resin Market research. This analysis synthesizes an exhaustive assessment of the hydrocarbon-resin value chain, competitive dynamics, and supply-side risk vectors to illuminate the choices facing executives in 2026. Our base-year snapshot indicates the global C9 petroleum resin market reached approximately USD 1.725 billion in 2025 and, given current trajectories, is projected to approach roughly USD 2.40 billion by 2032 — representing a compounded annual growth rate of about 4.85% across the 2026–2032 forecast horizon. These headline numbers frame a market that is mature but still offers selective pockets of expansion, especially for players who act decisively on feedstock strategy, product differentiation, and downstream partnerships.
C9 Petroleum Resin Market
Why 2026 Is a Strategic Inflection Point
Several concurrent trends converge to make 2026 a decision year for producers, converters, and investors:
C9 Petroleum Resin Market
- Feedstock reconfiguration in steam-cracking networks is changing the availability profile of the aromatic C9 fraction, the essential precursor to C9 resins. Decisions now about feedstock sourcing and cracker contracting will determine margin stability for years.
- End-market evolution — notably in adhesives, coatings, and inks — is placing a premium on tailored resin grades (performance, compatibility, and sustainability attributes). The winners will be those who secure technical differentiation rather than compete solely on price.
- Regulatory and reporting clarity on high-molecular-weight hydrocarbon resins reduces a layer of compliance uncertainty in major markets, but downstream customers increasingly expect traceability and low-impact footprints.
Market Dynamics & Supply-Chain Sensitivities
At a high level, the C9 resin market is shaped by a tight interplay between ethylene-cracker feedstock choices and resin production economics. C9 petroleum resin is produced from the aromatic C9 fraction — a byproduct of steam cracking of naphtha and other hydrocarbons. Operators that lean toward ethane cracking reduce their C9 byproduct output versus naphtha crackers, creating localized supply constraints when cracker utilization or feedstock mixes shift.
C9 Petroleum Resin Market
Key implications for 2026 strategy:
- Feedstock exposure matters. Companies with integrated access to naphtha-sourced C9 fractions or long-term offtake agreements will see superior margin resilience compared with spot-dependent converters.
- Price volatility will persist. Upstream feedstock swings transmit quickly to resin margins; scenario planning and hedging instruments should be routine elements of commercial planning.
- Regulatory posture is relatively benign for C9 resins at present: many hydrocarbon resins are assessed as low hazard under chemical assessment frameworks due to their high molecular weight and low volatility. Nevertheless, sustainability and supply transparency are now commercial differentiators even where regulatory risk is limited.
Competitive Landscape — Strategic Profiles and Implications
The competitive field mixes integrated majors, regional specialists, and nimble Chinese producers. Rather than enumerate market shares, our analysis focuses on strategic positioning and capability sets that will determine winners and losers in 2026–2032.
- Kolon Industries (South Korea) — Domestic scale plus product innovation. Kolon’s dual C5/C9 capability and its history of commercializing crosslinkable hydrocarbon resins make it a compelling partner for adhesive and advanced-coating formulators. Strategic implication: Kolon is well placed to pursue premiumization strategies and co-development agreements with formulators seeking performance differentiation.
- Neville Chemical Company (USA) — Secure domestic supply and legacy know-how. With a long track record in C9 aromatic resins, Neville is a preferred supplier where supply security and consistent quality are paramount. Strategic implication: Neville’s positioning plays well to customers seeking onshore alternatives amid global supply uncertainty.
- Eastman Chemical Company (USA) — Portfolio breadth and technical service. Eastman’s integrated hydrocarbon-resin offering, combined with strong downstream technical support, supports value-based selling. Strategic implication: Eastman can extract premium pricing through application engineering and bundled service models.
- Cray Valley / TotalEnergies (France/USA) — Global reach and investment capacity. As part of a larger energy-chemical ecosystem, Cray Valley can optimize feedstock logistics and scale niche grades for inks and adhesives. Strategic implication: look for targeted capacity investments and selective backward integration moves.
- Exxon Mobil (USA) — Feedstock integration advantage. Exxon’s upstream-to-chemical integration gives it low-cost access to C9 feedstocks in certain regions. Strategic implication: aggressive commercial offers in key segments could pressure standalone resin margins unless competitors secure differentiated propositions.
- Chinese manufacturers (multiple specialized players) — Cost-competitive, agile supply. Regional producers deliver flexible grade portfolios and fast-to-market responsiveness. Strategic implication: incumbents in developed markets should expect continued competitive pressure on commodity grades while pursuing higher-margin specialty applications.
Taken together, the competitive field fosters a market dynamic where scale and feedstock integration matter for cost leadership, and technical service and tailored grades matter for premium positioning. The market is neither a pure commodity race nor entirely premiumized — it rewards hybrid strategies.
What Our Full Report Delivers — Practical, Executable Intelligence
PW Consulting’s C9 Petroleum Resin Market report is built as an operator’s toolkit for 2026 decision-making. Key practical modules include:
- Demand model and forecast (2026–2032) with scenario outputs calibrated to feedstock shifts, regional cracker utilization scenarios, and end-use adoption curves.
- Price and margin sensitivity analysis that quantifies the impact of naphtha and C9 fraction price swings on producer economics under multiple contracting structures.
- Supply-risk heatmap and mitigation playbook mapping cracker outages, logistics chokepoints, and alternative feedstock options.
- Go-to-market playbooks for producers and converters: segmentation strategies, premium-grade development roadmap, and value-selling templates tailored to adhesives, coatings, inks, and rubber compounding customers.
- M&A and CapEx decision frameworks with target screening criteria, valuation heuristics for bolt-on resin assets, and integration checklists to preserve margins post-acquisition.
- Sustainability and compliance pathway: lifecycle hotspots, low-impact sourcing levers, and customer-facing disclosure templates that reduce procurement friction in large end-use accounts.
- Competitive dossiers on the leading producers, highlighting strategic intent, capacity levers, and likely moves through 2028.
We intentionally designed the deliverables as tools that senior management, supply-chain leaders, and corporate development teams can adopt immediately — not just as descriptive market commentary.
High-Value Strategic Recommendations for 2026
For executives preparing 2026 plans, our advice is sharply actionable and prioritized by impact and lead time:
- Secure feedstock optionality now. Negotiate flexible offtakes or co-invest in cracker-linked C9 streams. Even limited upstream integration or multi-year naphtha-linked contracts materially reduce margin volatility.
- Differentiate through formulation partnerships. Sponsor co-development projects with key adhesive and coatings customers to lock in demand for specialty grades and capture price premiums.
- Optimize commercial contracts. Move away from pure spot indexation where possible. Introduce hybrid pricing clauses that share upstream cost movements, protecting margins while remaining competitive.
- Target bolt-on capacity where it accelerates access to strategic customers. Small, focused acquisitions that add technical capability or customer intimacy often create outsized value compared with greenfield builds in this sector.
- Invest in traceability and disclosure. Even though regulatory risk is low today, sustainability transparency unlocks procurement programs with multinational formulators and reduces commercial friction.
- Institutionalize scenario-based planning. Embed C9 fraction availability cases into annual planning cycles to ensure procurement, operations, and commercial teams are aligned for stress conditions.
How Executives Should Use the Report
The report is designed for four primary use cases:
- Corporate Strategy: baseline market sizing, growth corridors, and valuation assumptions for capital allocation decisions.
- Commercial Leadership: pricing playbooks, contract templates, and customer segmentation to drive short-term margin recovery and long-term premium growth.
- Supply-Chain & Procurement: feedstock risk matrices, supplier-scorecard frameworks, and contingency planning to reduce exposure to cracker feedstock shifts.
- M&A & Investor Teams: opportunistic acquisition maps, integration checklists, and scenario-based valuations aligned with 2026 market realities.
Accessing the Full Intelligence
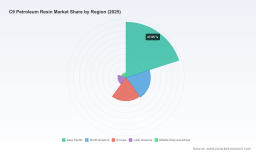
This briefing highlights our depth and the kinds of decision-ready outputs we deliver. We intentionally withheld granular regional splits, application-level share tables, and company-level volume data from this note to preserve the report’s role as a strategic asset. The full report contains those core segmented data tables, downloadable models, and interactive scenario dashboards that executives and their teams can apply directly to 2026 planning cycles.
For firms preparing capital plans, contract negotiations, or M&A activity in 2026, the difference between a reactive and a proactive approach will hinge on feedstock control and differentiated product positioning. PW Consulting’s C9 Petroleum Resin report provides the roadmap to convert market insight into executable advantage. To obtain the full dataset, scenario models, and company dossiers, please visit our report page or contact our advisory desk to arrange a briefing.
— PW Consulting, Strategic Insights Team
For detailed analysis of this topic, please visit the official page: C9 Petroleum Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com