

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Small-Volume Personal Care Packaging Market Set to Grow at a 4.4% CAGR, New Insights Reveal

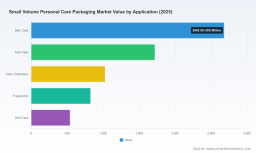
Small Volume Personal Care Packaging Market: Strategic Outlook for 2026
PW Consulting’s latest market study on Small Volume Personal Care Packaging presents a focused, actionable intelligence package designed to influence executive decisions through 2026 and beyond. Built on a six‑year historical base and a seven‑year forecast horizon, this release synthesizes revenue modeling, supplier mapping, regulatory scenario analysis, and go‑to‑market playbooks—enabling packaging manufacturers, brand owners, and procurement teams to prioritize investments, manage risk, and capture value in a market characterized by steady expansion and accelerating sustainability requirements.
Small Volume Personal Care Packaging Market
Executive snapshot
The small volume personal care packaging market recorded steady recovery and growth through the early 2020s and reached a material inflection point by the base year 2025. Our bottom‑up modeling shows the market size at the 2025 base, with a compound annual growth rate (CAGR) of approximately 4.4% across the 2026–2032 forecast period. By 2032 the market is projected to be materially larger than the 2025 baseline, reflecting a combination of premiumization, increased trial and travel formats, and regulatory-driven material transitions.
Small Volume Personal Care Packaging Market
Why 2026 is a strategic inflection point
- Sustainability as a commercial requirement: Regulatory trajectories in multiple U.S. states and other jurisdictions are tightening post‑consumer recycled (PCR) content requirements and expanding producer responsibilities. These rules are shifting cost‑to‑serve and supplier selection calculus for small, rigid and flexible formats alike.
- Material cost volatility: Early‑2026 upward pressure on polyethylene (PE) and polypropylene (PP) feedstocks has increased unit costs for plastic‑dominant small formats, compressing margins for low‑price, high‑volume SKUs while advantaging premium, recyclable or mono‑material designs that command pricing power.
- Format innovation and premium miniaturization: Brands continue to use small‑volume formats to support experiential marketing (sample kits, travel, subscriptions) and premiumization (mini serums, concentrated treatments). Advances in micro‑dispensing, airless systems, and low‑MOQ tooling make new SKU economics viable.
- Fragmented supply landscape: Market concentration is low; the top three suppliers account for less than one fifth of market revenues and the top five for roughly one quarter—creating room for specialist entrants, white‑label manufacturers, and localized players to grow rapidly through service differentiation and niche capabilities.
What the PW Consulting report delivers (practical, board‑ready outputs)
- Strategic playbooks: Scenario‑based recommendations for material strategies (PCR adoption paths, mono‑material transitions), SKU rationalization, and format roadmaps for travel, sample, subscription, and premium segments.
- Commercial modeling tools: Interactive cost‑to‑serve matrices and margin sensitivity models that allow procurement and finance teams to test price, resin, and tooling scenarios against regulatory compliance timelines.
- Supplier intelligence and scorecards: Vendor benchmarking across capability clusters—micro‑dispensing, low‑MOQ runs, sustainable material offerings, and global vs. regional manufacturing footprints—highlighting where to partner, insource, or consolidate.
- Regulatory & compliance playbook: A prioritized map of regional regulatory risks and timelines with compliance pathways and capex/Opex implications for converters and brand owners.
- Market sizing & forecast: Historic performance (2020–2025) and detailed forecasts through 2032 with scenario sensitivity to raw material prices and regulatory adoption rates. (Note: the public summary intentionally omits granular sub‑segment revenue splits; these are included in the full report.)
- Innovation and IP scan: Rapid assessment of emergent dispensing technologies, mono‑material closures, and refill systems that reduce life‑cycle costs and support claims of recyclability and lower carbon intensity.
Competitive landscape: where incumbents and challengers are placing their bets
Our vendor analysis identifies a diverse mix of global leaders, regional specialists and niche innovators. Large multinational converters and system providers have pursued two parallel strategies: (1) broaden product breadth to supply full packaging ecosystems for beauty and personal care; and (2) introduce modular small‑volume platforms (airless micro‑systems, pocket sprays, mini pumps) to capture higher margin, higher frequency SKUs. At the same time, niche players are exploiting low‑MOQ manufacturing, unit‑dose expertise, and close co‑development with indie brands.
Small Volume Personal Care Packaging Market
- Albéa Group (France): Strength in beauty‑grade tubes and bottles with low‑MOQ offerings and r‑material options positions Albéa to win serums, travel sets, and gift‑size SKUs where aesthetic finish and sustainability are decisive.
- Aptar Beauty (U.S.): Deep competency in micro‑dispensing and airless technologies, reinforced by recent product introductions targeted at precision dosing and hygiene, makes Aptar a first call for premium dermocosmetic and high‑viscosity applications.
- Silgan Dispensing (U.S.): Strengths in travel dispensers, foamers and fragrance minis match the sampling and trial strategies of fast‑moving consumer brands.
- Berry Global (U.S.): Investment in smaller stick and refill sizes plus recycled content options reflects a play for mass‑market personal care with sustainability parity.
- HCP Packaging (U.K.): Specialist in color cosmetics compacts and pocket designs—a logical partner for brands prioritizing premium pocketability and makeup refills.
- Amcor (Switzerland): Flexible packaging expertise and paper‑based sachet solutions are central to cost‑efficient sampling and single‑use product strategies with recyclability claims.
- Gerresheimer (Germany): Glass and lightweight decorative solutions appeal to premium skincare and fragrance segments that prioritize perceived quality and recyclability.
- Unit Pack & JP Packaging (U.S.): Unit‑dose and sachet specialists supporting trial, clinical samples and precise topical dosing—key partners for dermatological and technical personal care lines.
Recent vendor activity tracked in our research—product launches expanding mini formats, new automated micro‑fillers, and regional sustainability collections—underscores a fast‑moving competitive dynamic. For decision‑makers, the practical question is not only who can supply, but which supplier reduces regulatory and sourcing risk while improving speed to consumer.
Strategic implications and recommended actions for 2026
- Adopt a PCR transition roadmap now: With state and regional targets escalating over the next decade, brands should model staggered adoption of PCR and identify formats where early conversion yields the best trade‑off between price and consumer credibility.
- Prioritize mono‑material and refillable architectures: Design choices that simplify end‑of‑life processing reduce compliance cost and futureproof claims; these choices also create premium marketing differentiation when backed by verified chain‑of‑custody for recycled content.
- Hedge feedstock exposure: Build multi‑supplier resin agreements and qualify alternative materials (paper laminates, post‑consumer feedstocks) to soften margin shocks from PE/PP price swings.
- Leverage small‑run economics: Use low‑MOQ tooling and regional micro‑factories to support DTC, subscription, and limited‑edition launches while keeping working capital requirements manageable.
- Run prioritized pilot programs: Test high‑value small formats (micro‑dispensing, premium trial kits) in controlled markets to validate unit economics before full rollout.
- Explore consolidation and partnerships: Given the fragmented supplier base, acquisitive strategies and strategic JV models can accelerate capability build versus organic investment—especially for firms lacking micro‑filling or PCR capacity.
Use cases and commercial upside
Small volume packaging is no longer only a sampling tool; it underpins multiple revenue levers. Successful use cases we model in the report include travel and trial formats that increase conversion rates, subscription and refill ecosystems that improve lifetime value, and premium minis that command price premiums in prestige skincare. Each use case is accompanied by a profitability model showing payback periods for tooling and packaging redesign under realistic adoption rates.
Methodology & data integrity
The report’s conclusions are grounded in a hybrid methodology: bottom‑up revenue aggregation, supplier interviews, brand buyer surveys, patent and product launch tracking, and price benchmarking conducted across the 2020–2025 historical window and extended through 2032 using scenario drivers for raw material prices and regulatory adoption. Market concentration metrics and provider scorecards are triangulated with primary supplier disclosures and public filings to ensure defensible strategic guidance.
What is intentionally withheld (and why)
Consistent with the report’s role as a commercial advisory product, this public summary intentionally presents the high‑value strategic frameworks, macro market sizing, and competitive direction without disclosing granular sub‑segment revenue splits and confidential supplier contracts. These detailed sub‑segment matrices, regional/application-by‑format tables, and downloadable modeling workbooks are available in the full report package and are essential for transaction diligence and SKU‑level portfolio decisions.
How to use the full report
- Download the report to access interactive dashboards and the scenario model and to see the full sub‑segment breakdowns that inform SKU rationalization and pricing.
- Use the supplier scorecards to accelerate vendor qualification and to prioritize pilots with partners who can meet PCR and low‑MOQ needs.
- Engage our consulting team for a 90‑day implementation sprint: redesign a pilot SKU, secure pilot tooling, and validate final consumer and cost outcomes ahead of a scaled launch.
PW Consulting’s Small Volume Personal Care Packaging Market study is designed to be an operational catalyst: not just to inform, but to change how packaging teams, procurement, and brand strategy align around formats, materials, and commercial models for 2026. For access to the full data tables, segment granularity, interactive models, and supplier decks, please visit our report page or contact your PW Consulting account lead.
For detailed analysis of this topic, please visit the official page: Small Volume Personal Care Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com