

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Chemical & Materials
PW Consulting: Commercial Small Batteries Market Poised for 6.79% CAGR Through 2032
By pmarketresearch, 2026-07-06
Commercial Small Batteries Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
As organizations plan capital allocation and product-roadmap decisions for 2026, the commercial small batteries market stands out as a resilient, mid-single-digit growth sector with clear structural drivers and emerging points of disruption. PW Consulting’s forthcoming market research report — based on a 2020–2025 historical analysis and a 2026–2032 forecast horizon — synthesizes financial trajectory, competitive positioning, regulatory risk, and strategic playbooks that senior leaders will need to act confidently in the coming 12–18 months.
Commercial Small Batteries Market
Market Trajectory: The Big Picture
The commercial small batteries market has expanded steadily over the past five years, with measured acceleration into 2024–2025. From the base year (2025) used in our modelling, the market is projected to continue growing through 2032 at a compound annual growth rate (CAGR) of 6.79%. That rate reflects a combination of steady demand from healthcare devices, industrial IoT, retail systems and security applications, alongside replacement cycles and new design wins for commercial electronics.
Commercial Small Batteries Market
To contextualize the trajectory: the market has moved meaningfully higher since 2020 and is forecast to reach a materially larger size by the end of our forecast period in 2032. That expansion, combined with concentrated pockets of supplier strength, creates both opportunities and tactical risks for procurement, product, and M&A teams.
Commercial Small Batteries Market
Why This Matters for 2026 Decision Cycles
-
Capital allocation and sourcing strategies must incorporate both steady demand and episodic shocks. The forecasted mid‑single‑digit CAGR validates continued investment in small battery-enabled product platforms, but the detailed scenarios in our report show that margin sensitivity to input-cost swings is non-linear—requiring hedged supplier strategies and staged capital commitments.
-
Product teams need to accelerate safety-by-design and regulatory alignment. New and updated standards addressing ingestion risks and chemical restrictions are moving from guidance into enforceable practice; early conformity reduces time-to-market friction for new commercial devices.
-
M&A and partnership activity should be informed by concentration dynamics. A market with meaningful share concentration at the top creates attractive carve‑out opportunities for mid-market buyers and offers dominant suppliers leverage in channel negotiations; our competitive scorecards identify where value pools are most accessible.
Report Highlights: What Practitioners Will Find Inside
-
Actionable demand scenarios: deterministic and probabilistic forward scenarios through 2032 calibrated to macro‑adoption curves, device bill-of-material trends, and replacement cycles. Each scenario estimates topline implications while preserving the granularity clients need to stress-test portfolios (note: proprietary subsegment tables are available in the full report).
-
Cost-sensitivity and input-risk modelling: interactive dashboards that quantify margin exposure to raw-material price swings (including lithium carbonate volatility) and freight/logistics dynamics, with prescriptive sourcing playbooks for tiered procurement.
-
Regulatory and safety compliance playbooks: checklists and design‑control templates aligned to recent standards and regulations — including ingestion-safety testing norms and extended producer responsibility frameworks — to reduce compliance-related delays and recalls.
-
Commercial go-to-market frameworks: tailored channel and pricing strategies for commercial OEMs, medical device manufacturers, and system integrators to improve adoption rates and margin capture in regulated environments.
-
Competitive intelligence modules: vendor scorecards, supplier risk matrices, and M&A screening tools that combine primary interviews, patent activity mapping, and public financials to identify partnership and acquisition targets.
Competitive Landscape — Where Power and Exposure Converge
The small batteries market comprises legacy household brands, specialized component manufacturers, and suppliers focused on backup and industrial power. Market concentration is meaningful at the top: our analysis shows that the three largest vendors control a substantial share of the market, with the top five accounting for nearly 59% — a structural reality that informs pricing dynamics, channel power, and innovation pipelines.
Key industry participants analyzed in the report include established consumer and industrial brands that offer complementary strengths:
-
Energizer Holdings — breadth across alkaline, lithium, and coin cells with deep retail reach; strengths in branded volume and broad channel partnerships.
-
Duracell Inc. — consumer-recognized safety innovations and rechargeable options; recent product-level safety work underscores its emphasis on packaging and child-safety design features.
-
Panasonic Corporation and other global component manufacturers — diversified chemistries and industrial relationships that support integrated OEM supply to commercial electronics and medical devices.
-
VARTA, Maxell, GP Batteries, Murata, Renata — niche and specialty players with leadership in micro and button cells for precision applications, often competing on quality, regulatory compliance, and application-specific support.
-
EnerSys, GS Yuasa, Power-Sonic — suppliers focused on sealed lead-acid (SLA/VRLA) and small-format backup solutions for UPS, standby, and industrial use-cases.
Our competitive analysis goes beyond product catalogues to assess R&D pipelines, safety-certification commitments, channel strategies, and manufacturing footprint resilience. For senior leaders planning supply agreements or considering vertical integration, the report provides relative scoring across these vectors and recommended negotiation playbooks tailored to supplier archetypes.
Regulatory, Safety and Raw Material Dynamics — Near-Term Risks
Three external forces will disproportionately influence 2026 outcomes:
-
Regulatory tightening: The EU’s battery framework and evolving international safety standards are shifting compliance from optional to table stakes. Specific labeling rules and extended producer responsibility mechanisms are already affecting product design and total landed costs for commercial devices.
-
Safety standards and design obligations: New and updated standards focused on button/coin cell ingestion and physiological hazards require changes in packaging, device enclosures, and public-facing warnings — changes that product teams must incorporate early to avoid redesign cycles at scale.
-
Raw material volatility: Price swings in battery-grade feedstocks such as lithium carbonate materially impact unit economics for lithium-based small batteries. Our scenario modelling quantifies margin stress points and provides hedging and supplier-mix recommendations that can be implemented within procurement cycles for 2026.
Recent Industry Signals
-
Product and portfolio moves: New market entrants and incumbents are expanding into finer-format battery types to capture stable commercial demand flows — moves that can reshape supplier competition in adjacent categories.
-
Trade-show and innovation clustering: Industry trade events in 2025 and early 2026 showcased incremental but important advances in cell chemistry, packaging for safety, and integration methods for IoT endpoints — suggesting near-term product refresh cycles for commercial OEMs.
-
Safety-focused launches: Recent product innovations targeting child-safety and ingestion-risk mitigation illustrate how manufacturers are translating regulation and public concern into product differentiation — reinforcing the point that compliance can be a competitive asset.
Strategic Playbook for 2026
-
Embed regulatory compliance into product roadmaps: Treat new and updated standards as design constraints rather than after-market fixes; prioritize packaging and ingestion-mitigation technologies that reduce certification timelines.
-
Use procurement as a strategic lever: Implement multi-supplier sourcing with capacity options, index-linked pricing clauses for volatile feedstocks, and joint-development agreements to secure preferred pricing for key chemistries.
-
Prioritize modular design for serviceability: For devices deployed in high-service environments (medical, security, retail), optimize for battery-swap procedures and certified replacements to reduce lifecycle cost and liability.
-
Consider targeted partnerships and tuck-ins: Where concentration enables, explore alliances with specialty cell manufacturers to access differentiated chemistries or safety-enabled packaging technologies.
About the Report and Next Steps
PW Consulting’s full Commercial Small Batteries Market report combines quantitative forecasts, supplier and product maps, regulatory trackers, and executable templates designed for commercialization, procurement, and M&A teams. The preview you’ve read outlines the strategic implications and topline market trajectory — the full release contains the empirical datasets, vendor scorecards, and scenario-model templates that informed these insights.
For decision-makers who will set budgets, negotiate supplier agreements, or approve product launches in 2026, the report is structured to shorten time-to-decision: it translates market trajectories and regulatory signals into prioritized actions, mapped to implementation timelines and expected ROI.
How to Access Full Intelligence
This press preview follows a “trailer” principle: it demonstrates the analytic depth of our work and highlights the operational value for 2026 planning while intentionally omitting proprietary subsegment tables and granular regional/application splits. To obtain the complete dataset, vendor-level dashboards, and downloadable scenario workbooks, please refer to the PW Consulting release page for the Commercial Small Batteries Market report.
Our team is available to conduct executive briefings, tailored deep-dives, and supplier negotiation workshops based on the report’s findings—supporting fast, evidence-based decisions for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Commercial Small Batteries Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cochloroether Rubber Eco Market to Grow at 4.51% CAGR as Asia Pacific Leads with USD 297.96 Million Share
By pmarketresearch, 2026-07-06
Cochloroether Rubber (ECO) Market — Strategic Outlook for 2026: Key Implications from PW Consulting’s New Market Report
PW Consulting’s latest Cochloroether Rubber (ECO) Market study is issued with a clear remit: help executives convert market intelligence into defensible 2026 strategies. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the report synthesizes demand drivers, supply dynamics, cost structures, and competitive positioning that will determine which firms capture value as the market evolves. At the macro level, the industry is expanding steadily — the market grew from approximately USD 515 million in 2020 to roughly USD 642 million in 2025 and is projected to approach USD 875 million by 2032, reflecting a 4.51% CAGR across the forecast period. That trajectory underpins planning choices across procurement, product, and M&A agendas for 2026.
Cochloroether Rubber Eco Market
Why 2026 is a Strategic Inflection Point
-
Demand stabilization meets supply transformation. After a recovery phase through 2023–2025, incremental demand for ECO in automotive seals, industrial gasketing, and specialty rolls is now intersecting with meaningful upstream capacity changes. New epichlorohydrin capacity additions in 2024 and 2025 and an industry-wide shift toward glycerol- and bio-based feedstocks are altering marginal cost curves and sourcing risk profiles.
Cochloroether Rubber Eco Market -
Consolidation and supplier concentration are shaping commercial dynamics. Industry concentration metrics indicate a market with substantial share controlled by a narrow set of global suppliers — a structural condition that affects pricing power, contract terms, and speed of innovation adoption.
Cochloroether Rubber Eco Market -
Regulatory and sustainability vectors are accelerating product re-specification. The move by compounders to ETU-free and lead-free curing systems and the advance of bio-based epichlorohydrin production routes mean OEM specifications will increasingly include lifecycle and hazard parameters as pass/fail attributes rather than optional differentiators.
What the Report Delivers — Practical, Executable Intelligence
PW Consulting designed the report for use by commercial leaders, procurement teams, R&D heads, and corporate development groups. Deliverables are operational and include:
-
Market sizing and demand scenarios calibrated to 2026 planning cycles, with bottom-up and top-down crosschecks aligned to real-world shipments and end-market activity.
-
Cost-model templates that isolate feedstock, energy, conversion, and logistics components to quantify pass-through exposure to epichlorohydrin price moves and regional freight differentials.
-
Supplier scorecards and risk heatmaps covering manufacturing footprint, product breadth (homopolymer / copolymer / terpolymer families), quality certifications, and commercial flexibility.
-
Regulatory and compliance matrices that map chemical hazards, curing-system constraints, and emerging test protocols relevant to automotive and industrial spec writers.
-
Go-to-market playbooks for incumbents and entrants — from premium-grade product segmentation to low-cost regional supply strategies — with negotiation scripts for long-term off-take and tolling arrangements.
-
M&A and investment screening tools: capex sizing for greenfield polymer compounding, payback sensitivity to feedstock price volatility, and acquisition target prioritization criteria.
Importantly, the report pairs qualitative supplier insight with an interactive model so teams can stress-test strategies under demand shocks, raw-material squeezes, or accelerated electrification scenarios.
Supply-Side Dynamics: Epichlorohydrin, Capacity Additions, and the Bio-Shift
Epichlorohydrin remains the primary upstream feedstock for ECO production, and its market structure is a meaningful determinant of downstream cost and availability. Global epichlorohydrin production capacity reached multi-million-ton scale in 2025 with production rates materially below nameplate capacity — a delta that has compelled some suppliers to prioritize high-margin contractual customers during tight periods. Notably, 2024–2025 saw several new capacity additions with a pronounced emphasis on glycerol-based, lower-carbon production routes. These additions are reshaping the marginal cost curve and creating new arbitrage opportunities for buyers who can source bio-based feedstock or negotiate linked pricing mechanisms.
For procurement teams, the practical implications are twofold: first, hedging and long-term off-takes must be structured around feedstock pathway economics (conventional vs. bio-based), and second, supply continuity plans should incorporate alternative chemistry or compounder partners capable of rapid qualification.
Competitive Landscape: What the Leading Players Signal
The market exhibits a high degree of supplier concentration, with the top three firms accounting for a majority share and the top five controlling a substantial portion of global volume. This concentration (CR3 ~62.3%; CR5 ~78.45%) results in asymmetric bargaining power that manifests through price announcements, allocation policies, and technical partnership access.
-
Integrated Japanese producers: Established Japanese firms operate integrated value chains from epichlorohydrin monomer through finished ECO grades, enabling quality control and margin protection. Their product breadth — homopolymers, copolymers, and terpolymers — and long production histories make them preferred partners for high-spec automotive OEMs.
-
US capacity emphasis: Suppliers with US manufacturing positions highlight proximity advantage for North American OEM programs and regulatory alignment for critical applications such as fuel-system components.
-
Specialist compounders and formulators: Smaller, regional suppliers focus on application-specific compounds (e.g., high-durometer grades to meet ASTM classifications) and regulatory-compliant curing systems (ETU-free, lead-free) — features increasingly demanded by automotive and industrial purchasers.
Recent commercial signals—such as supplier-led price increases in mid-2024—underscore a landscape where capacity utilization, feedstock price pass-through, and contractual rigidity can rapidly shift margin outcomes for OEMs and tier suppliers. For buyers, the lesson is clear: price movements are not purely transient; they reflect embedded structural positions that require contractual and technical mitigation.
Strategic Priorities for 2026
-
Integrate feedstock pathway risk into product roadmaps: Distinguish formulations that are feedstock-agnostic from those that are not. Prioritize R&D that enables substitution to bio-based epichlorohydrin where lifecycle or regulatory pressures make this a procurement preference.
-
Secure layered supply contracts: Combine medium-term fixed-volume agreements with spot flexibility and call options to balance cost control and agility. Include explicit pass-through and indexing clauses tied to epichlorohydrin and energy baskets.
-
Invest in qualification velocity: Reduce lead time to approve alternate compounders by establishing standardized test protocols and accelerated aging pilots that align with OEM validation cycles.
-
Prioritize regulatory-compliant chemistries: Move away from hazardous curing systems where feasible; ETU- and lead-free offerings are becoming table stakes in many automotive programs.
-
Consider selective vertical integration or tolling partnerships: For manufacturers with scale, securing tolling capacity or partial upstream integration can offer meaningful protection against allocation risks and sudden price moves.
How PW Consulting’s Report Supports 2026 Decisions
Executives need analysis they can operationalize in months, not years. PW Consulting’s report supplies that bridge by combining market forecasting, supplier benchmarking, and executable playbooks. Key outputs designed for immediate use in 2026 planning cycles include:
-
Negotiation-ready supplier scorecards and term sheets tailored to different volume tiers and application criticality.
-
Scenario-based P&L impact calculators that show profit sensitivity to feedstock moves and allocation events.
-
Manufacturing readiness and qualification checklists that compress supplier onboarding timelines.
-
M&A “heat map” identifying segments and geographies where bolt-on acquisitions or strategic minority investments deliver quick access to new grades or regulatory-compliant compounding technologies.
On Transparency and Where to Find the Full Intelligence
In keeping with the “trailer” approach to strategic disclosure, this release emphasizes the insights and recommendations most immediately useful to senior decision-makers while deliberately withholding certain granular segmentation tables and specific regional/application breakdowns. Those detailed segmentations, including supplier-level volume histories, application-by-application forecasts, and confidential price and margin profiles, are bundled in the full PW Consulting report and interactive model.
For commercial teams planning 2026 sourcing cycles, product leaders refining grade roadmaps, or corporate development teams seeking targeted acquisition opportunities, the full report and model provide the necessary granularity and forensic supplier detail to execute with confidence.
Closing — A Practical Roadmap into 2026
The Cochloroether Rubber market is maturing into a structurally different industry than it was five years ago. Steady end-market demand, upstream capacity additions (including bio-based routes), and concentrated supplier power combine to make 2026 a planning year where choices about supply contracts, technical partnerships, and regulatory positioning will determine competitive advantage. PW Consulting’s report converts those market realities into executable strategies, allowing organizations to protect margin, accelerate qualification cycles, and selectively invest where the economics are most compelling.
To access the full report, the interactive forecast model, and supplier annexes required to implement these recommendations, please visit PW Consulting’s Cochloroether Rubber Market research page or contact our advisory team for a guided briefing.
For detailed analysis of this topic, please visit the official page: Cochloroether Rubber Eco Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cosmetic-Grade Sorbitan Esters Market Set to Grow at a 5.45% CAGR Through 2032
By pmarketresearch, 2026-07-06
Cosmetic Grade Sorbitan Esters Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
Executive preview
As formulators, manufacturers, and strategic buyers prepare for the pivotal decisions that will define 2026, PW Consulting’s latest Cosmetic Grade Sorbitan Esters Market study delivers a compact, operationally focused intelligence package. The market that supplied USD 505 million in revenues in 2025 is projected to expand at a steady compound annual growth rate (CAGR) of 5.45% through our forecast period, reaching roughly USD 732 million by 2032. This trajectory reflects a resilient demand base across personal care categories and evolving dynamics in raw material sourcing, regulatory clarity, and performance-driven innovation.
Cosmetic Grade Sorbitan Esters Market
Why this matters to 2026 decision-makers
-
Procurement optimization: Input-cost dynamics and supplier concentration make 2026 a year for renegotiation and strategic sourcing. With mid-tier concentration across the supplier landscape, buyers who lock in adaptive supply contracts and multi-sourcing options can materially reduce volatility exposure.
Cosmetic Grade Sorbitan Esters Market -
Formulation roadmaps: Sorbitan esters remain core w/o emulsifiers and co-emulsifiers. Brands seeking to deepen wellness and clean-beauty credentials must balance natural-sourced positioning with performance and regulatory confidence.
Cosmetic Grade Sorbitan Esters Market -
M&A and partnership focus: The market’s moderate concentration (CR3 ~42.5%, CR5 ~58.2%) highlights opportunities for acquisitive mid-sized players to build scale, while leading suppliers pursue value moves into specialty grades and regulatory-compliant pharmaceutical options.
-
Regulatory & reputational risk management: Recent regulatory commentary has reinforced safety perceptions, but heightened scrutiny on ingredient disclosures means proactive compliance and transparent supply chain claims are strategic imperatives.
What the PW Consulting report delivers (practical, actionable content)
-
Executive decision templates — scorecards and negotiation playbooks tailored for procurement, R&D, and commercial teams. These templates translate market indicators into levers you can use in supplier conversations, contract renewals, and cost model adjustments.
-
Scenario-driven demand planning — three quantitative scenarios (base, accelerated, constrained) calibrated to feedstock price volatility, product innovation cadence, and regulatory developments to support CAPEX and inventory decisions for 2026.
-
Manufacturing & CAPEX checklist — a practical guide to assess in-house vs. outsourced production of sorbitan esters, including minimum viable plant footprints, key process control parameters, and quality gating for cosmetic-grade and pharmaceutical-grade outputs.
-
Formulation migration playbooks — competitive analyses on how leading cosmetic brands substitute or reformulate with sorbitan esters to achieve desired sensorial and stability outcomes without compromising ‘clean’ or ‘natural’ claims.
-
Regulatory impact matrix — a concise mapping of likely regulatory scenarios and the operational responses required (e.g., additional testing, documentation, labelling changes), allowing legal and regulatory teams to prioritize exposures for 2026.
-
Value chain heatmap — highlights where margin compression may occur and where premiumization opportunities exist (specialty grades, pharma-cleared materials, bio-based certifications), enabling commercial teams to price and position products accordingly.
Market dynamics shaping 2026 strategy
The market’s steady expansion over the last half-decade — from the high hundreds of millions in annual revenue to a mid-five-hundred-million-dollar base in 2025 — underscores enduring demand from skin care, hair care, and decorative cosmetics. Growth is being driven by three interlocking vectors: performance-driven formulation needs, the mainstreaming of wellness-oriented product positioning, and distributors’ efforts to provide vertically integrated solutions.
Raw material dynamics are particularly consequential. Sorbitol — the upstream feedstock for sorbitan esters — displayed regionally divergent pricing and short-term volatility in late 2025 and early 2026. North American indices showed a pronounced softening in late 2025, reducing immediate feedstock pressure for some producers, while other sourcing regions experienced different pricing trends. For strategists, the takeaway is clear: differentiate short-term tactical buys from strategic long-term supply agreements, and model multiple sorbitol-price paths in annual planning.
On the regulatory front, recent authoritative reviews have preserved an overall favorable safety profile for key sorbitan esters. European scientific reassessments reiterated established safety conclusions, and U.S. surveillance on fluorinated chemistries did not implicate sorbitan esters. That regulatory backdrop supports continued usage in personal care, but brands should still invest in traceability and documentation to meet increasingly transparent market expectations.
Competitive landscape — who matters and why
The market features a mix of global integrators and regional specialists. Our report profiles the strategic positioning and product portfolios of the major suppliers, offering comparative matrices that help buyers and partners evaluate fit-for-purpose suppliers for different commercial strategies.
-
Croda International Plc (United Kingdom): A leader with a broad Span/Arlacel portfolio targeted at personal care. Croda’s strength lies in application support and stable supply to multinational brands — a preferred partner for companies that prioritize formulation development and global distribution networks.
-
Oleon NV (Belgium): Known for its RADIASURF family, Oleon emphasizes specialty grades that cross-use into pharma and sun care. Their proposition is attractive for manufacturers seeking differentiated emulsifiers with regulatory flexibility across adjacent markets.
-
BASF SE (Germany): A large-scale supplier offering Dehymuls and related grades, including pharmaceutical-compliant variants. BASF’s advantage is scale plus integrated R&D resources for complex emulsion systems, making them suited for high-volume industrial and premium segments.
-
Kao Corporation & Nikko Chemicals (Japan): Both players compete on high-purity grades and strong regional support in Asia, with an emphasis on tailored cosmetic applications and close collaboration with formulators in the APAC market.
-
Regional suppliers (India / China): Several suppliers from India and China provide competitive pricing and pragmatic supply solutions for local and regional brands. They are increasingly participating in supplier consolidation discussions and are building quality certifications to expand into premium channels.
Strategically, the market’s mid-level concentration suggests serial opportunities for alliances, co-development programs, and bolt-on acquisitions by fast-moving specialty chemical players. For buyers, a tiered-sourcing strategy — combining global incumbents for high-certainty supply with regional producers for cost flexibility — is recommended.
Practical implications for R&D and product teams
-
Prioritize a small number of sorbitan ester grades for platform formulations to reduce complexity while maintaining performance versatility.
-
Invest in accelerated stability testing focused on emulsion robustness across pH and temperature bands; this reduces late-stage reformulation costs and supports faster time-to-market.
-
Leverage supplier co-development programs for claims validation (e.g., “bio-derived” or “pharma-grade”) rather than developing in-house certifications that duplicate supplier capabilities.
Regulatory and ESG view: what to watch in 2026
Regulatory signals as of late 2025 and early 2026 have been largely supportive for cosmetic-grade sorbitan esters, but the broader regulatory environment is tightening on supply chain transparency and ingredient provenance. Brands that proactively document feedstock origins, manufacturing controls, and impurity profiles will minimize downstream risk and preserve access to sensitive markets.
From an ESG perspective, the industry is witnessing upward pressure for bio-based certifications and reduced cradle-to-gate carbon intensity. Suppliers who can demonstrate robust sustainability credentials will command a margin premium, particularly among premium and “clean beauty” customers.
Actionable 90-day plan for 2026
-
Map current exposure: quantify percentage of product portfolio reliant on sorbitan esters and identify single-source risks.
-
Initiate supplier risk audit: request updated QC and regulatory dossiers (including allergen and PFAS screening results) from core suppliers.
-
Run three stress scenarios in procurement models incorporating raw material price swings and two-tier demand scenarios from the PW Consulting report.
-
Engage R&D on a fast-track stability test for one high-volume SKU to explore a potential grade substitution that improves cost or sustainability profile.
Next steps & how to access the full intelligence
This brief is intended as a strategic preview. The full PW Consulting Cosmetic Grade Sorbitan Esters Market report contains the comprehensive segmentation analytics, proprietary supplier scorecards, detailed scenario models, and downloadable negotiation templates that support execution in 2026. To obtain the complete datasets, including granular regional and application breakdowns, supplier benchmarking, and our interactive forecast model, please consult the report landing page.
For companies making supply, formulation, or M&A decisions in 2026, this study converts market-level trends into executable steps. PW Consulting stands ready to support bespoke scenario modelling, supplier negotiation coaching, and integration planning to ensure your 2026 initiatives are both defensible and value-accretive.
For detailed analysis of this topic, please visit the official page: Cosmetic Grade Sorbitan Esters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High-Barrier MDO-PE Film Market Poised for 14.5% CAGR — Rising from USD 485.69 Million in 2025 to USD 1,253.16 Million by 2032
By pmarketresearch, 2026-07-06
High-Barrier MDO PE Film Market: Strategic Intelligence to Guide 2026 Decision-Making
PW Consulting’s new market study on High-Barrier Machine Direction Oriented Polyethylene (MDO-PE) film positions itself as an operational playbook for plastics, packaging, and FMCG leaders preparing strategic moves in 2026. Built from a robust historical window (2020–2025) and forward-looking forecasts (2026–2032), the report quantifies the market’s expansion trajectory and converts that signal into executable choices for R&D, procurement, operations, sustainability, and corporate development teams.
High Barrier Mdo Pe Film Market
Why this market matters in 2026
High-barrier MDO-PE films are increasingly treated not as a niche materials play but as a system-level lever for meeting recyclability mandates, reducing multi-material laminates, and preserving product integrity across food, pharmaceutical, and consumer-packaged goods. Our analysis shows a clear inflection: after rising from a modest base in 2020, the overall market system almost doubles by the 2025 base year and is forecast to more than double again through 2032. The model projects the market growing at a compound annual growth rate (CAGR) of 14.5% over the forecast window, reflecting accelerating commercial adoption, product downgrading opportunities (thinner gauges with equivalent performance), and regulatory-driven preferences for mono-material packaging.
High Barrier Mdo Pe Film Market
What this growth means operationally
At a 14.5% CAGR, demand-side dynamics will create tangible stress points and opportunities across the value chain:
High Barrier Mdo Pe Film Market
- Procurement: raw-material sourcing and grade availability will bifurcate into premium high-barrier grades and large-volume commodity PE; procurement strategies must shift from short-term spot buying to strategic offtake and blended-sourcing agreements.
- Production & Capacity: converters should assess capex cadence for MDO lines, downtime profiles for orientation equipment, and the economics of integrating EVOH or vacuum coatings versus coated/extruded barrier layers.
- Product Development: formulators and brand owners can trade laminate complexity for mono-material solutions—rebalancing optical, seal, and barrier properties to meet shelf-life without losing recyclability credentials.
- Sustainability & Compliance: with regulatory pressure rising (notably EU packaging regulations requiring recycled content in contact-sensitive packaging by 2030), MDO-PE offers a near-term pathway to compliance without sacrificing performance.
Market sizing and concentration — headline metrics
Our base-year assessment and scenario framework provide a defensible view of market scale and competitive density. The study’s bottom-up sizing confirms the material’s rapid expansion through 2025 and projects continued acceleration through 2032. Market concentration is moderate: the top three players account for roughly one third of the market, while the top five approach the mid-to-high forties as a percentage share — metrics that indicate room for regional champions and specialist entrants, while also signaling consolidation opportunities for larger incumbents.
Competitive landscape — who’s shaping the value chain
The competitive map is dominated by diversified film manufacturers, specialized MDO innovators, and global suppliers that combine barrier chemistry with PE mono-material architecture. Key players profiled in our assessment include large European film groups, Asian high-volume specialists, and North American converters strategically enabling shifts from BOPP/PET laminates to mono-PE solutions.
- RKW Group (Germany) has commercialized an integrated EVOH-in-PE offering — a product designed to compete with multi-material composites for barrier-sensitive applications while keeping the mono-material promise.
- Polifilm (Germany) positions its MDO-PE grades as replacements for PET/OPP/OPA in printed and laminated structures, emphasizing recyclability and mechanical stiffness.
- Several China-based producers have scaled high-barrier MDO-PE and AlOx-coated variants aimed at food and hygiene segments; these players compete on price-performance and local supply advantages.
- North American converters are focusing on optical performance and compliance pathways, enabling transitions for brands seeking How2Recycle alignment.
Recent product and collaboration activity confirms fast-moving technical progress: for example, a mid-2025 launch of an EVOH-integrated MDO-PE film and a late-2025 collaboration to downgauge cast MDO-PE for deep-freeze applications both demonstrate how manufacturers are compressing performance-per-thickness and creating immediate supply opportunities for brands that adopt early.
Regulation and raw-material dynamics — the immediate context
Two forces will dominate commercial decision-making in 2026:
- Regulatory mandates that require recycled content and mono-material strategies in certain contact-sensitive packaging categories are accelerating timelines for product conversions and supplier qualification.
- Raw material volatility — exemplified by swings in HDPE pricing and grade availability — will change cost pools and incentive structures for downgauging and material substitution. In practice, procurement teams must manage exposure to natural and colored HDPE spreads, which impact the economics of converting to high-barrier mono-PE versus retaining multi-material constructs.
Our report integrates publicly available pricing and market signals into scenario-based NPV models to show break-even windows for converting existing lines, investing in MDO capacity, or purchasing specialty high-barrier rolls versus laminated materials.
What the report contains — actionable modules
PW Consulting’s High-Barrier MDO-PE study is designed for immediate operational use. It includes:
- Market sizing and validated demand drivers (historical 2020–2025 and forecast 2026–2032).
- Supply-side mapping and capacity-by-technology assessment, with supplier scorecards that evaluate technical capability, geographic strength, and commercial readiness.
- Detailed cost models and sensitivity analyses for raw-material price trajectories, downgauging potentials, and laminate-replacement scenarios.
- Commercial playbooks for procurement, conversion timelines for brand owners, and adoption roadmaps for converters.
- Regulatory impact assessment and compliance playbooks tailored to EU 2030 recycled-content requirements and equivalent international trends.
- Risk matrix and mitigation plans (raw material, technology obsolescence, recycling infrastructure gaps) and recommended monitoring KPIs for 2026 execution.
- M&A and partnership scouting: target characteristics, valuation heuristics, and integration timelines for assets that complement scalable MDO-PE offerings.
To honour the “trailer” principle and preserve premiere value, the public release emphasizes strategic conclusions and frameworks while withholding full segment-level breakdowns and granular pricing tables — those are available to subscribers and licensees via the report portal.
Strategic plays for 2026 — five high-conviction moves
- Prioritize strategic offtake contracts for high-barrier grades now. With rapid demand growth projected, early commercial guarantees enable suppliers to justify capacity additions and help buyers secure consistent quality and pricing.
- Invest in downgauging pilots tied to rigorous shelf-life validation. Cost advantage from thickness reductions can be substantial — but only if barrier performance and sealing integrity are preserved across supply chain stresses.
- Define “mono-material” product families and run cross-functional trials. Legal, sustainability, and procurement must align on detectable performance thresholds that satisfy both regulators and retailers.
- Prepare sourcing dual-sourcing plans that hedge raw material price swings — blending locally produced high-barrier films with imports where logistics and lead times allow.
- Use M&A selectively to acquire specialized coating know-how or regional distribution networks that accelerate time-to-market for high-barrier mono-PE solutions.
How to use the report in 90 days
We recommend a disciplined three-phase activation plan for teams that deploy the report in early 2026:
- Day 0–30: Executive briefing and procurement stress-test. Adopt our price-sensitivity dashboards to quantify exposure and run vendor scenarios.
- Day 30–60: Cross-functional pilot design. Select 1–2 SKUs for downgauging/mono-material trials, define acceptance criteria, and secure test volumes with incumbent suppliers or new partners identified in the supplier scorecard.
- Day 60–90: Scale decision and roadmap. Based on pilot results, finalize capex needs, renegotiate commercial terms, and lock in implementation milestones aligned with regulatory compliance windows.
Final perspective
The High-Barrier MDO-PE segment represents a rare combination of regulatory tailwinds, measurable performance gains, and attractive unit-cost reduction opportunities through downgauging and laminate simplification. For executives mapping 2026 capital allocation and portfolio optimization, the market’s projected 14.5% CAGR and the measured concentration profile underscore both the urgency and the choice set: move early with targeted pilots and supplier partnerships, or prepare to compete later in a tighter market where scale and integrated capability matter.
PW Consulting’s full report provides the confidential segment-level analytics, supplier scorecards, and transaction playbooks that corporate leaders need to convert this growth trajectory into defensible market position. For access to the complete dataset, scenario models, and tailored advisory engagements, please visit the report landing page to request a sample chapter and speak with our industry practice leads.
For detailed analysis of this topic, please visit the official page: High Barrier Mdo Pe Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Small-Volume Personal Care Packaging Market to Grow at 4.4% CAGR to USD 9,171.8 Million by 2032; Asia Pacific Leads with USD 2,344.4 Million
By pmarketresearch, 2026-07-06
Small Volume Personal Care Packaging Market: Strategic Imperatives for 2026 — PW Consulting Insight Brief
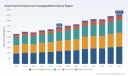
PW Consulting today releases its authoritative market study on the Small Volume Personal Care Packaging market, offering senior executives and product leaders an operationally focused playbook for 2026. Built on a 2025 base year and a seven‑year outlook, the report quantifies the market’s continuation of steady expansion — a compound annual growth rate of 4.4% through the 2026–2032 forecast window — and translates that trajectory into practical decisions for sourcing, innovation, sustainability compliance, and portfolio planning.
Small Volume Personal Care Packaging Market
Why this report matters for 2026 decisions
- Translate top‑line growth into executable moves: our forecast connects market momentum to specific format and channel implications that matter to procurement, R&D, and brand management teams.
- Turn regulatory shifts into opportunities: the study maps looming recycled-content mandates and Extended Producer Responsibility (EPR) developments to tactical product and supplier changes that limit disruption and capture first‑mover advantage.
- Derisk raw-material volatility: through detailed scenario modeling we show how cost shocks in polyolefin feedstocks propagate to unit economics and how to structure sourcing and pricing responses.
- Prioritize investments: the analysis helps decide where to pilot micro airless systems, low‑MOQ aesthetic formats, or unit‑dose technologies to accelerate time‑to‑market with controlled capital exposure.
What the full report delivers (practical, action‑oriented content)
- Forward-looking market model: an adjustable forecast engine (2026–2032) with configurable assumptions for pricing, substitution, and regulatory adoption so teams can stress‑test strategies under multiple scenarios.
- Competitive capability matrix: supplier benchmarking across design innovation, low‑MOQ readiness, recycled content capabilities, geographic footprint, and fill/finish partnerships.
- Regulatory & compliance playbook: plain‑language obligations, compliance timelines, cost-impact estimates, and a stepwise roadmap for achieving PCR content targets and EPR reporting requirements in priority jurisdictions.
- Sourcing and procurement toolkits: template RFIs/RFPs, marginal cost calculators for small‑volume SKUs, and negotiation playbooks tailored to low‑volume/low‑margin personal care items.
- Innovation tracker & case studies: profiles of recent product launches and platform upgrades—covering mini pump systems, airless microformats, pocket sprays, and compact refill architectures—paired with implementation checklists.
- Portfolio optimization framework: decision trees and scorecards to evaluate which SKUs to down‑size, convert to unit‑dose, adopt recycled content, or move into refill systems based on margin, channel, and brand positioning.
Market dynamics shaping strategies in 2026
Three converging forces define the operating context for 2026: continuing end‑market growth driven by trial and travel‑size demand, intensifying sustainability regulation, and episodic raw‑material cost volatility.
Small Volume Personal Care Packaging Market
- Regulatory pressure for recycled content and EPR is accelerating — several U.S. states have advanced or enacted mandates that elevate minimum post‑consumer recycled (PCR) requirements and expand producer responsibilities. For companies selling into regulated states, compliance planning and annual reporting will become operational necessities rather than optional sustainability initiatives.
- Polyethylene (PE) and polypropylene (PP) feedstock costs put acute pressure on small‑format plastic economics. Early‑2026 increases in North American PE/PP translate into tighter supplier margins and material surcharges. The report’s scenario module quantifies how these moves affect unit economics at the SKU level and which design adjustments or material swaps most effectively mitigate cost exposure.
- Consumer trends — premiumization in prestige skincare, hygiene and on‑the‑go convenience, and e‑commerce sampling — sustain demand for miniaturized and unit‑dose formats. Yet these same trends raise expectations for tactile quality, dosing precision, and sustainability credentials.
Competitive landscape — who to watch and why
The small‑volume packaging arena remains fragmented, with market concentration metrics indicating ample room for specialty players and continued innovation-led displacement. Leading suppliers combine scale with specialized microformat capabilities; a diverse set of smaller providers and niche specialists round out the ecosystem.
Small Volume Personal Care Packaging Market
- Albéa Group (France): a recognized leader in beauty packaging, Albéa’s low‑MOQ offerings and recent travel/serum bottle collection demonstrate how heritage cap/extrusion players are moving deeper into small‑volume, PCR‑capable formats. Brands seeking ready‑to‑market aesthetic solutions and regional low‑volume production should evaluate Albéa’s North America SKUs as a go‑to option.
- Aptar Beauty (U.S.): Aptar’s portfolio of mini pumps, micro airless systems, and recent dropper innovations shows a focus on precision dispensing for high‑value serums and dermocosmetics. Their Neodropper Autoload (2026) underscores a category trend: devices that enhance hygiene and dosing consistency can command premium pricing in prestige segments.
- Silgan Dispensing (U.S.) and Berry Global (U.S.): these large global suppliers couple scale manufacturing with expanding small‑format lines (including new smaller stick sizes and mini dispensing systems), offering pathways to cost‑effective production runs for mass and personal‑care brands pursuing recyclable offerings.
- HCP Packaging (U.K.) and Gerresheimer (Germany): players with strengths in compact design and glass/lightweight alternatives are positioned to service premium color cosmetics and fragrance segments where perceived material quality remains a purchase driver.
- Amcor, Unit Pack, JP Packaging: Amcor’s flexible sachets and paper‑based formats and unit‑dose specialists (Unit Pack, JP Packaging) represent tactical choices for sampling, trial, and single‑use technical applications where supply chain agility and fill/finish partnerships are decisive.
Recent supplier moves — from Aptar’s NeoDropper Autoload to Berry Global’s smaller stick sizes and Albéa’s North America collection — signal an industry incrementally aligning design innovation with recyclability and low‑MOQ manufacturing. These innovations should inform your 2026 supplier qualification and product development timelines.
Five actionable strategies for 2026
- Implement a dual‑track sourcing strategy: secure spot contracts for short‑term volume surges while negotiating longer‑term agreements tied to PCR supply to manage both cost and compliance risk.
- Pilot premium microdispensing tech for prestige launches: leverage micro airless and hygienic droppers in small runs to test willingness‑to‑pay before scaling.
- Design for recycled content now: prioritize mono‑polymer constructions and labeling clarity to meet fast‑approaching PCR mandates and simplify recyclability performance.
- Optimize SKU architecture on a margin‑per‑gram basis: use the report’s cost modeling templates to decide which SKUs should be converted to sachets, unit‑dose, or refillable cores to improve margins without sacrificing brand equity.
- Assess M&A and partnership targets with conveyorized scoring: target suppliers that provide low‑MOQ fill/finish capacity, integrated PCR content supply, or specialized dosing tech to shorten commercialization cycles.
Real use cases and pilot recommendations
For brands launching a new serum line in 2026: conduct a staged rollout using a PCR‑capable 30ml aesthetic bottle for flagship SKUs and micro airless samples for trial channels. For mass personal care SKUs under margin pressure: transition select SKUs to flexible sachets or unit‑dose formats and renegotiate packaging‑material indexation clauses to share raw material fluctuation risk with suppliers. The report provides stepwise pilot plans, expected timelines, and supplier pairing suggestions to operationalize both paths.
How to access the full intelligence
This brief highlights the strategic contours; the full PW Consulting Small Volume Personal Care Packaging Market report delivers the granular segmentation tables, supplier scorecards, downloadable forecast models, and the proprietary playbooks you need to act in 2026. For executives preparing budgets, sourcing plans, or NPD roadmaps, the report provides the evidence base and tools to move from strategy to execution quickly.
To secure the full report, data tables, and bespoke advisory engagements, visit PW Consulting’s report page or contact our Small Volume Packaging practice to arrange a tailored briefing and scenario walk‑through. Early adopters of the report’s playbooks will be best positioned to convert regulatory compliance and material disruption into competitive advantage in 2026.
For detailed analysis of this topic, please visit the official page: Small Volume Personal Care Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Sulphur Pastilles Market to Top USD 1,045.5 Million in 2025, Growing at a 4.12% CAGR Through 2032
By pmarketresearch, 2026-07-06
Sulphur Pastilles Market: Strategic Imperatives for 2026 — PW Consulting Insights
Executive summary
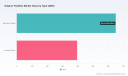
PW Consulting’s latest Sulphur Pastilles Market report (base year 2025) synthesizes five years of historical trade and production analysis (2020–2025) with a robust forward-looking forecast (2026–2032). The market, which expanded from approximately USD 855.2 Million in 2020 to USD 1,045.5 Million in 2025, is projected to continue expanding under multiple macro and micro drivers to reach an estimated USD 1,386.96 Million by 2032. PW Consulting models the addressable market to grow at a compound annual growth rate (CAGR) of 4.12% across the 2026–2032 forecast window.
Sulphur Pastilles Market
Why this report matters to executive teams in 2026
- Timing: 2026 is a pivot year for procurement, pricing, and logistics strategies amid sharp feedstock volatility and evolving transport/regulatory interpretations.
- Actionability: The analysis translates market trajectories into concrete commercial levers — procurement hedges, SKU packaging choices, storage investments, and priority M&A targets — enabling boards and strategy teams to move from insight to execution.
- Risk-adjusted planning: The report’s scenario-based financial models let CFOs stress-test working-capital outcomes and margin sensitivity under plausible sulphur price swings and demand shifts.
Market dynamics and near-term shocks
Two themes dominate the current operating environment: supply-feedstock price volatility and evolving transport/regulatory clarity for formed sulphur products.
Sulphur Pastilles Market
- Price volatility: In early 2026 commodity sulphur prices experienced abrupt upward movement. For example, prices were reported at 6,700 CNY/T on April 3, 2026 — representing a multi-week and year-on-year spike. Published regional price checkpoints from January–March 2026 indicate meaningful geographic variance in CIF/FOB pricing and point to localized cost differentials that materially affect landed cost economics for exporters and importers alike.
- Regulatory/transportation certainty: Interpretations of hazardous-materials regulations have continued to evolve. Notably, formed sulphur (including pastilles) transported in non-bulk packaging is interpreted in several major jurisdictions as not subject to Hazardous Materials Regulations. Equivalent classifications under national transport codes (e.g., Australia’s ADG Code) reduce compliance friction for many shippers, shifting focus toward packaging design and documentation to exploit safer, lower-cost transport modalities.
Supply, concentration and competitive tension
The Sulphur Pastilles market shows moderate concentration: the top three firms account for a meaningful share of global capacity while the top five increase that footprint further. Specifically, PW Consulting’s market concentration analysis places CR3 at approximately 38.5% and CR5 near 52.3%. This structure creates a dual dynamic — established players sustain scale advantages in logistics and large off-take contracts, while a varied set of regional and specialist producers retain pricing flexibility and niche product strengths.
Sulphur Pastilles Market
What the report contains — operational intelligence for 2026 decisions
- Demand modelling: granular demand-driver matrices calibrated to agricultural cycles, fertilizer reformulation trends, rubber and chemical processing throughput, and "others" categories — all translated to regionally nuanced volume and price scenarios (note: detailed split tables are reserved for the full report).
- Supply-mapping and plant-level intelligence: capacity by technology (e.g., rotoform, drop-forming), operational footprints, typical warehousing/packaging approaches, and logistics corridors that influence lead times and cost to serve.
- Price-sensitivity and margin playbooks: stress-tested P&L impacts of commodity swings and freight disruptions, with merchant, tolling and contract vs. spot procurement strategies quantified for a range of buyer archetypes.
- Regulatory and packaging decision matrix: an actionable checklist for exploiting non-bulk transport classifications while maintaining safety, insurance and customer-acceptance standards.
- Commercial go-to-market templates: channel segmentation, premiumization levers (e.g., micronutrient-enriched pastilles), pricing architecture and tendering playbooks tailored to fertilizer producers, industrial processors and specialty end-users.
- M&A and partnership playbook: screening criteria, valuation multiples guidance, integration risk checklists and prioritized target archetypes for both accretive bolt-ons and transformative scale deals.
Competitive landscape — profiles and strategic implications
Our competitive analysis synthesizes primary interviews, plant visits and public data to profile leading manufacturers and their distinct strategic positions:
- Martin Midstream Partners L.P. (USA) — A producer with multiple formed-sulphur facilities and capability to produce Multipurpose Sulfur grades. Strengths: integrated logistics and proximity to North American feedstock. Strategic implication: advantaged for high-volume industrial contracts and tolling arrangements with regional processors ( https://mmlp.com).
- Coogee Chemicals (Australia) — Established chemistry and logistics expertise serving both industrial and agricultural channels. Strengths: regional distribution networks and blended product offerings ( https://www.coogee.com.au).
- Tiger-Sul Products LLC (Tessenderlo Kerley Inc.) (USA) — Offers industrial-grade pastilles alongside specialty sulphur products (micronutrient blends, bentonite mixes) with international processing and warehousing. Strategic implication: positioned to capture premium yield through differentiated SKUs ( https://www.tigersul.com).
- Georgia Gulf Sulfur Corporation (USA) — Known for rotoform technologies producing distinctive particle shapes and a legacy industrial-sulphur product line. Strengths: manufacturing process IP and product uniformity suited to automated dosing systems ( https://www.georgiagulfsulfur.com).
- Grupa Azoty Siarkopol (Poland) — European-formulated pastille producer with storage and handling practices aligned to industrial supply chains. Strengths: regional sourcing and customer proximity ( https://grupaazoty.com).
- National Est. For Agricultural & Industrial Sulphur (Saudi Arabia) — Uses drop-forming tech and brands targeted at agricultural markets; strategic implication: low-cost feedstock access in Middle East markets ( https://www.neais.net).
- Regional and specialist suppliers (examples include Swancorp, Devco Australia, Brimfert, Passion Ag, BTSCO, Petro Arkan) — These firms excel at nimble supply to niche customers, high-purity product lines, or localized logistics advantages.
Collectively, the landscape suggests a two-track competitive environment: scale players optimizing cost-to-serve for commodity-grade demand, and specialist suppliers capturing value in differentiated, higher-margin applications.
Strategic recommendations for 2026 planning cycles
- Prioritize procurement resilience: implement multi-scenario hedging and supplier-scorecard frameworks that incorporate feedstock price signals, freight elasticity, and regional regulatory differentials. Shortlist secondary suppliers within a six- to nine-month readiness window to buffer against spot spikes.
- Reassess packaging and transport strategies: where regulatory interpretations permit, shift higher-volume shipments toward non-bulk, formed-pastille configurations to lower compliance costs and expedite customs clearance. Pair packaging investments with customer education to reduce rejection risk.
- Differentiate product portfolios: invest in micronutrient-enhanced pastilles and low-dust formulations for premium segments (e.g., food-grade processing, precision fertilizer blends). Use product differentiation to protect margin against commodity price cycles.
- Supply-chain localization vs. scale arbitrage: for players with regional end-markets, evaluate near-market micro-facility or tolling arrangements to reduce lead times and inventory carrying costs; for traders and large processors, pursue scale through regional warehousing hubs.
- M&A and partnership targeting: given the market’s CR3/CR5 profile (moderate concentration), opportunistic acquisitions of niche-capability firms or warehousing platforms can accelerate access to premium channels while delivering synergies in freight and inventory optimization.
- Embed regulatory monitoring and contingency playbooks: align commercial contracts to clear transport and storage responsibilities, and audit packaging specs quarterly to capitalize on favorable classification shifts without exposing compliance risk.
How PW Consulting supports execution
Beyond the market intelligence, PW Consulting provides an implementation-focused toolkit: supplier and plant-level due diligence, detailed landed-cost calculators, integration playbooks for acquisitions, and a 12–18 month commercialization sprint program that bridges strategy to measurable EBITDA outcomes. For procurement teams, we deliver scorecards, tender templates and a playbook to synchronize hedging with working-capital policies. For corporate development teams, we provide prioritized target lists and a phased integration roadmap optimized to retain customer contracts and preserve operational continuity.
Next steps and access
This press release highlights the strategic contours and action levers from PW Consulting’s Sulphur Pastilles Market report. To preserve the commercial value of our proprietary segmentation, plant-level datasets and the full suite of scenario outputs, detailed split tables and granular financial models are available only in the full report. Executive teams planning for 2026 procurement cycles, commercial launches or M&A activity are encouraged to access the complete study for the operational templates, vendor scorecards and valuation models.
Contact PW Consulting to request the full Sulphur Pastilles Market report and tailored briefings for board and executive planning sessions.
For detailed analysis of this topic, please visit the official page: Sulphur Pastilles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Insight: C9 Petroleum Resin Market Poised to Grow at a 4.85% CAGR
By pmarketresearch, 2026-07-06
C9 Petroleum Resin Market — Strategic Preview for 2026: Why PW Consulting’s C9 Report Will Shape Your Next Move
PW Consulting’s newly completed C9 Petroleum Resin Market report (base year 2025; historical window 2020–2025; forecast horizon 2026–2032) offers a focused, decision-ready examination of a niche yet indispensable class of hydrocarbon resins. Our analysis quantifies the market’s trajectory and decodes the operational and strategic levers that will matter most to producers, downstream formulators, investors, and procurement teams as they set priorities for 2026 and beyond.
C9 Petroleum Resin Market
Executive snapshot
- The global C9 petroleum resin market demonstrated robust recovery and steady expansion through 2020–2025, moving from a mid‑single‑billion dollar base in 2020 to a substantially larger total by the 2025 base year (figures in USD Million).
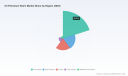
- PW Consulting projects continued growth across the forecast window (2026–2032) at a compound annual growth rate (CAGR) of approximately 4.85%, reflecting steady downstream demand and selective capacity additions.
- By the end of the forecast horizon, total market value is expected to be materially higher than the 2025 baseline, underlining opportunities for margin recovery, portfolio premiumization, and strategic consolidation.
What the report contains — tactical, transaction-grade intelligence
- Granular market sizing and mid‑term forecasts (total market and breakouts by region, process type, and application) that support revenue planning and investment appraisals.
- Supply‑chain topology and feedstock mapping: origins of the C9 aromatic fraction, sensitivity to ethylene cracker feedstock choices, and scenarios for upstream availability through 2032.
- Price dynamics and margin modelling that link cracker economics, naphtha/ethane cycles, and resin plant operating strategies.
- Demand-side diagnostics across adhesives, coatings, printing inks, rubber compounding and other end‑use clusters — including buying patterns, technical specifications, and switching costs.
- Competitive landscaping with proprietary company profiles, capability matrices, and opportunity‑fit assessments for potential M&A, JV or greenfield investments.
- Regulatory and materials‑safety intelligence: practical implications of recent hazard assessments and reporting thresholds for industrial chemicals in key jurisdictions.
- Actionable strategic recommendations, investment scenarios and a risk dashboard designed for C‑suite use in 2026 budgeting and scenario planning.
Market snapshot & forecast — the big picture you need
Across the 2020–2025 period, the C9 petroleum resin market displayed resilience amid feedstock swings and downstream demand normalization. PW Consulting’s calibrated bottom‑up model shows a market that expanded significantly by the 2025 base year, and is projected to continue ascending through 2032 under a central case that assumes steady industrial growth and modest capacity additions. With a 2026–2032 CAGR of roughly 4.85%, the market offers predictable growth for differentiated products while remaining exposed to upstream volatility tied to ethylene cracker configurations and naphtha pricing.
C9 Petroleum Resin Market
For decision-makers, the immediate implication is clear: base‑case topline growth will not alone solve margin pressure. Competitive advantage will accrue to players who control feedstock optionality, extract product premia through formulation specificity (e.g., hydrogenated or crosslinkable grades), and embed supply resilience close to key end‑use clusters.
C9 Petroleum Resin Market
Key market dynamics shaping 2026 decisions
- Feedstock availability and cracker economics: The C9 aromatic fraction is a byproduct of steam cracking. A structural shift in cracker feedstock — notably toward ethane in some regions — reduces C9 byproduct yields and increases supply cyclicality. Procurement and asset‑siting decisions must be stress‑tested against these upstream scenarios.
- Downstream demand heterogeneity: Adhesives, coatings, inks and rubber compounds each value different resin attributes (tack, softening point, compatibility). Commercial strategies that segment customers by technical needs — not just volume — will capture higher margins.
- Product and process differentiation: Thermal vs catalytic polymerization and hydrogenation create distinct performance and cost profiles. Innovations such as crosslinkable hydrocarbon resins present premium pathways; manufacturers with proprietary process know‑how will command leverage.
- Pricing and margin volatility: Resin prices remain sensitive to feedstock swings. Buyers and sellers should incorporate dynamic hedging, flexible contract structures, and price‑escalation clauses linked to upstream indices.
- Regulatory context and material classification: Recent assessments affirm that many hydrocarbon resins are low‑hazard and qualify for certain reporting simplifications. While regulatory tailwinds reduce compliance cost in some markets, firms must still monitor classification changes and local labeling or disclosure norms.
Competitive landscape — implications for strategy and M&A
The C9 resin arena features a mix of integrated global players, regional specialists, and high‑volume capacity in select manufacturing hubs. Our competitive review highlights several archetypes and practical lessons:
- Integrated oil & chemical producers (feedstock control advantage): Companies that can internalize C9 feedstock via cracker operations have a structural cost edge and the ability to prioritize allocation to strategic downstream units. This integration influences pricing discipline and can create barriers for pure‑play resin traders.
- Regional champions and secure‑supply specialists: Established domestic producers — particularly those serving local industrial ecosystems — offer a value proposition centered on supply security and rapid technical support. This is a critical consideration for downstream formulators with Just‑in‑Time manufacturing footprints.
- Innovation‑led differentiators: Firms that commercialize novel resin chemistries (e.g., crosslinkable grades, tailored hydrogenated resins) can capture premium niches in high‑performance adhesives and coatings. Protecting IP and accelerating customer trials are priority actions for R&D‑led players.
- High‑volume manufacturers in Asia: Lower‑cost manufacturing bases and proximity to large downstream markets create scale advantages, but China‑based producers also face increasing scrutiny on quality consistency and environmental compliance — considerations that affect export prospects.
For 2026 planning, executives should treat portfolio decisions through the lenses of feedstock control, product differentiation, and geographic proximity. Options to explore include bolt‑on acquisitions to secure C9 feedstock, JVs with cracker operators, conversion of existing aromatics capacity to higher‑value specialty grades, or targeted investments in hydrogenation and catalytic process capabilities.
How to use PW Consulting’s report in your 2026 playbook
- Capex prioritization: Use our demand scenarios and feedstock sensitivity analysis to rank prospective investments — new plant capacity, debottlenecking, or process upgrades — by IRR under multiple cracker‑feedstock outlooks.
- Procurement and hedging: Implement procurement playbooks informed by our price‑modelling; consider long‑term supply contracts with indexation, or strategic inventory cushions in markets exposed to ethane conversion.
- Commercial strategy and product mix: Reallocate commercial focus toward higher‑margin specialty grades where customer switching costs are highest; deploy technical service teams to accelerate qualification cycles.
- M&A and partnership screening: Use our company profiles and capability matrices to identify targets and JV partners that would secure feedstock, add process know‑how, or expand access to premium end markets.
- Regulatory and ESG alignment: Leverage the report’s regulatory appendix to streamline compliance and to frame product stewardship narratives that resonate with industrial customers and procurement teams.
Methodology and assurance
PW Consulting’s findings are grounded in a hybrid methodology: bottom‑up plant and company production data, top‑down macro demand modelling, and primary interviews with producers, formulators and feedstock suppliers. We apply scenario analysis to stress‑test forecasts against alternative cracker feedstock mixes and feedstock price pathways. The result is a defensible, transaction‑grade view suitable for board‑level decision support, M&A diligence, and procurement strategy.
What we are deliberately not disclosing here (and why)
In keeping with the “trailer” principle of this release, we have intentionally withheld granular regional and application split tables, as well as cell‑level revenue forecasts and some proprietary competitive scores. These items are part of the full PW Consulting dataset and analytic output, which is designed for clients who require transaction‑quality modelling and confidential benchmarking. Releasing those line‑items publicly would dilute their strategic value to subscribing clients.
Final note — the strategic cliff‑edge for 2026
2026 represents an inflection point where upstream cracker strategies, midstream allocation practices, and downstream demand composition converge. While headline growth is steady, the real prize in the C9 resin market will go to organizations that convert market insight into structural advantage: securing feedstock optionality, scaling differentiated chemistries, and forging commercial linkages with the most profitable downstream segments. PW Consulting’s C9 Petroleum Resin Market report equips executives with the scenarios, supplier intelligence, and operational playbooks to make those decisions with confidence.
For access to the full dataset, detailed regional and application splits, proprietary company scorecards and the complete suite of strategic recommendations, visit PW Consulting’s report page or contact our industrials team to arrange a briefing and data licence.
For detailed analysis of this topic, please visit the official page: C9 Petroleum Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Essential Rose Oil Market Valued at USD 568.0 Million in 2025, Poised for 6.5% CAGR Through 2032
By pmarketresearch, 2026-07-06
Essential Rose Oil Market 2026: Strategic Imperatives from PW Consulting’s New Market Brief
Executive summary
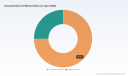
PW Consulting today releases the Essential Rose Oil Market — Essential Rose Oil Market 2026 Brief, a targeted intelligence product built to inform executive decisions as firms enter a pivotal growth window. Our analysis shows the global essential rose oil market expanding from an estimated USD 568.0 Million in 2025 to an anticipated USD 882.7 Million by 2032, implying a mid‑to‑high single‑digit compound annual growth rate (CAGR) of approximately 6.5% through the forecast period. That growth is being driven by simultaneous premiumization across cosmetics and perfumery, rising interest in natural aromatherapy and therapeutic applications, and renewed sourcing strategies led by major fragrance houses and specialty suppliers.
Essential Rose Oil Market
Why this brief matters for 2026 decision cycles
- Actionable foresight: 2026 marks the start of the modelled forecast period (2026–2032). Procurement, R&D and M&A calendars should align now with our scenario timelines to capture upside.
- Supply risk meets demand opportunity: The market growth rate and concentrated supply base create both margin upside for brands and structural exposure for buyers—necessitating immediate strategic responses.
- Investment prioritization: Capital allocation decisions tied to traceability, sustainable certification, and downstream formulation strategies will materially affect position in the premium segment by 2028–2030.
Market outlook & macro dynamics
Our baseline scenario projects continued acceleration of the rose oil market driven by (1) premium perfumery and clean‑beauty demand, (2) aromatherapy and therapeutic adoption in developed markets, and (3) diversification of supply chains to mitigate sourcing concentration. The market expanded notably in the early 2020s — from roughly USD 418.5 Million in 2020 to USD 568.0 Million in 2025 — and our forecast growth reflects both volume expansion and a structural price component tied to raw material constraints.
Essential Rose Oil Market
Two structural characteristics underpin the outlook and require immediate attention in 2026 planning:
Essential Rose Oil Market
- Labor and raw‑material intensity. Rose oil extraction remains extraordinarily labor‑intensive; large quantities of fresh petal biomass are required per unit of finished oil, and harvesting is seasonally compressed. These factors create short, highly leveraged supply windows and amplify labor cost and availability risks.
- Geographic concentration and regulatory protection. Traditional production regions dominate global supply and benefit from geographic indications and well‑established cultivation systems. That concentration supports quality reputation but increases exposure to climate, labor and policy shocks.
Price and procurement dynamics (teaser)
Price volatility in recent seasons has been pronounced, creating a two‑track pricing environment: spot market spikes during constrained harvests, and premium hedging for certified, traceable lots contracted in advance. Our full report models alternative price paths under multiple harvest and certification scenarios — including stress cases for low yields and upside cases tied to premiumization — and translates these into procurement playbooks for buyers, formulators and ingredient traders. Note: detailed price-path matrices and contract simulation outputs are reserved for the full report.
Report contents — what executives will find inside
- Market sizing and forecast model (2020–2032) with scenario branches and sensitivity testing calibrated to biological yield variability.
- Practical procurement playbook for 2026: contracting templates, indexation clauses, and third‑party verification checkpoints for secure offtake.
- Grower economics and seasonal labour modeling: cost drivers, break‑even analyses, and policy levers to stabilize supply during the narrow harvest window.
- Traceability and sustainability pathways: certification impact assessments (including organic and ethical sourcing frameworks), comparative ROI on traceability investments, and a phased implementation roadmap for downstream players.
- Extraction and processing technology comparison: classical steam distillation versus modern hybrid extraction, yield tradeoffs, energy use, and CAPEX/OPEX benchmarks for distilleries and centralized processing hubs.
- Price risk management toolkit: hedging approaches, blended sourcing strategies, and contract structures to protect margin while securing quality lots.
- Regulatory and IP appendix: geographic indication frameworks, labelling rules, and compliance hotspots for cosmetics and flavor use cases.
Competitive landscape — strategic read of market players
The rose oil value chain is anchored by a mix of specialist growers/distillers and global flavor & fragrance houses. Industry concentration is meaningful: the three largest suppliers account for a substantial share of trade, and the top five firms approach a majority share of market influence. That structure shapes bargaining power, innovation diffusion, and the pace at which sustainability standards are adopted.
- Specialist growers and distillers (Bulgaria, Turkey and beyond). Established producers with integrated cultivation and distillation capabilities remain the backbone of supply. Profiles such as long‑standing family producers and modern organic operators blend heritage cultivation knowledge with traceability investments. Their control of field‑to‑bottle workflows confers comparative advantage in certified and fully traceable lots, a category that commands premiums in perfumery and therapeutic applications.
- Regional organic and ethical leaders. Organic operators that can demonstrate full traceability from their own fields are increasingly attractive partners for premium brands requiring supply chain integrity. These firms are not only suppliers but strategic allies for co‑developing provenance narratives and certified product lines.
- Global fragrance houses and integrators. Major fragrance and flavor firms are actively reconfiguring upstream relationships—through direct sourcing, minority investments, or strategic offtakes—to lock in certified volumes and to secure influence over extraction techniques and traceability. Their 2030 strategies increasingly emphasize sustainable sourcing and vertical integration in botanicals, including rose oil.
- Ingredient traders and consolidators. Regional distributors and commodity merchants continue to expand portfolios through M&A and geographic diversification, seeking scale and broader channel reach. These players are central to short‑term market liquidity but face margin pressure unless they augment value with traceability services and quality assurance.
Recent market signals to watch in 2026
- Strategic announcements from global fragrance houses setting 2030 sustainability targets reflect a higher willingness to underwrite premium sourcing arrangements and to invest in upstream capacity.
- Certification wins among regional producers validate demand for ethically sourced and traceable lots—and create differentiated supply that commands term contracts.
- Consolidation moves by multinational distributors expand route‑to‑market reach, shifting negotiating power toward integrated suppliers who can ensure year‑round availability.
Implications for corporate strategy (practical, prioritized actions for 2026)
- Procurement: Move from spot purchases to a tiered contracting approach. Allocate a core of certified, traceable volumes under multi‑year offtakes and complement with opportunistic spot buys to capture pricing troughs.
- Supply resilience: Invest in dual sourcing (geographic + technological), and consider minority equity in upstream growers/distillers to secure preferred access during tight seasons.
- Product strategy: For brands, prioritize premiumized SKUs that can justify the incremental ingredient cost through storytelling and verified provenance; for ingredient players, bundle traceability and certification as a service.
- Sustainability ROI: Prioritize spend on traceability systems that map to market value (e.g., organic certification for perfumery premiums, ethical sourcing for healthcare applications). The highest returns occur when traceability is integrated with consumer‑facing narratives.
- R&D and formulation: Explore concentration, micro‑encapsulation and hybrid blends to stretch scarce raw material, while preserving olfactory and therapeutic profiles. These technical levers can mitigate exposure to raw material tightness without compromising brand integrity.
What PW Consulting’s brief does not disclose — and why you should download the full report
In keeping with our “trailer” approach this press brief highlights strategic findings and actionable recommendations while reserving core datasets—detailed regional and application splits, the full price‑path model, contract templates, and granular supplier scorecards—for the full Essential Rose Oil Market report. These discreet datasets and proprietary matrices are central to contract negotiations, M&A due diligence and tactical procurement execution; they are available through the report portal.
Final thought — four strategic bets for 2026
- Bet on premiumization: Consumers continue to pay for verified provenance. Position brands and SKUs to capture that premium where margins allow.
- Bet on vertical resilience: Equity partnerships or strategic offtake contracts are increasingly a determinant of year‑over‑year ingredient security.
- Bet on traceability as market access: Certification and traceable supply are becoming entry requirements for premium channels and institutional buyers.
- Bet on blending & tech: Technical innovations that extend supply or enable high‑quality synthetic complements will be critical risk‑mitigation tools.
For 2026 planning, executives need both the big picture and the operational blueprints: PW Consulting’s Essential Rose Oil Market brief provides the former and our full report delivers the latter. To access the detailed models, supplier scorecards and contract playbooks that underpin these findings, please visit the PW Consulting research portal.
For detailed analysis of this topic, please visit the official page: Essential Rose Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Diphenylmethanol Market to Expand at 4.78% CAGR — Asia Pacific Leads with USD 184.94 Million in 2025
By pmarketresearch, 2026-07-06
Diphenylmethanol Market Outlook 2026 — Strategic Briefing for Corporate Decision-Makers
PW Consulting’s latest market study on Diphenylmethanol (benzhydrol, CAS 91-01-0) provides a practical, decision-ready briefing for executives planning investments, sourcing strategies, and R&D roadmaps in 2026. Built on a 2020–2025 historical foundation with a dedicated 2026–2032 forecast horizon, the report translates macro trends into operational choices — while reserving granular segment tables for the full release to protect competitive sensitivity and drive targeted engagement.
Diphenylmethanol Market
Market Snapshot: Momentum, Scale, and Forecast
The Diphenylmethanol market has shown steady expansion over the last half-decade, rising from a market size in 2020 to a materially larger base by the 2025 reference year. Under our forecast assumptions, the market is expected to continue its upward trajectory through 2032 at a compound annual growth rate (CAGR) of approximately 4.78% (USD, revenue unit: Million). This rate reflects a combination of pharmaceutical intermediate demand resiliency, specialty chemical applications, and incremental penetration into niche downstream uses driven by formulation trends.
Diphenylmethanol Market
For strategic planners, three high-level takeaways flow from the numbers: (1) the market is large enough to warrant dedicated sourcing and product development strategies; (2) growth is steady rather than explosive, which favors disciplined, phased capital deployment; and (3) visibility to 2032 allows multi-year contracts and capacity planning to be aligned with expected demand curves rather than short-term volatility.
Diphenylmethanol Market
Why This Report Matters for 2026 Decisions
- Investment timing and scale: The combination of mid-single-digit CAGR and established baseline volumes suggests that greenfield projects should be sized conservatively or staged incrementally. Brownfield expansions and toll-manufacturing partnerships generally offer better risk-adjusted returns for market entrants in 2026.
- Sourcing strategy optimization: Buyers will benefit from shifting from purely price-driven supplier selection to a dual-focus on quality tiers and logistics resilience. The report provides supplier scorecards and negotiation frameworks that can be operationalized immediately.
- Product differentiation and margin capture: As end-users increasingly value higher-purity intermediates and tailored specifications for API synthesis and specialty formulations, producers that can demonstrate controlled impurity profiles and regulatory traceability command premium positioning.
- Regulatory and safety compliance: Safety classifications and regulatory status materially influence product stewardship, packaging, and labeling choices — all of which are included in the report’s compliance checklist for 2026 market entry and product relaunch decisions.
Actionable Report Contents — What You Can Use Day One
PW Consulting designed this study to be operationally useful. Key deliverables included in the full report are:
- Forward-looking market model with scenario toggles (base, upside, downside) and sensitivity levers for price, feedstock cost, and demand elasticity.
- Supplier and capacity map with vetted due-diligence criteria and an actionable supplier short-listing methodology.
- Unit cost benchmark templates and a build-your-own capex/opex calculator for brownfield vs. greenfield cases.
- Commercial playbooks for contract strategy (term length, volume bands, penalty mechanisms) and distribution channel optimization for specialty vs. reagent-grade sales.
- Technical appendix comparing reduction routes, key process parameters, and environmental footprint implications for major synthesis technologies.
- Regulatory and safety checklists that translate hazard classifications into product stewardship actions and labeling pathways.
- M&A and partnership scorecards, including integration risk matrices and value capture levers for bolt-on acquisitions in regional markets.
Each deliverable is accompanied by templates and step-by-step implementation guidance so corporate development, procurement, and technical teams can act immediately upon the report’s insights.
Competitive Landscape — How to Read the Players
The Diphenylmethanol supply base spans custom-synthesis specialists, industrial intermediates manufacturers, and premium laboratory reagent distributors. The market shows a moderate degree of concentration: the top three players account for around 38.45% of market share, while the top five reach approximately 54.12%. For decision-makers, that concentration profile signals a market where scale matters but where differentiated strategies remain viable for focused players.
- Capot Chemical Co., Ltd. (Hangzhou, China — https://www.capotchem.com) : Positioned as a custom-synthesis and high-purity fine-chemicals provider, Capot’s strengths lie in flexible scale-up capability and targeted pharmaceutical-grade offerings. Their model suits customers seeking tailored grades and development-stage supply partnerships.
- Catapharma Chemicals Pvt. Ltd. (India — https://www.catapharma.com) : A regional manufacturer and supplier focused on solid intermediates for pharmaceuticals and perfumery. Competitive cost structures and export orientation are key advantages, making Catapharma a typical partner for volume-driven programs.
- Vasudha Chemicals Pvt. Ltd. (Mumbai, India — https://vasudhachem.com) : A diversified specialty chemical maker supplying intermediates across pharmaceuticals, cosmetics, and rubber. Their breadth of product lines supports cross-selling and integrated supply agreements.
- Gunjal Industries (Ankleshwar, Gujarat, India — https://www.gunjalindustries.com) : Export-oriented manufacturer of high-purity industrial-grade benzhydrol. Their emphasis on purity and compliance appeals to clients in regulated markets seeking predictable quality.
- Amar Healthcare (India — https://www.amarhealthcare.in) : An API and intermediate manufacturer whose offering of Diphenylmethanol is often integrated into broader API supply chains, enhancing value in long-term supplier relationships.
- S. Nihar Exports (Mumbai, India — https://sniharexports.com) : A supplier and custom manufacturer serving pharmaceutical and research segments, characterized by flexibility and focus on standard purity grades.
- TCI Chemicals (Tokyo, Japan — https://www.tcichemicals.com) : Global supplier of high-purity benzhydrol for laboratory and research applications. TCI’s premium positioning and global distribution network suit research and analytical channels.
- Sigma-Aldrich / Merck KGaA (Darmstadt, Germany — https://www.sigmaaldrich.com) : A leading provider of reagent- and standard-grade Diphenylmethanol, with global brand strength in quality control and reference materials. Their channel reach and certification portfolio make them the default choice for regulated analytical requirements.
Strategic implications: small-to-medium manufacturers should emphasize niche purity profiles, supply reliability, and regulatory traceability to defend margins, while larger players can pursue scale, breadth, and price-led competition. The CR3/CR5 concentration metrics indicate room for consolidation, but only where scale advantages translate into improved logistics, feedstock procurement, or regulatory compliance efficiencies.
Manufacturing, Feedstock, and Process Considerations
Technically, Diphenylmethanol is most commonly produced by reduction of benzophenone. Commercial routes include catalytic hydrogenation as well as classical metal-based reductions such as aluminum powder in alkaline methanolic media or zinc dust under basic conditions. Benzophenone acts as the primary upstream feedstock; its availability, quality, and price volatility are therefore central to supply economics.
Choosing a production route has strategic consequences beyond CAPEX and yields: hydrogenation requires hydrogen supply and specialized catalysts but often offers cleaner impurity profiles and easier scale-up, whereas metal-based reductions may have lower initial equipment costs but generate metal-containing wastes that increase downstream treatment cost and regulatory complexity. Our technical appendix compares these routes using unit-cost models and environmental-impact matrices tailored for 2026 operational realities.
Regulatory and Safety Environment
From a product stewardship perspective, Diphenylmethanol is classified under the CLP system as Skin Irrit. 2 (H315), Eye Irrit. 2 (H319), and STOT SE 3 (H335). Critically, it is not currently listed for authorisation or restriction under the most restrictive elements of the EU REACH Annex XIV/XVII frameworks, which preserves operational flexibility for producers and users. Nonetheless, the hazard profile requires deliberate controls in handling, packaging, and transport — a topic addressed through actionable compliance checklists in the report.
Risk Matrix and Scenario Planning for 2026
- Supply disruption risk: Concentrated feedstock sourcing or single-region dependence can amplify exposure. The report’s supplier diversification playbook is designed to quantify trade-offs between cost and resilience.
- Regulatory shift risk: Although not presently subject to Annex XIV/XVII restrictions, future regulatory tightening or local hazard-based controls could alter cost-to-serve in key markets; the report includes trigger-based contingency plans.
- Price and margin risk: Feedstock and energy cost swings are the primary drivers of input-cost variability. Our sensitivity scenarios show the break-even points for different business models (toll, merchant, integrated production).
- Technological risk: Advances in selective reduction technologies or new catalytic systems could change unit-cost economics — an upside scenario modeled in the report.
Next Steps — How PW Consulting Supports Your 2026 Playbook
For executives preparing operational budgets, capital plans, or M&A pipelines for 2026, PW Consulting’s Diphenylmethanol study delivers market-context intelligence plus a toolkit for execution. The public briefing intentionally omits granular regional and application-level split tables to preserve the strategic value of the full dataset — available through our web portal and tailored client briefings.
Contact PW Consulting to obtain the full dataset, the complete set of supplier scorecards, the capex/opex calculator, and a one-on-one executive briefing that translates the study’s findings into a prioritized action plan for your organization.
About PW Consulting
PW Consulting advises chemical producers, pharmaceutical companies, and private equity investors with market research and deal-oriented strategy. Our reports combine primary supplier diligence, techno-economic modeling, and regulatory analysis to produce practical, implementable recommendations aligned with each client’s risk tolerance and strategic horizons.
For detailed analysis of this topic, please visit the official page: Diphenylmethanol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pseudoboehmite Market Poised to Grow at a 5.22% CAGR Through 2032
By pmarketresearch, 2026-07-06
Pseudoboehmite Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
As global supply chains recalibrate and catalyst-driven value chains pursue higher performance with lower environmental footprints, pseudoboehmite has re-emerged as a strategic material for petrochemical catalysts, adsorbents, advanced ceramics and specialty applications. PW Consulting’s latest Pseudoboehmite Market report — covering 2020–2025 historical performance and a 2026–2032 forecast — synthesizes macro drivers, supplier economics and go-to-market playbooks that will determine winners and losers through 2026 and beyond.
Pseudoboehmite Market
Headline market view: steady recovery, structural opportunity
Our base-year assessment shows the pseudoboehmite market expanding from a mid-single‑hundred million USD base in 2020 to an estimated USD 654.6 Million in 2025, reflecting recovery from cyclic pressures and investments in higher-purity product lines. Under our central forecast the market is projected to grow at a compound annual growth rate (CAGR) of approximately 5.22% across 2026–2032, reaching roughly USD 935 Million by 2032. That trajectory captures both cyclical demand for refinery and petrochemical catalysts and medium-term secular shifts driven by stricter performance and environmental specifications across multiple end markets.
Pseudoboehmite Market
Why 2026 is pivotal for corporate strategy
- Margins are being re-tested by feedstock volatility: Recent price moves in aluminum hydroxide and bauxite have reduced upstream cost pressure in several regions. For procurement and commercial teams this creates a near-term margin window to renegotiate contracts, but the window is uneven by geography and product grade.
- Capacity upgrades are changing competitive dynamics: Several established producers have completed or are commissioning upgraded production lines targeted at high‑purity and hydrocracking-grade pseudoboehmite. These investments are altering the supply curve and raising the bar on product specification and reliability.
- Regulatory and ESG scrutiny is increasing: Environmental approvals, third-party audits and standards compliance are becoming baseline expectations for new capacity projects and major suppliers. Buyers and financiers will increasingly favor counterparties that can show consistent social and environmental governance.
What the report delivers — practical, decision-ready intelligence
PW Consulting’s report is designed as an operational toolkit for C-suite and commercial teams facing 2026 decisions. Key deliverables include:
Pseudoboehmite Market
- Granular market sizing (historical and forward-looking) and scenario-based forecasts that isolate volume, value and pricing impacts under alternative demand and input-cost regimes.
- Supply-side diagnostics: capacity maps, utilization estimates, project pipelines and a risk heatmap that flags probable bottlenecks and overhangs through 2032.
- Raw material and cost analysis linking aluminum hydroxide, alumina feedstock and bauxite price trajectories to finished pseudoboehmite margins and contract structures.
- Competitive benchmarking and capability matrices for incumbent and emerging producers, with tailored supplier scorecards for procurement negotiations.
- Commercial playbooks including product segmentation strategies, premiumization pathways for high‑purity grades, channel strategies for adsorbents versus catalyst carriers, and pricing levers in tight vs. soft markets.
- Scenario-based M&A and JV recommendations, including integration checklists and blueprints for brownfield upgrades vs. greenfield investment.
- Regulatory and ESG compliance templates to accelerate permitting, community engagement and certification for major capacity projects.
Supply-side and raw-material context
Recent input-cost trends are material to 2026 strategy. Aluminum hydroxide pricing in Northeast Asia softened materially in early 2026, while European spot levels also declined modestly, reflecting weaker downstream demand in certain polymer and flame‑retardant sectors and easing upstream alumina and bauxite feedstock costs. China CIF bauxite and U.S. import indices underscore that feedstock volatility remains a live risk — one that will influence regional margins and trade flows. Smart procurement teams will use short-term softness to secure multi-year terms with embedded flexibility, while capital planners should stress-test new capacity against both lower-cost and higher-cost feedstock scenarios.
Competitive landscape — structure, strengths and strategic implications
The market exhibits a moderate level of concentration, with the leading suppliers collectively accounting for a significant share of demand. A competitive field mixes global chemical majors, specialty alumina houses and regional producers focused on industrial and catalyst applications. Key archetypes include:
- Global specialty majors: Companies such as Honeywell UOP, BASF and Almatis bring deep process and application know‑how, enabling bundled offers into catalyst and adsorbent markets. Their strengths are technical support, global supply networks and established OEM relationships.
- Integrated alumina players: Firms like CHALCO and several Chinese producers leverage upstream alumina integration to pursue scale and cost competitiveness, while also investing in higher‑specification PHS lines aimed at hydrocracking and other demanding applications. Recent environmental approvals and third‑party audits for expanded lines illustrate a trend toward formalized ESG diligence on new capacity.
- Specialty innovators: Producers such as Sasol, Nabaltec and regional specialists focus on highly dispersed, high‑purity grades and tailored surface chemistries — segments where technical differentiation commands premium pricing.
- Smaller regional suppliers: Numerous mid‑tier and local players supply industrial grades into ceramics, refractories and polishing markets. These suppliers are often agile on pricing but face increasing certification and quality pressures from multinational buyers.
For buyers and investors, the strategic implication is clear: aligning with the right supplier archetype depends on whether priority is cost, technical partnership or speed-to-market on specialty grades.
Regulatory & ESG — a new baseline for investment
Regulatory scrutiny is no longer episodic. The recent environmental and social assessments, plus ISO certifications maintained by certain upgraded production projects, set a precedent for permitting, procurement and offtake in 2026. Financial and trade partners are increasingly conditioning access to capital on demonstrable ESG performance and traceable supply chains. Corporates planning capacity expansions must integrate environmental and human‑rights impact assessments into early-stage feasibility; buyers should include ESG clauses in long-term contracts.
Strategic recommendations for 2026 decision-makers
- Procurement: Lock in tiered contracts that blend spot exposure with multi-year volumes, include feedstock pass-through mechanics, and require supplier certification milestones to mitigate delivery and ESG risks.
- Product strategy: Invest selectively in high‑purity and specialty grades where technical differentiation yields sustainable premiums. For commoditized grades, pursue operational excellence to protect margins.
- Capex & partnerships: Prioritize modular brownfield upgrades and targeted JV models that shorten lead-times and share the burden of permitting and certification. Integrate environmental remediation and community engagement costs into the earliest capex models.
- M&A & portfolio moves: Use current market dynamics to evaluate tuck-in acquisitions that provide access to certified capacity, proprietary dispersions or downstream integration into catalyst manufacturing.
- Risk management: Model multiple feedstock scenarios and design hedging strategies around aluminum hydroxide and bauxite indices. Maintain supplier redundancy for critical grades.
Concluding perspective
The pseudoboehmite market entering 2026 is neither a niche curiosity nor a commodity commodity—rather, it sits at the intersection of performance chemistry, supply-chain complexity and rising ESG expectations. PW Consulting’s new report provides the quantitative backbone and the practical toolset leaders need to make defensible choices: where to source, when to invest, and how to capture premium growth pockets while managing raw-material and regulatory risk. With a projected mid-single-digit CAGR driving the market toward roughly USD 935 Million by 2032, the next 18 months will separate strategic winners who institutionalize supplier intelligence and technical differentiation from those reacting to price cycles.
Next steps
For procurement leaders, technology scouts and corporate strategists preparing 2026 budgets and capital plans, the full Pseudoboehmite Market Report contains the underlying data tables, regional supply-demand overlays, supplier scorecards and scenario models referenced here. To access the complete analysis, actionable appendices and firm-level profiles, please visit PW Consulting’s report page or contact our industrial materials practice for a briefing and tailored advisory engagement.
For detailed analysis of this topic, please visit the official page: Pseudoboehmite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com