

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Insight: C9 Petroleum Resin Market Poised to Grow at a 4.85% CAGR

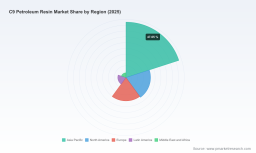
C9 Petroleum Resin Market — Strategic Preview for 2026: Why PW Consulting’s C9 Report Will Shape Your Next Move
PW Consulting’s newly completed C9 Petroleum Resin Market report (base year 2025; historical window 2020–2025; forecast horizon 2026–2032) offers a focused, decision-ready examination of a niche yet indispensable class of hydrocarbon resins. Our analysis quantifies the market’s trajectory and decodes the operational and strategic levers that will matter most to producers, downstream formulators, investors, and procurement teams as they set priorities for 2026 and beyond.
C9 Petroleum Resin Market
Executive snapshot
- The global C9 petroleum resin market demonstrated robust recovery and steady expansion through 2020–2025, moving from a mid‑single‑billion dollar base in 2020 to a substantially larger total by the 2025 base year (figures in USD Million).
- PW Consulting projects continued growth across the forecast window (2026–2032) at a compound annual growth rate (CAGR) of approximately 4.85%, reflecting steady downstream demand and selective capacity additions.
- By the end of the forecast horizon, total market value is expected to be materially higher than the 2025 baseline, underlining opportunities for margin recovery, portfolio premiumization, and strategic consolidation.
What the report contains — tactical, transaction-grade intelligence
- Granular market sizing and mid‑term forecasts (total market and breakouts by region, process type, and application) that support revenue planning and investment appraisals.
- Supply‑chain topology and feedstock mapping: origins of the C9 aromatic fraction, sensitivity to ethylene cracker feedstock choices, and scenarios for upstream availability through 2032.
- Price dynamics and margin modelling that link cracker economics, naphtha/ethane cycles, and resin plant operating strategies.
- Demand-side diagnostics across adhesives, coatings, printing inks, rubber compounding and other end‑use clusters — including buying patterns, technical specifications, and switching costs.
- Competitive landscaping with proprietary company profiles, capability matrices, and opportunity‑fit assessments for potential M&A, JV or greenfield investments.
- Regulatory and materials‑safety intelligence: practical implications of recent hazard assessments and reporting thresholds for industrial chemicals in key jurisdictions.
- Actionable strategic recommendations, investment scenarios and a risk dashboard designed for C‑suite use in 2026 budgeting and scenario planning.
Market snapshot & forecast — the big picture you need
Across the 2020–2025 period, the C9 petroleum resin market displayed resilience amid feedstock swings and downstream demand normalization. PW Consulting’s calibrated bottom‑up model shows a market that expanded significantly by the 2025 base year, and is projected to continue ascending through 2032 under a central case that assumes steady industrial growth and modest capacity additions. With a 2026–2032 CAGR of roughly 4.85%, the market offers predictable growth for differentiated products while remaining exposed to upstream volatility tied to ethylene cracker configurations and naphtha pricing.
C9 Petroleum Resin Market
For decision-makers, the immediate implication is clear: base‑case topline growth will not alone solve margin pressure. Competitive advantage will accrue to players who control feedstock optionality, extract product premia through formulation specificity (e.g., hydrogenated or crosslinkable grades), and embed supply resilience close to key end‑use clusters.
C9 Petroleum Resin Market
Key market dynamics shaping 2026 decisions
- Feedstock availability and cracker economics: The C9 aromatic fraction is a byproduct of steam cracking. A structural shift in cracker feedstock — notably toward ethane in some regions — reduces C9 byproduct yields and increases supply cyclicality. Procurement and asset‑siting decisions must be stress‑tested against these upstream scenarios.
- Downstream demand heterogeneity: Adhesives, coatings, inks and rubber compounds each value different resin attributes (tack, softening point, compatibility). Commercial strategies that segment customers by technical needs — not just volume — will capture higher margins.
- Product and process differentiation: Thermal vs catalytic polymerization and hydrogenation create distinct performance and cost profiles. Innovations such as crosslinkable hydrocarbon resins present premium pathways; manufacturers with proprietary process know‑how will command leverage.
- Pricing and margin volatility: Resin prices remain sensitive to feedstock swings. Buyers and sellers should incorporate dynamic hedging, flexible contract structures, and price‑escalation clauses linked to upstream indices.
- Regulatory context and material classification: Recent assessments affirm that many hydrocarbon resins are low‑hazard and qualify for certain reporting simplifications. While regulatory tailwinds reduce compliance cost in some markets, firms must still monitor classification changes and local labeling or disclosure norms.
Competitive landscape — implications for strategy and M&A
The C9 resin arena features a mix of integrated global players, regional specialists, and high‑volume capacity in select manufacturing hubs. Our competitive review highlights several archetypes and practical lessons:
- Integrated oil & chemical producers (feedstock control advantage): Companies that can internalize C9 feedstock via cracker operations have a structural cost edge and the ability to prioritize allocation to strategic downstream units. This integration influences pricing discipline and can create barriers for pure‑play resin traders.
- Regional champions and secure‑supply specialists: Established domestic producers — particularly those serving local industrial ecosystems — offer a value proposition centered on supply security and rapid technical support. This is a critical consideration for downstream formulators with Just‑in‑Time manufacturing footprints.
- Innovation‑led differentiators: Firms that commercialize novel resin chemistries (e.g., crosslinkable grades, tailored hydrogenated resins) can capture premium niches in high‑performance adhesives and coatings. Protecting IP and accelerating customer trials are priority actions for R&D‑led players.
- High‑volume manufacturers in Asia: Lower‑cost manufacturing bases and proximity to large downstream markets create scale advantages, but China‑based producers also face increasing scrutiny on quality consistency and environmental compliance — considerations that affect export prospects.
For 2026 planning, executives should treat portfolio decisions through the lenses of feedstock control, product differentiation, and geographic proximity. Options to explore include bolt‑on acquisitions to secure C9 feedstock, JVs with cracker operators, conversion of existing aromatics capacity to higher‑value specialty grades, or targeted investments in hydrogenation and catalytic process capabilities.
How to use PW Consulting’s report in your 2026 playbook
- Capex prioritization: Use our demand scenarios and feedstock sensitivity analysis to rank prospective investments — new plant capacity, debottlenecking, or process upgrades — by IRR under multiple cracker‑feedstock outlooks.
- Procurement and hedging: Implement procurement playbooks informed by our price‑modelling; consider long‑term supply contracts with indexation, or strategic inventory cushions in markets exposed to ethane conversion.
- Commercial strategy and product mix: Reallocate commercial focus toward higher‑margin specialty grades where customer switching costs are highest; deploy technical service teams to accelerate qualification cycles.
- M&A and partnership screening: Use our company profiles and capability matrices to identify targets and JV partners that would secure feedstock, add process know‑how, or expand access to premium end markets.
- Regulatory and ESG alignment: Leverage the report’s regulatory appendix to streamline compliance and to frame product stewardship narratives that resonate with industrial customers and procurement teams.
Methodology and assurance
PW Consulting’s findings are grounded in a hybrid methodology: bottom‑up plant and company production data, top‑down macro demand modelling, and primary interviews with producers, formulators and feedstock suppliers. We apply scenario analysis to stress‑test forecasts against alternative cracker feedstock mixes and feedstock price pathways. The result is a defensible, transaction‑grade view suitable for board‑level decision support, M&A diligence, and procurement strategy.
What we are deliberately not disclosing here (and why)
In keeping with the “trailer” principle of this release, we have intentionally withheld granular regional and application split tables, as well as cell‑level revenue forecasts and some proprietary competitive scores. These items are part of the full PW Consulting dataset and analytic output, which is designed for clients who require transaction‑quality modelling and confidential benchmarking. Releasing those line‑items publicly would dilute their strategic value to subscribing clients.
Final note — the strategic cliff‑edge for 2026
2026 represents an inflection point where upstream cracker strategies, midstream allocation practices, and downstream demand composition converge. While headline growth is steady, the real prize in the C9 resin market will go to organizations that convert market insight into structural advantage: securing feedstock optionality, scaling differentiated chemistries, and forging commercial linkages with the most profitable downstream segments. PW Consulting’s C9 Petroleum Resin Market report equips executives with the scenarios, supplier intelligence, and operational playbooks to make those decisions with confidence.
For access to the full dataset, detailed regional and application splits, proprietary company scorecards and the complete suite of strategic recommendations, visit PW Consulting’s report page or contact our industrials team to arrange a briefing and data licence.
For detailed analysis of this topic, please visit the official page: C9 Petroleum Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com