

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cochloroether Rubber Eco Market to Grow at 4.51% CAGR as Asia Pacific Leads with USD 297.96 Million Share

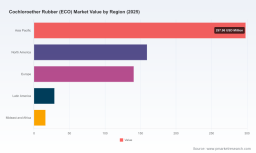
Cochloroether Rubber (ECO) Market — Strategic Outlook for 2026: Key Implications from PW Consulting’s New Market Report
PW Consulting’s latest Cochloroether Rubber (ECO) Market study is issued with a clear remit: help executives convert market intelligence into defensible 2026 strategies. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the report synthesizes demand drivers, supply dynamics, cost structures, and competitive positioning that will determine which firms capture value as the market evolves. At the macro level, the industry is expanding steadily — the market grew from approximately USD 515 million in 2020 to roughly USD 642 million in 2025 and is projected to approach USD 875 million by 2032, reflecting a 4.51% CAGR across the forecast period. That trajectory underpins planning choices across procurement, product, and M&A agendas for 2026.
Cochloroether Rubber Eco Market
Why 2026 is a Strategic Inflection Point
-
Demand stabilization meets supply transformation. After a recovery phase through 2023–2025, incremental demand for ECO in automotive seals, industrial gasketing, and specialty rolls is now intersecting with meaningful upstream capacity changes. New epichlorohydrin capacity additions in 2024 and 2025 and an industry-wide shift toward glycerol- and bio-based feedstocks are altering marginal cost curves and sourcing risk profiles.
Cochloroether Rubber Eco Market -
Consolidation and supplier concentration are shaping commercial dynamics. Industry concentration metrics indicate a market with substantial share controlled by a narrow set of global suppliers — a structural condition that affects pricing power, contract terms, and speed of innovation adoption.
Cochloroether Rubber Eco Market -
Regulatory and sustainability vectors are accelerating product re-specification. The move by compounders to ETU-free and lead-free curing systems and the advance of bio-based epichlorohydrin production routes mean OEM specifications will increasingly include lifecycle and hazard parameters as pass/fail attributes rather than optional differentiators.
What the Report Delivers — Practical, Executable Intelligence
PW Consulting designed the report for use by commercial leaders, procurement teams, R&D heads, and corporate development groups. Deliverables are operational and include:
-
Market sizing and demand scenarios calibrated to 2026 planning cycles, with bottom-up and top-down crosschecks aligned to real-world shipments and end-market activity.
-
Cost-model templates that isolate feedstock, energy, conversion, and logistics components to quantify pass-through exposure to epichlorohydrin price moves and regional freight differentials.
-
Supplier scorecards and risk heatmaps covering manufacturing footprint, product breadth (homopolymer / copolymer / terpolymer families), quality certifications, and commercial flexibility.
-
Regulatory and compliance matrices that map chemical hazards, curing-system constraints, and emerging test protocols relevant to automotive and industrial spec writers.
-
Go-to-market playbooks for incumbents and entrants — from premium-grade product segmentation to low-cost regional supply strategies — with negotiation scripts for long-term off-take and tolling arrangements.
-
M&A and investment screening tools: capex sizing for greenfield polymer compounding, payback sensitivity to feedstock price volatility, and acquisition target prioritization criteria.
Importantly, the report pairs qualitative supplier insight with an interactive model so teams can stress-test strategies under demand shocks, raw-material squeezes, or accelerated electrification scenarios.
Supply-Side Dynamics: Epichlorohydrin, Capacity Additions, and the Bio-Shift
Epichlorohydrin remains the primary upstream feedstock for ECO production, and its market structure is a meaningful determinant of downstream cost and availability. Global epichlorohydrin production capacity reached multi-million-ton scale in 2025 with production rates materially below nameplate capacity — a delta that has compelled some suppliers to prioritize high-margin contractual customers during tight periods. Notably, 2024–2025 saw several new capacity additions with a pronounced emphasis on glycerol-based, lower-carbon production routes. These additions are reshaping the marginal cost curve and creating new arbitrage opportunities for buyers who can source bio-based feedstock or negotiate linked pricing mechanisms.
For procurement teams, the practical implications are twofold: first, hedging and long-term off-takes must be structured around feedstock pathway economics (conventional vs. bio-based), and second, supply continuity plans should incorporate alternative chemistry or compounder partners capable of rapid qualification.
Competitive Landscape: What the Leading Players Signal
The market exhibits a high degree of supplier concentration, with the top three firms accounting for a majority share and the top five controlling a substantial portion of global volume. This concentration (CR3 ~62.3%; CR5 ~78.45%) results in asymmetric bargaining power that manifests through price announcements, allocation policies, and technical partnership access.
-
Integrated Japanese producers: Established Japanese firms operate integrated value chains from epichlorohydrin monomer through finished ECO grades, enabling quality control and margin protection. Their product breadth — homopolymers, copolymers, and terpolymers — and long production histories make them preferred partners for high-spec automotive OEMs.
-
US capacity emphasis: Suppliers with US manufacturing positions highlight proximity advantage for North American OEM programs and regulatory alignment for critical applications such as fuel-system components.
-
Specialist compounders and formulators: Smaller, regional suppliers focus on application-specific compounds (e.g., high-durometer grades to meet ASTM classifications) and regulatory-compliant curing systems (ETU-free, lead-free) — features increasingly demanded by automotive and industrial purchasers.
Recent commercial signals—such as supplier-led price increases in mid-2024—underscore a landscape where capacity utilization, feedstock price pass-through, and contractual rigidity can rapidly shift margin outcomes for OEMs and tier suppliers. For buyers, the lesson is clear: price movements are not purely transient; they reflect embedded structural positions that require contractual and technical mitigation.
Strategic Priorities for 2026
-
Integrate feedstock pathway risk into product roadmaps: Distinguish formulations that are feedstock-agnostic from those that are not. Prioritize R&D that enables substitution to bio-based epichlorohydrin where lifecycle or regulatory pressures make this a procurement preference.
-
Secure layered supply contracts: Combine medium-term fixed-volume agreements with spot flexibility and call options to balance cost control and agility. Include explicit pass-through and indexing clauses tied to epichlorohydrin and energy baskets.
-
Invest in qualification velocity: Reduce lead time to approve alternate compounders by establishing standardized test protocols and accelerated aging pilots that align with OEM validation cycles.
-
Prioritize regulatory-compliant chemistries: Move away from hazardous curing systems where feasible; ETU- and lead-free offerings are becoming table stakes in many automotive programs.
-
Consider selective vertical integration or tolling partnerships: For manufacturers with scale, securing tolling capacity or partial upstream integration can offer meaningful protection against allocation risks and sudden price moves.
How PW Consulting’s Report Supports 2026 Decisions
Executives need analysis they can operationalize in months, not years. PW Consulting’s report supplies that bridge by combining market forecasting, supplier benchmarking, and executable playbooks. Key outputs designed for immediate use in 2026 planning cycles include:
-
Negotiation-ready supplier scorecards and term sheets tailored to different volume tiers and application criticality.
-
Scenario-based P&L impact calculators that show profit sensitivity to feedstock moves and allocation events.
-
Manufacturing readiness and qualification checklists that compress supplier onboarding timelines.
-
M&A “heat map” identifying segments and geographies where bolt-on acquisitions or strategic minority investments deliver quick access to new grades or regulatory-compliant compounding technologies.
On Transparency and Where to Find the Full Intelligence
In keeping with the “trailer” approach to strategic disclosure, this release emphasizes the insights and recommendations most immediately useful to senior decision-makers while deliberately withholding certain granular segmentation tables and specific regional/application breakdowns. Those detailed segmentations, including supplier-level volume histories, application-by-application forecasts, and confidential price and margin profiles, are bundled in the full PW Consulting report and interactive model.
For commercial teams planning 2026 sourcing cycles, product leaders refining grade roadmaps, or corporate development teams seeking targeted acquisition opportunities, the full report and model provide the necessary granularity and forensic supplier detail to execute with confidence.
Closing — A Practical Roadmap into 2026
The Cochloroether Rubber market is maturing into a structurally different industry than it was five years ago. Steady end-market demand, upstream capacity additions (including bio-based routes), and concentrated supplier power combine to make 2026 a planning year where choices about supply contracts, technical partnerships, and regulatory positioning will determine competitive advantage. PW Consulting’s report converts those market realities into executable strategies, allowing organizations to protect margin, accelerate qualification cycles, and selectively invest where the economics are most compelling.
To access the full report, the interactive forecast model, and supplier annexes required to implement these recommendations, please visit PW Consulting’s Cochloroether Rubber Market research page or contact our advisory team for a guided briefing.
For detailed analysis of this topic, please visit the official page: Cochloroether Rubber Eco Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com