

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Pseudoboehmite Market Poised to Grow at a 5.22% CAGR Through 2032

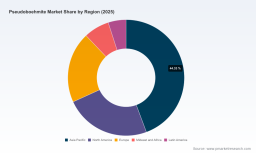
Pseudoboehmite Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
As global supply chains recalibrate and catalyst-driven value chains pursue higher performance with lower environmental footprints, pseudoboehmite has re-emerged as a strategic material for petrochemical catalysts, adsorbents, advanced ceramics and specialty applications. PW Consulting’s latest Pseudoboehmite Market report — covering 2020–2025 historical performance and a 2026–2032 forecast — synthesizes macro drivers, supplier economics and go-to-market playbooks that will determine winners and losers through 2026 and beyond.
Pseudoboehmite Market
Headline market view: steady recovery, structural opportunity
Our base-year assessment shows the pseudoboehmite market expanding from a mid-single‑hundred million USD base in 2020 to an estimated USD 654.6 Million in 2025, reflecting recovery from cyclic pressures and investments in higher-purity product lines. Under our central forecast the market is projected to grow at a compound annual growth rate (CAGR) of approximately 5.22% across 2026–2032, reaching roughly USD 935 Million by 2032. That trajectory captures both cyclical demand for refinery and petrochemical catalysts and medium-term secular shifts driven by stricter performance and environmental specifications across multiple end markets.
Pseudoboehmite Market
Why 2026 is pivotal for corporate strategy
- Margins are being re-tested by feedstock volatility: Recent price moves in aluminum hydroxide and bauxite have reduced upstream cost pressure in several regions. For procurement and commercial teams this creates a near-term margin window to renegotiate contracts, but the window is uneven by geography and product grade.
- Capacity upgrades are changing competitive dynamics: Several established producers have completed or are commissioning upgraded production lines targeted at high‑purity and hydrocracking-grade pseudoboehmite. These investments are altering the supply curve and raising the bar on product specification and reliability.
- Regulatory and ESG scrutiny is increasing: Environmental approvals, third-party audits and standards compliance are becoming baseline expectations for new capacity projects and major suppliers. Buyers and financiers will increasingly favor counterparties that can show consistent social and environmental governance.
What the report delivers — practical, decision-ready intelligence
PW Consulting’s report is designed as an operational toolkit for C-suite and commercial teams facing 2026 decisions. Key deliverables include:
Pseudoboehmite Market
- Granular market sizing (historical and forward-looking) and scenario-based forecasts that isolate volume, value and pricing impacts under alternative demand and input-cost regimes.
- Supply-side diagnostics: capacity maps, utilization estimates, project pipelines and a risk heatmap that flags probable bottlenecks and overhangs through 2032.
- Raw material and cost analysis linking aluminum hydroxide, alumina feedstock and bauxite price trajectories to finished pseudoboehmite margins and contract structures.
- Competitive benchmarking and capability matrices for incumbent and emerging producers, with tailored supplier scorecards for procurement negotiations.
- Commercial playbooks including product segmentation strategies, premiumization pathways for high‑purity grades, channel strategies for adsorbents versus catalyst carriers, and pricing levers in tight vs. soft markets.
- Scenario-based M&A and JV recommendations, including integration checklists and blueprints for brownfield upgrades vs. greenfield investment.
- Regulatory and ESG compliance templates to accelerate permitting, community engagement and certification for major capacity projects.
Supply-side and raw-material context
Recent input-cost trends are material to 2026 strategy. Aluminum hydroxide pricing in Northeast Asia softened materially in early 2026, while European spot levels also declined modestly, reflecting weaker downstream demand in certain polymer and flame‑retardant sectors and easing upstream alumina and bauxite feedstock costs. China CIF bauxite and U.S. import indices underscore that feedstock volatility remains a live risk — one that will influence regional margins and trade flows. Smart procurement teams will use short-term softness to secure multi-year terms with embedded flexibility, while capital planners should stress-test new capacity against both lower-cost and higher-cost feedstock scenarios.
Competitive landscape — structure, strengths and strategic implications
The market exhibits a moderate level of concentration, with the leading suppliers collectively accounting for a significant share of demand. A competitive field mixes global chemical majors, specialty alumina houses and regional producers focused on industrial and catalyst applications. Key archetypes include:
- Global specialty majors: Companies such as Honeywell UOP, BASF and Almatis bring deep process and application know‑how, enabling bundled offers into catalyst and adsorbent markets. Their strengths are technical support, global supply networks and established OEM relationships.
- Integrated alumina players: Firms like CHALCO and several Chinese producers leverage upstream alumina integration to pursue scale and cost competitiveness, while also investing in higher‑specification PHS lines aimed at hydrocracking and other demanding applications. Recent environmental approvals and third‑party audits for expanded lines illustrate a trend toward formalized ESG diligence on new capacity.
- Specialty innovators: Producers such as Sasol, Nabaltec and regional specialists focus on highly dispersed, high‑purity grades and tailored surface chemistries — segments where technical differentiation commands premium pricing.
- Smaller regional suppliers: Numerous mid‑tier and local players supply industrial grades into ceramics, refractories and polishing markets. These suppliers are often agile on pricing but face increasing certification and quality pressures from multinational buyers.
For buyers and investors, the strategic implication is clear: aligning with the right supplier archetype depends on whether priority is cost, technical partnership or speed-to-market on specialty grades.
Regulatory & ESG — a new baseline for investment
Regulatory scrutiny is no longer episodic. The recent environmental and social assessments, plus ISO certifications maintained by certain upgraded production projects, set a precedent for permitting, procurement and offtake in 2026. Financial and trade partners are increasingly conditioning access to capital on demonstrable ESG performance and traceable supply chains. Corporates planning capacity expansions must integrate environmental and human‑rights impact assessments into early-stage feasibility; buyers should include ESG clauses in long-term contracts.
Strategic recommendations for 2026 decision-makers
- Procurement: Lock in tiered contracts that blend spot exposure with multi-year volumes, include feedstock pass-through mechanics, and require supplier certification milestones to mitigate delivery and ESG risks.
- Product strategy: Invest selectively in high‑purity and specialty grades where technical differentiation yields sustainable premiums. For commoditized grades, pursue operational excellence to protect margins.
- Capex & partnerships: Prioritize modular brownfield upgrades and targeted JV models that shorten lead-times and share the burden of permitting and certification. Integrate environmental remediation and community engagement costs into the earliest capex models.
- M&A & portfolio moves: Use current market dynamics to evaluate tuck-in acquisitions that provide access to certified capacity, proprietary dispersions or downstream integration into catalyst manufacturing.
- Risk management: Model multiple feedstock scenarios and design hedging strategies around aluminum hydroxide and bauxite indices. Maintain supplier redundancy for critical grades.
Concluding perspective
The pseudoboehmite market entering 2026 is neither a niche curiosity nor a commodity commodity—rather, it sits at the intersection of performance chemistry, supply-chain complexity and rising ESG expectations. PW Consulting’s new report provides the quantitative backbone and the practical toolset leaders need to make defensible choices: where to source, when to invest, and how to capture premium growth pockets while managing raw-material and regulatory risk. With a projected mid-single-digit CAGR driving the market toward roughly USD 935 Million by 2032, the next 18 months will separate strategic winners who institutionalize supplier intelligence and technical differentiation from those reacting to price cycles.
Next steps
For procurement leaders, technology scouts and corporate strategists preparing 2026 budgets and capital plans, the full Pseudoboehmite Market Report contains the underlying data tables, regional supply-demand overlays, supplier scorecards and scenario models referenced here. To access the complete analysis, actionable appendices and firm-level profiles, please visit PW Consulting’s report page or contact our industrial materials practice for a briefing and tailored advisory engagement.
For detailed analysis of this topic, please visit the official page: Pseudoboehmite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com