

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Commercial Small Batteries Market Poised for 6.79% CAGR Through 2032

Commercial Small Batteries Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
As organizations plan capital allocation and product-roadmap decisions for 2026, the commercial small batteries market stands out as a resilient, mid-single-digit growth sector with clear structural drivers and emerging points of disruption. PW Consulting’s forthcoming market research report — based on a 2020–2025 historical analysis and a 2026–2032 forecast horizon — synthesizes financial trajectory, competitive positioning, regulatory risk, and strategic playbooks that senior leaders will need to act confidently in the coming 12–18 months.
Commercial Small Batteries Market
Market Trajectory: The Big Picture
The commercial small batteries market has expanded steadily over the past five years, with measured acceleration into 2024–2025. From the base year (2025) used in our modelling, the market is projected to continue growing through 2032 at a compound annual growth rate (CAGR) of 6.79%. That rate reflects a combination of steady demand from healthcare devices, industrial IoT, retail systems and security applications, alongside replacement cycles and new design wins for commercial electronics.
Commercial Small Batteries Market
To contextualize the trajectory: the market has moved meaningfully higher since 2020 and is forecast to reach a materially larger size by the end of our forecast period in 2032. That expansion, combined with concentrated pockets of supplier strength, creates both opportunities and tactical risks for procurement, product, and M&A teams.
Commercial Small Batteries Market
Why This Matters for 2026 Decision Cycles
-
Capital allocation and sourcing strategies must incorporate both steady demand and episodic shocks. The forecasted mid‑single‑digit CAGR validates continued investment in small battery-enabled product platforms, but the detailed scenarios in our report show that margin sensitivity to input-cost swings is non-linear—requiring hedged supplier strategies and staged capital commitments.
-
Product teams need to accelerate safety-by-design and regulatory alignment. New and updated standards addressing ingestion risks and chemical restrictions are moving from guidance into enforceable practice; early conformity reduces time-to-market friction for new commercial devices.
-
M&A and partnership activity should be informed by concentration dynamics. A market with meaningful share concentration at the top creates attractive carve‑out opportunities for mid-market buyers and offers dominant suppliers leverage in channel negotiations; our competitive scorecards identify where value pools are most accessible.
Report Highlights: What Practitioners Will Find Inside
-
Actionable demand scenarios: deterministic and probabilistic forward scenarios through 2032 calibrated to macro‑adoption curves, device bill-of-material trends, and replacement cycles. Each scenario estimates topline implications while preserving the granularity clients need to stress-test portfolios (note: proprietary subsegment tables are available in the full report).
-
Cost-sensitivity and input-risk modelling: interactive dashboards that quantify margin exposure to raw-material price swings (including lithium carbonate volatility) and freight/logistics dynamics, with prescriptive sourcing playbooks for tiered procurement.
-
Regulatory and safety compliance playbooks: checklists and design‑control templates aligned to recent standards and regulations — including ingestion-safety testing norms and extended producer responsibility frameworks — to reduce compliance-related delays and recalls.
-
Commercial go-to-market frameworks: tailored channel and pricing strategies for commercial OEMs, medical device manufacturers, and system integrators to improve adoption rates and margin capture in regulated environments.
-
Competitive intelligence modules: vendor scorecards, supplier risk matrices, and M&A screening tools that combine primary interviews, patent activity mapping, and public financials to identify partnership and acquisition targets.
Competitive Landscape — Where Power and Exposure Converge
The small batteries market comprises legacy household brands, specialized component manufacturers, and suppliers focused on backup and industrial power. Market concentration is meaningful at the top: our analysis shows that the three largest vendors control a substantial share of the market, with the top five accounting for nearly 59% — a structural reality that informs pricing dynamics, channel power, and innovation pipelines.
Key industry participants analyzed in the report include established consumer and industrial brands that offer complementary strengths:
-
Energizer Holdings — breadth across alkaline, lithium, and coin cells with deep retail reach; strengths in branded volume and broad channel partnerships.
-
Duracell Inc. — consumer-recognized safety innovations and rechargeable options; recent product-level safety work underscores its emphasis on packaging and child-safety design features.
-
Panasonic Corporation and other global component manufacturers — diversified chemistries and industrial relationships that support integrated OEM supply to commercial electronics and medical devices.
-
VARTA, Maxell, GP Batteries, Murata, Renata — niche and specialty players with leadership in micro and button cells for precision applications, often competing on quality, regulatory compliance, and application-specific support.
-
EnerSys, GS Yuasa, Power-Sonic — suppliers focused on sealed lead-acid (SLA/VRLA) and small-format backup solutions for UPS, standby, and industrial use-cases.
Our competitive analysis goes beyond product catalogues to assess R&D pipelines, safety-certification commitments, channel strategies, and manufacturing footprint resilience. For senior leaders planning supply agreements or considering vertical integration, the report provides relative scoring across these vectors and recommended negotiation playbooks tailored to supplier archetypes.
Regulatory, Safety and Raw Material Dynamics — Near-Term Risks
Three external forces will disproportionately influence 2026 outcomes:
-
Regulatory tightening: The EU’s battery framework and evolving international safety standards are shifting compliance from optional to table stakes. Specific labeling rules and extended producer responsibility mechanisms are already affecting product design and total landed costs for commercial devices.
-
Safety standards and design obligations: New and updated standards focused on button/coin cell ingestion and physiological hazards require changes in packaging, device enclosures, and public-facing warnings — changes that product teams must incorporate early to avoid redesign cycles at scale.
-
Raw material volatility: Price swings in battery-grade feedstocks such as lithium carbonate materially impact unit economics for lithium-based small batteries. Our scenario modelling quantifies margin stress points and provides hedging and supplier-mix recommendations that can be implemented within procurement cycles for 2026.
Recent Industry Signals
-
Product and portfolio moves: New market entrants and incumbents are expanding into finer-format battery types to capture stable commercial demand flows — moves that can reshape supplier competition in adjacent categories.
-
Trade-show and innovation clustering: Industry trade events in 2025 and early 2026 showcased incremental but important advances in cell chemistry, packaging for safety, and integration methods for IoT endpoints — suggesting near-term product refresh cycles for commercial OEMs.
-
Safety-focused launches: Recent product innovations targeting child-safety and ingestion-risk mitigation illustrate how manufacturers are translating regulation and public concern into product differentiation — reinforcing the point that compliance can be a competitive asset.
Strategic Playbook for 2026
-
Embed regulatory compliance into product roadmaps: Treat new and updated standards as design constraints rather than after-market fixes; prioritize packaging and ingestion-mitigation technologies that reduce certification timelines.
-
Use procurement as a strategic lever: Implement multi-supplier sourcing with capacity options, index-linked pricing clauses for volatile feedstocks, and joint-development agreements to secure preferred pricing for key chemistries.
-
Prioritize modular design for serviceability: For devices deployed in high-service environments (medical, security, retail), optimize for battery-swap procedures and certified replacements to reduce lifecycle cost and liability.
-
Consider targeted partnerships and tuck-ins: Where concentration enables, explore alliances with specialty cell manufacturers to access differentiated chemistries or safety-enabled packaging technologies.
About the Report and Next Steps
PW Consulting’s full Commercial Small Batteries Market report combines quantitative forecasts, supplier and product maps, regulatory trackers, and executable templates designed for commercialization, procurement, and M&A teams. The preview you’ve read outlines the strategic implications and topline market trajectory — the full release contains the empirical datasets, vendor scorecards, and scenario-model templates that informed these insights.
For decision-makers who will set budgets, negotiate supplier agreements, or approve product launches in 2026, the report is structured to shorten time-to-decision: it translates market trajectories and regulatory signals into prioritized actions, mapped to implementation timelines and expected ROI.
How to Access Full Intelligence
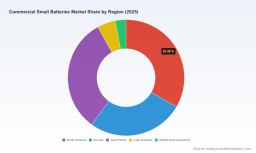
This press preview follows a “trailer” principle: it demonstrates the analytic depth of our work and highlights the operational value for 2026 planning while intentionally omitting proprietary subsegment tables and granular regional/application splits. To obtain the complete dataset, vendor-level dashboards, and downloadable scenario workbooks, please refer to the PW Consulting release page for the Commercial Small Batteries Market report.
Our team is available to conduct executive briefings, tailored deep-dives, and supplier negotiation workshops based on the report’s findings—supporting fast, evidence-based decisions for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Commercial Small Batteries Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com