

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Pseudoboehmite Market Set to Expand at 5.22% CAGR, Surpassing USD 934.74 Million by 2032

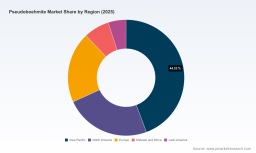
Pseudoboehmite Market — Strategic Brief for 2026 Decision Makers
Executive snapshot
PW Consulting’s latest market study on pseudoboehmite frames a market that has materially expanded over the past half-decade and is set for steady, structurally driven growth through the next planning cycle. Using 2025 as the base year, the market stood at USD 654.64 Million and — under our central-case assumptions — will expand at a compound annual growth rate (CAGR) of 5.22% across the 2026–2032 forecast window, reaching roughly USD 934.74 Million by 2032. Between 2020 and 2025 the market demonstrated resilience, growing from the low hundreds of millions to the current base, and the profile of demand is shifting toward higher-performance grades and more complex value chains.
Pseudoboehmite Market
Why this matters for 2026 strategic planning
Pseudoboehmite is a material enabler for high-value applications (notably catalyst carriers, adsorbents, and advanced speciality materials). For companies that rely on process catalysts, adsorbent media, or engineered alumina products, the market’s trajectory has direct implications for plant economics, product roadmaps, and procurement strategies. The 5.22% CAGR masks a more nuanced reality: growth is concentrated in applications that demand higher-purity and engineered microstructures, while legacy, commodity-grade demand is more exposed to cyclical end-markets.
Pseudoboehmite Market
Market dynamics and supply‑side considerations
- Demand composition is evolving. Advances in hydrocracking, emissions mitigation, and adsorbent formulations are increasing demand for high-dispersity and high-purity pseudoboehmite grades. End-user engineers increasingly specify narrow material property windows (surface area profiles, pore structure, impurity ceilings), which elevates the value of supplier technical services.
- Feedstock and cost pass‑through. Input costs for alumina precursors and upstream bauxite regimes are exerting pressure on producer margins, but regional differences in feedstock access and logistics mean localized cost dynamics are increasingly relevant to sourcing decisions. In short: feedstock volatility matters, but its impact is mediated by a supplier’s access to captive alumina/aluminum hydroxide, scale, and hedging policies.
- Regulatory and sustainability drivers. Environmental and social governance (ESG) factors are now a procurement filter in many of the large refiners and chemical majors. Producers that can demonstrate certified supply chains, environmental assessments, and occupational health standards capture an increasingly large share of new-specification business.
- Technology and grade differentiation. Performance differentiation — not just price — is becoming the decisive procurement variable in many hydroprocessing and adsorbent applications. Suppliers that combine material science expertise with reliable scale-up pathways command premium positioning.
Competitive landscape: who matters and why
The industry remains characterized by a mix of global technology-oriented suppliers, large integrated mineral players, and regional specialty producers. The competitive map matters because suppliers differ along four strategic axes: technological differentiation, scale/capacity, regional footprint, and ESG/compliance credentials.
Pseudoboehmite Market
- Sasol Limited — A technology-driven supplier with strong capabilities in producing highly dispersed, high-purity pseudoboehmite (including established product families). Sasol’s processes and brand recognition in catalyst carrier applications make it a go‑to partner for refiners seeking performance predictability.
- CHALCO / Chalco Shandong Advanced Material — A large-volume producer that has moved aggressively to upgrade capacity for hydrocracking-grade pseudoboehmite. The company’s recent major project approvals and certification activity have signaled a strategic shift toward higher-end refinery applications and an emphasis on audited sustainability credentials.
- Honeywell UOP — Offers branded alumina families that serve both catalyst intermediates and adsorbents; Honeywell’s end-user relationships in refining and petrochemicals provide downstream pull-through for new material specifications.
- Nabaltec AG, Almatis, BASF SE — Positioned as premium suppliers with niche specialities: flame retardant formulations, specialty catalysis, and advanced materials. These firms compete on formulation expertise, consistent quality, and technical support.
- Regional Chinese players and smaller specialists — Several mid-sized Chinese producers and niche firms supply tailored pseudoboehmite variants for local industrial markets and for global customers seeking cost-competitive alternatives. Their strategic relevance is growing where proximity, price, or bespoke product formats matter.
Notably, Chalco Shandong’s move to commission and certify upgraded production lines for hydrocracking applications — including the environmental and social assessments associated with large-capex projects — exemplifies the dual commercial and compliance investment path that incumbent producers are now walking.
Implications for supply risk and procurement
- Supplier selection is multi-dimensional. Price alone will not secure long-term feedstock reliability or product conformity for high-end applications. Procurement must incorporate technical qualification cycles, on-site audits, and contractual SLA mechanisms tied to material performance.
- Diversify by capability, not only by geography. A portfolio approach that spans a technology‑focused global supplier, a high-volume regional producer, and at least one specialty independent will mitigate operational and specification risks.
- Lock in innovation through strategic partnerships. Co-development agreements (R&D collaborations, pilot-run commitments, toll-processing) are effective levers to secure preferential access to advanced grades and to accelerate qualification timelines.
- Sustainability clauses are table stakes. Buyers should integrate upstream audit requirements and supplier remediation roadmaps into RFPs to avoid downstream supply interruptions tied to regulatory or reputational incidents.
Recommended strategic moves for 2026
For corporate leaders scheduling capital allocation and sourcing decisions this year, PW Consulting recommends a three‑tiered action plan that balances defensive and offensive moves.
- Immediate (0–12 months)
- Conduct supplier stress-tests: scenario-run supplier capacity, delivery, and quality resilience under feedstock shock and regulatory tightening.
- Initiate technical qualification with at least two alternative suppliers for critical grades, with explicit performance acceptance criteria and failure remediation pathways.
- Include ESG audit requirements as a mandatory component of procurement contracts for new supply lines.
- Medium (12–36 months)
- Evaluate backward integration or long-term off-take agreements with primary alumina/hydroxide suppliers where margin capture and security of feedstock matter.
- Pursue selective co‑development agreements with a technology partner to secure preferential access to next‑generation pseudoboehmite formulations.
- Consider bolt-on acquisitions or JV structures to secure regional manufacturing footprints where market access bottlenecks or trade frictions exist.
- Organizational
- Build an internal material science assessment cell to reduce time-to-qualify for new grades and to better translate lab metrics into operational guarantees.
- Create cross-functional CAPEX decision frameworks that capture long-term feedstock scenarios, regulatory risk premiums, and carbon/ESG impacts.
What PW Consulting’s full report delivers (high level)
We designed the Pseudoboehmite Market report to be an operational playbook for commercial, procurement, and corporate development teams. Key deliverables include:
- Proprietary demand-sensing model covering 2020–2032 with scenario-paths and sensitivity to feedstock, regulation, and technology adoption.
- Supplier benchmarking and scorecards that evaluate technology, capacity, compliance, and delivery risk.
- Price and margin scenario analysis and an operator-focused CAPEX/OPEX model for greenfield and retrofit lines.
- Supply‑chain risk heatmaps, including logistics and single‑source exposure matrices.
- M&A and partnership playbook: target screening criteria, valuation moats, and a commercial due diligence checklist for buyers and investors.
- Procurement negotiation templates including technical acceptance criteria, SLA language, and ESG audit clauses.
To preserve actionable advantage for subscribers, the report’s full segmentation tables, supplier market shares, and unit-cost schedules are available in the complete release. This executive brief highlights the strategic takeaways while reserving the granular intelligence for the full deliverable.
Closing perspective
As the pseudoboehmite market matures, the winners will be companies that combine materials expertise with robust supply-chain constructs and demonstrable sustainability credentials. The underlying market story is one of steady growth underpinned by structural adoption in higher-value applications — a dynamic that rewards proactive partnering, disciplined procurement, and targeted capital deployment. PW Consulting’s full market study equips decision-makers with the models, supplier intelligence, and transaction playbooks needed to act confidently in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Pseudoboehmite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com