

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Palm Kernel Shells Biomass Market Set to Surge at an 8.5% CAGR to Reach USD 2,318.9 Million by 2032

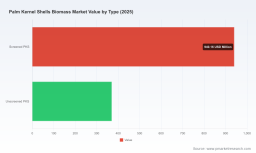
Palm Kernel Shells Biomass Market — Strategic Imperatives for 2026
As global decarbonisation accelerates and thermal generation portfolios are restructured, palm kernel shells (PKS) have emerged from the palm-oil value chain as a strategically important biomass feedstock. PW Consulting’s latest Palm Kernel Shells Biomass Market report (base year 2025) frames the PKS opportunity with a rigorous, forward-looking lens: the market was worth roughly USD 1.31 billion in 2025 and our demand-supply model projects an 8.5% compounded annual growth rate through the forecast window, reaching institutional-scale market sizes by the early 2030s. For decision-makers planning 2026 roadmaps, the report converts this macro momentum into operational actions, risk maps and investment-ready scenarios — while reserving the granular cell-level datasets and company-level volume tables for the full report.
Palm Kernel Shells Biomass Market
Why 2026 Is an Inflection Year
-
Policy and procurement are aligning. A suite of sustainability-driven procurement filters—most visibly certification regimes required for export markets—has shifted buyer behaviour toward traceable, certified PKS. This is changing offtake dynamics and elevating premiums for compliant supply chains.
Palm Kernel Shells Biomass Market -
Supply-side restructuring is underway. Processing capacity additions, plant rationalisations and the emergence of dedicated PKS aggregators have made feedstock availability more market-responsive, but not uniformly so across trading corridors. Logistics chokepoints (port capacity, seasonal vessel availability and inland trucking) remain decisive cost drivers.
Palm Kernel Shells Biomass Market -
Commercial concentration sits in a middle band: the sector is not hyper-consolidated, but neither is it atomised. The competitive geometry leaves room for scale players to secure advantage through integrated supply chains, and for nimble intermediaries to capture margins through logistics and quality arbitrage.
-
Price and risk transmission are intensifying. Macroeconomic variables—including palm oil reference pricing, local export levies and currency movements—feed quickly into PKS export economics. Buyers and producers face several months of lagged, but material, pricing effects as these variables evolve.
What the Report Delivers — Practical, Transaction-Ready Intelligence
The PW Consulting report is built for commercial teams, buyers, asset owners and investors who must convert sector momentum into defensible decisions. Key deliverables include:
-
Proprietary market sizing and a reconciled demand-supply model covering historical 2020–2025 dynamics and forward projections across the 2026–2032 forecast window (methodology, input assumptions and sensitivity runs included).
-
Price-driver decomposition that isolates origin fundamentals, logistics cost components and sustainability-premium mechanics — and translates these into forward price envelopes under alternative macro scenarios.
-
Regulatory and certification matrix connecting country-level export measures, sustainability standards and buyer compliance requirements to offtake and insurance considerations.
-
Operational playbooks for procurement and inbound logistics — tender templates, quality specs and sample contract clauses calibrated to typical PKS grading (net calorific values, ash and moisture specifications) and international shipping practices.
-
Supplier benchmarking and a competitive landscape module: company profiles, capability heatmaps, processing footprints and capacity-change trackers. (Note: granular company volumes and regional/applications splits are only available in the full report.)
-
Transaction support tools: valuation checklists for acquisition targets, due-diligence scorecards for offtake counterparties, and scenario-based investment cases for processing plants and port-side logistics hubs.
Competitive Dynamics — Who Matters and Why
The market ecology is shaped by three archetype players: certified export-focused processors, regional aggregators with buyer linkages, and diversified palm-oil groups that monetise residues as energy feedstock. Leading examples illustrate these roles:
-
Export-focused processors who emphasise certified, traceable product and have expanded processing capacity to serve demanding buyers. Their advantage: faster market access to sustainability-conscious buyers and the ability to capture contract premiums.
-
Regional trading houses and industrial buyers that combine long-term supplier relationships with flexible delivery nodes across Southeast Asia. Their advantage: lower logistical friction and the ability to tailor delivery schedules to utility ramp profiles.
-
Integrated plantation and milling groups that treat PKS as a closed-loop complement to their core operations, supplying both domestic industrial boilers and export markets. Their advantage: feedstock security and internal price arbitrage opportunities.
Recent industry actions illustrate the strategic choices companies are making: capacity additions in strategic coastal locations, multi-year offtake agreements with sustainability clauses, and new long-haul shipments into established biomass markets. These moves confirm two structural themes: certification and logistics access are the immediate value multipliers; and scale in processing plus export capability materially improves negotiating leverage with large buyers and utilities.
Regulatory and Quality Constraints — Operational Realities
-
Certification requirements in key import markets have real economic consequences. Compliance regimes that verify origin and processing chain integrity shape which tonnes are contractable on long-term terms.
-
Origin-level trade measures and export administration changes can tighten or loosen realisable export economics. Even modest changes to export tariffs or service fees materially shift the margin calculus for both exporters and buyers.
-
Technical specifications matter in procurement: calorific value bands, ash content and moisture drive boiler performance, handling systems and downstream emission profiles. Buyers increasingly specify these parameters to reduce plant risk and maintenance costs.
Strategic Actions for 2026 — Tactical Steps with Immediate Payback
For corporate leaders planning budgets and contracts in 2026, the report recommends a focused set of executable steps that can be initiated in quarters rather than years.
-
Secure multi-year offtake frameworks that include flexibility clauses for modal choice and force majeure calibrated to seasonality. Prioritise counterparties that accept staggered pricing collars rather than rigid floor/ceiling structures.
-
Invest in certification and traceability early. The incremental operational cost of documented chain-of-custody is often exceeded many times over by the price premium and counterparty access it unlocks.
-
Conduct logistics-to-market audits. Small reductions in port dwell time and vessel scheduling uncertainty can yield outsized margin improvements across contracted volumes.
-
Calibrate procurement to quality tiers. A deliberate blend of screened and unscreened product, matched to buyer technical tolerance, can optimise yield while avoiding costly downgrades at delivery.
-
Prepare contingency sourcing corridors. Diversifying supply nodes, even within the same country, reduces exposure to localized levies, mill outages and transport disruptions.
Investment & M&A Radar
Investors and strategic buyers should prioritise assets that combine three attributes: processing capacity with modular scalability, deep buyer offtake relationships (preferably with sustainability clauses), and resilient port/rail access. Our transaction playbook—which includes due diligence templates and valuation sensitivities—targets these attributes, emphasising the need to stress-test projections against alternative palm oil price paths and regional trade-policy shifts.
Risk Management — What Keeps CFOs Awake
-
Policy volatility in originating countries that can change export economics quickly.
-
Quality divergence between batch receipts and contractual specs that can trigger penalties or rejection risk at destination boilers.
-
Logistics and vessel availability, where a single bottleneck can cascade into missed offtake deliveries and credit exposure.
Why PW Consulting’s Report Is Different
We combine a granular operational view (tender templates, QC checklists, port-rotation maps) with a robust macro model that produces scenario-weighted forecasts. Our market-concentration metrics and company capability matrices offer a diagnostic not found in commodity-only studies: we show where value accrues in the commercial chain and provide the implementation tools commercial teams need to capture it.
How to Use This Insight in 2026
-
Procurement teams: use the modelled price envelopes and tender templates to design contracts that reduce basis risk and lock in certified capacity.
-
Asset owners: use the scenario toolset to validate investments in processing or port-capacity expansions and to quantify payback under different demand-growth trajectories.
-
Investors and M&A advisers: apply the due diligence scorecards and consolidation playbook to prioritise targets that are most likely to deliver accretive margin expansion.
Next Steps
The summary here highlights the structural logic and actionable directions for corporates and investors considering PKS in 2026. To access the full intelligence — including detailed regional and application breakouts, company-level benchmarking, contract clause templates and the complete dataset underpinning our forecast — please consult the full Palm Kernel Shells Biomass Market report. PW Consulting offers bespoke briefings and implementation support packages to translate this market-level view into transactional milestones and operational change programs.
In a market growing at a mid-single-digit to high-single-digit compound rate and shifting under the twin forces of sustainability and logistics, 2026 is the year to convert strategic intent into measurable advantage. Our report gives you both the high-level map and the on-the-ground tools required to act with speed and conviction.
For detailed analysis of this topic, please visit the official page: Palm Kernel Shells Biomass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com