

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Robust Growth for Polymer Reinforcing Filler Market — From USD 14,250.6 Million in 2025 to USD 20,730.1 Million by 2032 at a 5.5% CAGR

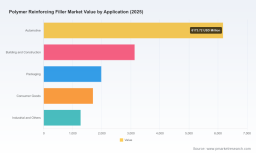
Polymer Reinforcing Filler Market — Strategic Outlook for 2026
Executive summary
PW Consulting’s latest Polymer Reinforcing Filler Market report delivers a pragmatic, decision-focused view of a market that has moved from niche engineering inputs to strategic raw materials for polymer value chains. The global market reached a robust base in 2025 (reported in USD Million terms) and — under a set of plausible demand, supply and technology scenarios — is projected to grow at a compound annual growth rate (CAGR) of approximately 5.5% through the 2026–2032 forecast window. By 2032 the market is expected to be substantially larger than its 2025 base, reflecting continued substitution, composite adoption, and parallel developments in circular feedstocks and specialty grades.
Polymer Reinforcing Filler Market
Why this matters for 2026 corporate decision-making
- Strategic sourcing: Reinforcing fillers are no longer commodity line items: variations in grade, surface treatment, and carbon footprint directly affect polymer performance, regulatory compliance and the lifecycle impact of finished goods.
- CapEx and footprint planning: Supply-side moves — capacity investments, regional expansions, and new processing technologies — require buyers and compounders to rethink single-sourcing strategies and lead times.
- Product roadmaps and differentiation: R&D choices around filler selection (e.g., glass fiber vs. specialty silica vs. engineered carbon blacks) are becoming a primary means to tune stiffness, durability and recyclability — and therefore to differentiate in automotive, construction and packaging end-markets.
- ESG and circularity: Emerging low‑carbon, recycled and chemically recycled reinforcing fillers are changing supplier selection criteria — procurement teams must integrate lifecycle assessments into commercial scoring and specifications.
Market snapshot (what the numbers say)
PW Consulting’s model synthesizes five years of historic performance (2020–2025) and projects through 2032. The market exhibited resilience through recent volatility, and our scenario-driven forecasting indicates steady expansion through the forecast period at an average CAGR of ~5.5%. This growth is fuelled by continuous innovation in specialty grades, rising composite penetration in weight-sensitive applications, and incremental substitution toward engineered mineral fillers and advanced carbon-based solutions.
Polymer Reinforcing Filler Market
Competitive landscape — who shapes the market
The reinforcing filler market sits between oligopoly and fragmented supply: the largest three players account for a meaningful share of the market but there remains a long tail of regional and specialty producers. PW Consulting’s concentration analysis shows a mid-range consolidation dynamic: the top three and top five players together hold a dominant yet non-controlling slice of global supply, leaving room for agile entrants and technology-driven disrupters.
Polymer Reinforcing Filler Market
- Cabot Corporation (Boston, MA) — A global leader in reinforcing carbons and specialty carbon blacks. Cabot is extending circular and low‑carbon offerings and pursuing partnerships to accelerate commercial adoption of circular reinforcing carbons.
- Birla Carbon (Aditya Birla Group) (Mumbai) — A major vertically integrated carbon black supplier with recent capacity moves to support polymer reinforcement demand and specialty grades for high-performance applications.
- Imerys S.A. (Paris) — A leading mineral filler supplier, focusing on engineered calcium carbonates, kaolin and talc variants that improve stiffness and dimensional stability in polymers.
- Omya AG (Oftringen) and Minerals Technologies Inc. (New York) — Both emphasize optimized mineral fillers and surface treatments to improve dispersion and reinforce mechanical properties in plastics and elastomers.
- Owens Corning and specialty compounders such as RTP Company — Key for glass-fiber reinforcement and custom compound solutions that bridge raw-material capability and application-level performance.
- Specialty and emerging players such as Plastic Energy, Huber, Hoffmann Mineral, LKAB Minerals and 20 Microns bring differentiated chemistries, recycled feedstocks and regional market access — all of which matter for tailored product strategies.
Recent competitive moves illustrate the market’s dual dynamic: incumbents expanding capacity and specialty portfolios while new entrants commercialize lower‑carbon or recycled fillers. These developments create immediate procurement and partnership opportunities for firms willing to move early.
Recent developments shaping 2026 strategy
- Major carbon black suppliers announced capacity and partnership initiatives to accelerate circular carbon adoption and broaden geographic production capability, indicating an industry pivot toward lower‑emission carbon fillers.
- Specialty mineral suppliers launched new silica and calcium carbonate product lines optimized for automotive polymers and packaging — a direct response to demand for better thermal stability and recyclability compatibility.
- Commercialization of recycled and chemically recycled reinforcing fillers has reached market entry stage in several jurisdictions, and one such product has secured regulatory registration enabling commercial use in Europe.
What the PW Consulting report contains — practical assets for executives
Beyond narrative, the report is structured as an operational toolkit for commercial, R&D and procurement leaders. Highlights include:
- Bottom‑up market sizing and consensus forecasts with scenario toggles for demand shocks, substitution and regulatory impacts.
- Supplier scorecards and an objective benchmarking framework combining technical capability, sustainability metrics, geographic reach and commercial terms.
- Price and margin sensitivity matrices that map raw‑material price moves to compounder and OEM P&L under multiple pass‑through regimes.
- Go‑to‑market playbooks for launching new filler-enabled compounds, including target customer segments, sample-pack strategies, and trial-to-qualification timelines.
- CapEx decision models and decision trees for capacity partnerships, greenfield versus brownfield expansion, and toll-processing options.
- M&A and JV blueprints identifying acquisition targets by technology, geography and capability band, with high-level valuation heuristics and integration risk checklists.
- Regulatory and sustainability roadmap including lifecycle assessment templates, compliance checkpoints and communications guidance for supplier contracts.
Strategic implications and actionable recommendations for 2026
We translate the market view into six priority actions that should inform board-level and executive decisions in 2026:
- Reclassify filler selection as a strategic lever: Move filler selection upstream into product design and procurement scorecards to capture performance and sustainability value rather than treating it as a last‑mile commodity choice.
- Secure flexible supply and engage in capacity partnerships: Hedge against regional supply risk by qualifying multiple suppliers across different technology nodes (e.g., engineered mineral, specialty silica, recycled carbon) and negotiate volume-flex contracts that include quality and carbon metrics.
- Invest selectively in co‑development: Pursue co‑development pilots with suppliers to tailor surface treatments or hybrid filler systems that enable weight reduction, cost down, or easier recycling — seek commercial options that convert pilot success into scaled supply agreements.
- Fast‑track low‑carbon alternatives where value accrues: Prioritize adoption of validated recycled and chemically recycled reinforcing fillers in product lines where carbon intensity commands a premium or where regulatory pressure is acute.
- Build a price‑sensitivity playbook: Model pass‑through impacts in your segments and set trigger-points for renegotiation, hedging or formula indexation tied to raw‑material benchmarks.
- Use M&A strategically: Consider tuck‑ins for specialty grades and regional players to accelerate technical capability, or JVs with recyclers to secure circular feedstock in markets with elevated sustainability requirements.
Near-term (0–90 days) and medium-term (6–12 months) action plans
PW Consulting recommends a two-horizon activation approach to convert insight into outcomes.
- 0–90 days: Conduct supplier risk mapping and qualify at least two alternative suppliers per high‑risk polymer line; launch lifecycle audits for top 3 SKUs by volume; initiate pilot discussions with one recycled filler provider.
- 6–12 months: Execute co‑development pilots converting at least one product family to a lower‑carbon filler where technical parity is achievable; finalize at least one strategic supply agreement with contractual SLAs on quality and carbon reporting; incorporate filler choices into product cost models and customer value propositions.
Risk factors and mitigations
Key risks include raw-material pricing swings, regulatory shifts related to additives and recycled content, and technology risk around scale-up of novel filler chemistries. PW Consulting’s report supplies probabilistic scenario maps and mitigation playbooks — from strategic inventory buffers and contractual indexation to accelerated qualification protocols and insurance-backed logistics solutions.
How to use the full report
This market brief is intentionally selective — offering the analytical framing and strategic recommendations you need to act in 2026 while limiting granular segment tables and price series to the full report. PW Consulting’s complete dataset and appendices include detailed regional and application-level forecasts, supplier-by-grade benchmarking, raw-material price time series and downloadable decision-support models that operational teams can drop directly into procurement, R&D and corporate planning workflows.
Conclusion — where value will be captured in 2026
The next 12–18 months will separate winners and laggards. Companies that treat reinforcing fillers as strategic inputs — integrating technical selection, supplier partnerships and carbon metrics into product roadmaps — will capture margin, customer‑facing differentiation and regulatory resilience. PW Consulting’s Polymer Reinforcing Filler Market report is designed to be the playbook for those decisions: rigorous, actionable and tailored to the operational realities facing procurement, R&D and corporate strategy teams in 2026.
To access the full dataset, supplier scorecards and decision-support tools referenced here, visit our report landing page — the granular segmentation and downloadable models are available there for subscription clients and enterprise licenses.
For detailed analysis of this topic, please visit the official page: Polymer Reinforcing Filler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com