

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: C9 Petroleum Resin Market to Reach USD 2,402.4 Million by 2032 at a 4.85% CAGR; Asia Pacific Holds USD 821.7 Million in 2025

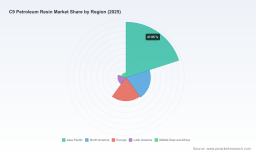
C9 Petroleum Resin Market: Strategic Imperatives for 2026 — PW Consulting
The C9 petroleum resin market is entering a decisive phase as legacy feedstock dynamics, evolving end‑use demand, and incremental product innovation reconfigure competitive advantage. Using 2025 as our base year, PW Consulting’s C9 Petroleum Resin Market Report synthesizes a continuous historical series (2020–2025) with a forward‑looking model (2026–2032) to quantify opportunity and risk. The global market grew from the low‑thousands (USD Million) at the start of the decade to an estimated USD 1,724.5 Million in 2025 and is forecast to expand at a compound annual growth rate (CAGR) of 4.85% through 2032, reaching roughly USD 2,402.4 Million by the end of the projection period. This briefing summarizes the strategic value the report delivers for decisions you will make in 2026 — while intentionally withholding the full proprietary segment-level tables to encourage direct review of the primary analysis and models.
C9 Petroleum Resin Market
Why this report is material to 2026 corporate decisions
-
Actionable clarity for capital allocation. Our integrated demand‑supply and margin model translates feedstock scenarios into expected cash‑on‑cash outcomes for new plant investments, debottlenecking and retrofits.
C9 Petroleum Resin Market -
Procurement and risk management playbook. The report maps the sensitivity of resin margins to upstream naphtha/C9 fraction swings and provides hedging and contract structures that midstream and downstream players can adopt immediately.
C9 Petroleum Resin Market -
M&A and partnership prioritization. We identify where scale, feedstock security, or proprietary grades translate into premium valuation multiples, and where bolt‑on acquisitions can be de‑risked by technology or customer overlaps.
-
Commercial and product stratification. The analysis gives revenue‑mix templates that help sales and innovation teams prioritize hydrogenated and specialty grades where value capture is highest.
-
Regulatory and sustainability readiness. Our regulatory appendix clarifies current risk profiles and tactical steps to prepare for evolving REACH/TSCA expectations and downstream customer requirements.
Core market dynamics that will shape 2026 outcomes
-
Feedstock architecture is the single largest strategic variable. C9 petroleum resins are produced from the aromatic C9 fraction, itself a byproduct of steam cracking. A structural shift in cracker feedstock mix — notably the move from naphtha to ethane — materially reduces C9 byproduct availability per unit of ethylene output. For integrated producers and merchant resin manufacturers alike, this alters feedstock security, margin volatility and the calculus on vertical integration.
-
Volatility transmission from upstream to resin margins. Historical episodes of naphtha and C9 fraction price spikes show rapid pass‑through to resin pricing, but with lags and differential exposure for thermal vs catalytic vs hydrogenated process routes. Our scenario workbench models multiple volatility regimes to quantify downside for unhedged players.
-
Regulatory posture is largely permissive today — hydrocarbon resins are assessed as low hazard in several recent regulatory evaluations and often qualify for polymer reporting exemptions. Nonetheless, expanded scrutiny on lifecycle emissions and chemical footprints means producers should proactively document supply chain emissions and impurities ahead of customer demands.
-
Incremental product innovation is a differentiator. Hydrogenation, catalytic control and crosslinkable formulations are moving from lab to commercial practice; producers that can cost‑effectively scale higher‑value grades will capture better margins even in a moderately consolidated market.
Demand structure and substitution vectors
Demand remains anchored in adhesives & sealants, paints & coatings, printing inks and rubber compounding — each exhibiting different sensitivity to resin grade, supply security and technical performance. Structural tailwinds include growing industrial and construction activity in selected geographies and an uptick in specialty formulations that demand more refined resin grades. At the same time, substitution risk exists from alternative tackifiers and polymer systems, particularly where formulators prioritize low VOC or bio‑based claims. PW Consulting’s market model flags which end‑use pockets are most likely to pay a premium for upgraded resin chemistries and which are likely to remain price‑sensitive.
Supply-side structure and competitive posture
The C9 resin market shows a moderate level of concentration, with the largest groups collectively holding a material share of capacity while a diversified base of regional and specialty producers supply local markets and niche grades. This balance creates both margin compression in commoditized segments and sustained premium capture for differentiated technologies and secure feedstock positions.
-
Kolon Industries (South Korea) — a domestic leader with unique proprietary formulations in aromatic and aliphatic resins and an early mover in crosslinkable hydrocarbon resins. Their playbook centers on formulation partnerships with adhesives and coating customers.
-
Neville Chemical Company (USA) — long‑standing USA producer with a strategic emphasis on secure domestic supply and technical service for high‑performance coatings and adhesives customers.
-
Eastman Chemical Company (USA) — brings integrated production and a broad hydrocarbon resin portfolio; positions itself to convert scale into global account penetration.
-
Cray Valley / TotalEnergies (France / USA) — global reach with continuous investments in resin technology and customer support, emphasizing specialty grades for inks and adhesives.
-
Chinese manufacturers (multiple) — a cluster of domestic producers who compete aggressively on price and supply flexibility for regional customers; several are advancing higher‑margin grades and export footprints.
-
ExxonMobil (USA) — integrated feedstock advantage; their resin strategy leverages upstream cracker economics and global commercial channels.
-
Arakawa Chemical (Japan) — steady provider with strong technical service in Asia and a focus on coating and adhesive segments.
Practical implications and recommended moves for 2026
-
Reassess feedstock strategy within 90 days. Firms should stress‑test existing contracts against at least three cracker feedstock scenarios (naphtha‑centric, mixed, ethane‑centric) and quantify the margin and supply risks for each production route.
-
Prioritize flexible production and premium grades. Capex planning should favor modular upgrades that enable shifts between thermal, catalytic and hydrogenation routes to capture premium demand without committing to single feedstock exposure.
-
Lock in strategic customer partnerships. Longer‑term off‑take arrangements with formulators in adhesives and coatings can de‑risk new capacity and support premium pricing for specialty grades.
-
Integrate sustainability disclosure into commercial terms. Collect upstream emissions and impurity data now to avoid last‑minute compliance costs and to position products for green‑premium procurement.
-
Use M&A selectively to acquire technology or feedstock security. Smaller bolt‑on plays that bring hydrogenation or crosslinkable tech, or that secure access to C9‑rich streams, are higher‑value targets than broad geographic roll‑ups.
-
Deploy dynamic pricing and analytics. Use near‑real‑time feedstock indices and customer elasticity models to move beyond static annual contracts.
What PW Consulting’s report delivers (practical, executable content)
The full report is structured to be actionable within procurement, strategy, R&D and commercial teams. Key deliverables include:
-
A bottom‑up market model covering 2020–2032 with scenario toggles for cracker feedstock mix, margin sensitivity, and end‑use demand elasticity.
-
Price and margin dashboards that translate upstream price movements into expected resin price bands and margin outcomes for thermal, catalytic and hydrogenated routes.
-
Competitive company dossiers with strategic SWOTs, capability maps and a decision matrix for partnership or M&A targets.
-
Technology and product roadmaps describing commercialization timelines and expected cost curves for higher‑value resin grades.
-
Regulatory and sustainability playbook summarizing current low‑hazard assessments plus recommended disclosure templates for customer use.
-
Commercial templates — 100‑day go‑to‑market plans, procurement contracting language, and capex evaluation checklists aligned to our scenario outputs.
How to use the report in 2026 boardroom discussions
-
Bring the scenario results to your next strategy offsite. Use our ethane vs naphtha scenarios to stress‑test your most capital‑intensive options and to set trigger points for investment.
-
Make procurement the owner of feedstock risk. Assign KPIs tied to margin leakage from feedstock volatility and deliver monthly flash reporting using our index templates.
-
Set a clear R&D milepost for upgraded grades. If you are aiming to commercialize hydrogenated or crosslinkable resins, map out a two‑year commercialization timeline with key customer validation gates.
-
Use the competitive dossiers to prioritize alliance or acquisition targets. Focus diligence on feedstock access, proprietary process IP, and customer stickiness instead of headline capacity alone.
Final note — why this is a “must‑read” before committing 2026 resources
Decisions made in 2026 will lock in feedstock exposure, product mix and commercial positioning for the better part of the decade. PW Consulting’s C9 Petroleum Resin Market Report turns opaque upstream dynamics and fragmented commercial signals into a clear set of strategic choices, modelled with scenario rigor and commercial immediacy. We present the analytical foundation you need to make defensible capital, procurement and product decisions — while reserving full proprietary segment tables and company‑level metrics for the complete report to preserve the actionable advantage for subscribers.
Access the full analysis
For access to the detailed datasets, proprietary segmentation, downloadable model, and the competitive dossiers referenced above, request the full C9 Petroleum Resin Market Report from PW Consulting. The full report contains the segment‑level splits, granular regional and application forecasts, and downloadable model files that support boardroom‑ready decision packages for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: C9 Petroleum Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com