

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Sulphur Pastilles Market Valued at USD 1,045.5 Million in 2025 to Expand at 4.12% CAGR (2026–2032)

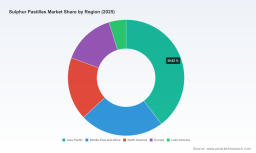
Sulphur Pastilles Market — 2026 Strategic Brief
Executive snapshot
PW Consulting’s latest market study on Sulphur Pastilles synthesizes five years of historical behaviour (2020–2025) and delivers a commercial roadmap for 2026–2032. The global market reached approximately USD 1,045.5 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 4.12% over the forecast period, with expected market size rising into the mid‑teens of hundreds of millions by 2032. For executives planning investments, procurement strategies, or M&A activity in 2026, the report frames the macro trajectory clearly while preserving the transaction‑level detail you need to act.
Sulphur Pastilles Market
Why 2026 is a strategic inflection year
-
Post‑pandemic demand normalization in core applications (fertilizer manufacturing, chemical processing and specialized industrial uses) has intersected with acute raw material price volatility, creating a period of compressed margins and selective opportunity.
Sulphur Pastilles Market -
Regulatory clarifications in major transport regimes have reduced logistics friction for formed sulphur products shipped in non‑bulk packaging — lowering barriers for rapid regional redeployment but increasing competition around service and reliability.
Sulphur Pastilles Market -
Market concentration remains meaningful: the top producers collectively hold a material share of supply, creating both risk of supply squeeze and pockets of competitive advantage for scale players. Our concentration analysis shows a moderate degree of consolidation among the highest‑volume suppliers, informing counterparty risk assessments and sourcing strategies.
What the PW Consulting report delivers (practical, transaction‑grade intelligence)
-
Market sizing and forecasting: validated top‑line market values (2020–2025 historical, 2026–2032 forecast with scenario bands) and growth drivers mapped to commercial KPIs.
-
Pricing & cost dynamics: rolling price curve analysis and sensitivity models that link feedstock sulphur prices to finished‑product margins and breakeven maps for different production technologies.
-
Supply chain heat‑maps: mill‑level and port‑level routing analytics, lead‑time distributions, and a supplier reliability index to prioritise sourcing lanes.
-
Commercial playbooks: procurement tactics (spot vs contract blend strategies), inventory thresholds tied to working capital optimization, and contract clause templates for volatility pass‑through and quality assurance.
-
Competitive & M&A landscape: strategic profiles, capability matrices, and a shortlist of opportunistic M&A targets and bolt‑on acquisition criteria for 2026 deployment.
-
Regulatory & logistics compendium: jurisdictional transport guidance, HSE triggers and a decision tree for packaging and movement that minimises compliance risk while retaining commercial flexibility.
-
Scenario playbooks: three executable scenarios (base, upside, downside) with actionable contingency plans for producers, traders and large‑scale consumers.
Data‑driven market dynamics you need to factor into 2026 plans
Our analysis synthesises price feeds, trade flows and plant utilisation to show how upstream sulphur feedstock moves through to pastilles. Price volatility has been pronounced in early 2026: regional price markers and spot indices show rapid month‑on‑month swings and significant year‑over‑year gains in several markets. This volatility materially affects cash margins for both industrial and agricultural grades, and it alters the economics of different product forms (e.g., pastilles vs. flakes) and logistics options (bulk vs. bagged shipments).
At the same time, transport regulation interpretations in multiple jurisdictions have effectively de‑risked certain non‑bulk shipments of formed sulphur, lowering compliance costs for bagged pastilles. This is a tactical lever: suppliers who can certify shape, moisture and packaging standards capture lower transport tariffs and faster customs clearances, improving delivery lead times for buyers willing to accept slightly higher unit prices for reliability.
Competitive landscape — who matters and why
The sector comprises established chemical producers, regionally dominant manufacturers and nimble specialist fabricators. PW Consulting evaluated operational footprints, product portfolios, technical differentiators and go‑to‑market models for leading firms. Highlights of companies covered in the study:
-
Martin Midstream Partners L.P. (USA) — Integrated production at multiple North American sites positions the company for domestic industrial supply and blended MP (Multipurpose Sulfur) offerings. The combination of multiple facilities and logistics assets is a defensive moat for large‑volume buyers seeking secure supply.
-
Coogee Chemicals (Australia) — Strong regional logistics and chemical handling expertise make Coogee a preferred partner for industrial consumers across Australasia, especially where inland distribution and regulatory know‑how are mission critical.
-
Tiger‑Sul (Tessenderlo Kerley Inc., USA) — A global footprint for industrial‑grade pastilles and value‑added forms (bentonite blends, micronutrient variants) that appeals to specialist end‑users and formulators. Their international processing and warehousing capability is a differentiator for global supply chains.
-
Georgia Gulf Sulfur Corporation (USA) — Known for rotoform technology producing uniform formed pastilles, Georgia Gulf’s technical capability serves buyers with strict particle‑size and flowability requirements.
-
Grupa Azoty (Poland) — An integrated producer with standardised product specs and outdoor handling systems suited to industrial supply contracts in Europe and neighbouring regions.
-
NEAIS / Said Ghodhran Group (Saudi Arabia) — Regionally significant producer using drop‑forming technologies targeted at agricultural and industrial markets in the Middle East and Africa.
-
Regional specialists and aggregators such as Swancorp, Devco Australia, Brimfert, Passion Ag, BTSCO and Petro Arkan — these companies deliver local market agility, niche technical propositions and cost‑efficient logistics for specific applications.
Strategic implications and recommended actions for 2026
-
Hedge selectively and design flexible contracts: Given price volatility, adopt a layered procurement approach — a base of contracted volumes with indexed clauses plus opportunistic spot purchases. Use the report’s pass‑through templates to reduce margin squeeze.
-
Prioritise supplier resilience over lowest price: The supplier reliability index in our study shows that small differences in on‑time performance can lead to disproportionate production downtime costs. For critical SKUs, prefer suppliers with diversified terminal access and established contingency stock arrangements.
-
Invest in packaging & logistics compliance: Where regulatory interpretations favour non‑bulk packaging, incremental CAPEX in certified bagging and QA reduces transport premiums and shortens lead times — a rapid ROI for mid‑sized traders and producers.
-
Targeted M&A and partnerships: For upstream players, acquire or partner with regional fabricators to secure downstream placement and faster market access; for traders, align with producers offering value‑added blends to capture higher margin segments.
-
Product & application diversification: Developers of micronutrient‑enhanced or tailored particle sizes can command premium pricing and lock in long‑term offtake contracts with agronomists and specialty chemical formulators.
-
Operational readiness for price spikes: Maintain a short list of alternate suppliers and pre‑negotiated transshipment options to manage sudden regional supply shocks driven by feedstock disruptions or logistic bottlenecks.
Why PW Consulting’s report becomes a 2026 decision‑making tool
Our study transforms raw market indicators into operational choices. It pairs top‑line forecasting with supplier‑level intelligence, contract templates, and tactical procurement playbooks — the elements business leaders need to convert market signals into defensible, cash‑accretive actions. The report is intentionally structured as a decision support system for 2026: not just numbers, but executable moves linked to measurable KPIs.
Next steps
-
For a complete set of segmented tables, supplier maps, pricing curves and the full set of tactical templates referenced in this brief, access the full Sulphur Pastilles Market report on the PW Consulting portal.
-
Contact our advisory desk for a tailored 90‑minute executive briefing where we overlay your P&L and procurement footprint on the report’s scenarios and deliver a customised action plan for Q2–Q4 2026.
PW Consulting — Bringing market clarity to strategic choices. For the full intelligence suite, supplier shortlists and modelled decision trees, visit our report page or request a direct briefing.
For detailed analysis of this topic, please visit the official page: Sulphur Pastilles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com