

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Polymer Reinforcing Filler Market to Reach USD 20,730 Million by 2032 — 5.5% CAGR from 2026 (Base Year 2025); Asia Pacific Leads with USD 6,394M

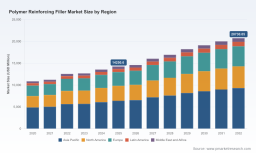
Polymer Reinforcing Filler Market: Strategic Imperatives for 2026 — PW Consulting Preview
PW Consulting today publishes a strategic preview of our upcoming Polymer Reinforcing Filler Market report (base year 2025). The market reached approximately USD 14.25 billion in 2025 and — driven by steady demand for reinforced polymers across transportation, packaging, construction and industrial applications — our central projection anticipates expansion at a 5.5% CAGR through the 2026–2032 forecast horizon, with the industry set to surpass USD 20.7 billion by 2032. This briefing summarizes the report’s practical value for 2026 decision cycles, highlights the competitive and sustainability dynamics reshaping the market, and outlines the executive actions we recommend. For the complete, granular segmentation data and company-level scorecards, access to the full report is required.
Polymer Reinforcing Filler Market
Why this matters in 2026: macro trends shaping near-term strategy
-
Demand resilience amid structural change: Polymer reinforcing fillers continue to be a core enabler of lightweighting, cost optimization, and performance uplift across multiple end markets. Although macrocycles introduce periodic volatility, underlying industrial and mobility trends (e.g., electrification, stricter fuel economy/CO2 targets, and expanded use of engineered plastics) are sustaining mid-single-digit growth.
Polymer Reinforcing Filler Market -
Supply-side shifts and pricing pressure: Raw material cost drivers remain a live issue for procurement and margin planning. For example, North American calcium carbonate pricing reached circa USD 0.32/kg in December 2025 — a reminder that feedstock swings can reshape substitution economics and force rapid reformulation choices at scale.
Polymer Reinforcing Filler Market -
Sustainability as a structural divider: Low-carbon and circular filler technologies are transitioning from niche to commercial. Notable developments include REACH-registered recycled reinforcing fillers that claim materially lower life-cycle emissions compared with conventional carbon black. Adoption will accelerate where OEMs and converters can quantify CO2 benefits without compromising mechanical performance.
-
Consolidation and competitive concentration: The market exhibits moderate concentration — the top three and top five suppliers account for material portions of global capacity — creating both stability in supply and clear levers for incumbents to pursue premiumization, capacity investments, or bolt-on M&A strategies.
What PW Consulting’s report delivers — practical, decision-ready components
Our full report is designed for commercial and technical leaders who must make tangible choices in 2026. The deliverables are intentionally operational rather than purely descriptive:
-
Robust market model (2020–2032) with sensitivity layers: total-market trajectories, unit demand drivers, and three explicit demand scenarios tied to mobility, construction cycles and packaging recovery rates.
-
Supplier capacity and risk map: plant-level footprints, announced expansions and near-term availability windows — enabling procurement to model supply shocks and lead-time exposure.
-
Material economics and substitution matrix: cross-material parity curves that quantify when silica, calcium carbonate, glass fibers or carbonaceous fillers become cost-effective substitutes given property targets and feedstock pricing.
-
Technology adoption roadmap: maturity curves for circular carbon and chemically recycled mineral blends, performance equivalency benchmarks, and adoption thresholds for OEMs and compounders.
-
Sustainability playbook: LCA comparators, compliance checklists (including REACH implications), and supplier scoring to fast-track low-emission sourcing decisions.
-
M&A and partnership playbook: target-screening filters, integration risk checklists, and deal valuation templates tailored to the materials space.
-
Interactive executive dashboard: scenario toggles (feedstock price, policy shocks, substitution rates) that translate market moves into P&L and balance-sheet impacts for buyers and producers.
Note: in keeping with our “preview” approach, we are intentionally withholding full regional, type and application breakdowns in this release — those detailed splits and the underlying database are accessible in the full report and accompanying models.
Competitive landscape — what to watch in 2026
The competitive terrain is defined by a blend of legacy majors scaling specialty grades, mineral producers optimizing cost positions, and new entrants commercializing circular or recycled reinforcing fillers. Key dynamics and company-level implications from our coverage include:
-
Cabot Corporation — recent acquisition activity and announcements around circular reinforcing carbon reflect a strategic pivot: secure feedstock and co-develop low-carbon product pathways with tire and rubber OEMs. Their Asia Pacific production capability expansion positions them to capture accelerating demand for circular carbons in high-volume applications.
-
Birla Carbon — capacity additions in Asia for ultra-high-performance carbon blacks indicate a two-pronged play: defend tire and mechanical rubber goods leadership while moving up the performance curve for polymer and coating specialties.
-
Imerys, Omya, MTI and other mineral majors — product launches targeting improved dispersion, thermal stability and bio-compatible chemistries show a shift from commodity selling to engineered solutions that enable higher filler loadings without compromising processability.
-
Plastic Energy and other circular innovators — the commercialization of chemically recycled reinforcing fillers (REACH-registered, with published carbon reduction claims) is a catalytic development. These entrants create an alternative sourcing pathway for buyers seeking lower-scope emissions footprints.
-
Composite specialist suppliers (e.g., Owens Corning, RTP Company) — glass fibers and specialty compounders remain critical where mechanical performance mandates fiber reinforcement. Their partnerships with OEMs create entry barriers for lower-cost mineral substitution in high-performance applications.
Strategically, these movements translate into three actionable implications: incumbents must accelerate product differentiation and circular capabilities; converters should run parallel qualification tracks for lower-carbon substitutes; and investors should re-evaluate target screens to include circular-chemistry IP and downstream compounding expertise.
Strategic actions we recommend for 2026 decision cycles
-
Procurement and supply chain: implement multi-sourced contracts for key filler families and build FLEX options with regional converters to mitigate single-point capacity risk. Use the report’s supplier-risk heatmap to prioritize contractual hedges and buffer inventory strategies.
-
R&D and product strategy: fast-track co-development with circular filler providers where LCA benefits are demonstrable and set joint validation timelines with OEMs to shorten go-to-market cycles.
-
Commercial and pricing: adopt differentiated pricing for low-carbon or high-performance grades; use substitution cost curves to defend margin while enabling customers to meet sustainability targets.
-
Investment and M&A: target bolt-ons that add surface-treatment capabilities, specialty mineral processing, or chemical-recycling feedstock access. The report’s M&A playbook prioritizes assets that accelerate either margin expansion or technological preemption.
-
Regulatory and sustainability: integrate REACH and regional EPR policy scenarios into long-range planning. Prioritize suppliers with certified lower-emission product pathways and transparent LCA data to de-risk downstream compliance demands.
How executives will use this report in 2026
-
Procurement teams will model supplier exposure under price shock and capacity shortfall scenarios and convert those into negotiated terms.
-
Product and formulation teams will use substitution matrices and performance benchmarks to decide when to switch filler chemistries without re-engineering entire platforms.
-
Corporate development teams will apply the M&A playbook to prioritize targets that either extend sustainable product portfolios or fill strategic gaps in processing and surface treatment.
-
Sustainability leads will deploy the report’s LCA comparators to quantify version-to-version emissions improvements and to prepare procurement specifications for low-carbon fillers.
Closing — the strategic value proposition
For 2026, the strategic calculus in the polymer reinforcing filler market hinges on three interlocking imperatives: securing resilient and flexible supply; differentiating via material performance and sustainability; and timing investments or partnerships to capture structural demand growth. PW Consulting’s full report combines a rigorous market model, plant-level supply mapping, technology-adoption roadmaps, and operational playbooks to move leaders from insight to action. This preview has highlighted the high-level implications and recent commercial milestones; the full dataset and company-level scorecards — including the granular regional, type and application splits that underpin scenario testing — are available through our report portal.
To obtain the full report, access the interactive dashboard, or arrange a bespoke executive briefing tailored to your business unit’s priorities for 2026, please visit PW Consulting’s report page or contact our industry team directly.
For detailed analysis of this topic, please visit the official page: Polymer Reinforcing Filler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com