

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Cold Roof Coating Market to Reach USD 8,611.45 Million by 2032, Growing at a 7.15% CAGR

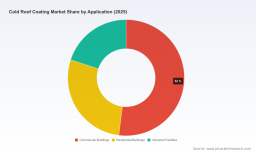
Cold Roof Coating Market — Strategic Preview for 2026: Why PW Consulting’s New Report Is a Decision-Maker’s Playbook
As building owners, manufacturers, and investors position for the next growth cycle in energy-efficient building materials, cold roof coatings have emerged from niche retrofit solutions into a mainstream category with measurable impact on operating costs, regulatory compliance, and sustainability commitments. PW Consulting’s latest market study — covering historical performance (2020–2025), a 2025 base year, and a detailed forecast horizon (2026–2032) — distills what corporate leaders must know now to make defensible decisions across product development, sourcing, pricing, and M&A throughout 2026.
Cold Roof Coating Market
Macroeconomic Trajectory: Growth that Pays Attention
The cold roof coating market is on a sustained expansion path. PW Consulting’s model positions the global market at approximately USD 5.31 billion in 2025, growing at a compound annual growth rate (CAGR) of 7.15% over the forecast period. By 2026, the market is projected to exceed USD 5.6 billion, and the base-case scenario carried through our sector models reaches beyond USD 8.6 billion by 2032. These topline dynamics are driven by a mix of regulatory adoption, building-code requirements tied to solar reflectance and SRI performance, accelerated retrofit pipelines in commercial portfolios, and increasing specification activity for new-build projects prioritizing thermal performance.
Cold Roof Coating Market
What the Report Contains — Practical, Executable Insight (Not Just Charts)
- Integrated market-size and demand-driver modeling that translates macro policy levers and climatic exposure into quantifiable demand scenarios.
- Segmentation-focused playbooks (by product chemistry, end-use application, and channel) that prioritize where to invest R&D, where to defend, and where to harvest.
- Raw-material and cost-pass-through frameworks that link petrochemical feedstock volatility and pigment pricing to margin outcomes under realistic contract structures.
- Regulatory-compliance mapping that overlays the latest ANSI/CRRC S100-2025 testing protocols and CRRC program developments onto product development and labeling roadmaps.
- Commercial execution tools: specification templates, procurement negotiation levers for large accounts, installer certification and warranty program design principles, and a six- to 18-month go-to-market sprint plan.
- M&A and partnership diagnostics: valuation premia drivers, integration risk checklists, and a short-listing methodology for bolt-on targets based on technological fit and route-to-market synergies.
Importantly, the report is structured to be used in boardrooms and by business-unit leaders: each chapter concludes with “Decision Points” and a one-page action plan tailored to either an incumbent manufacturer, an investor evaluating entry, or a large specifier seeking to accelerate rooftop conversions.
Cold Roof Coating Market
Competitive Landscape — Who’s Shaping the Market and How
Competition in the cold roof coating sector balances large, diversified chemical companies with specialized niche formulators. Market concentration is moderate: the top three players account for roughly one-third of market revenue, while the top five approach the mid-forties percentile. This structure creates both room for scale advantages (procurement, distribution, cross-selling) and opportunities for targeted differentiation (product performance, certification, installer networks).
- Sherwin-Williams — leverages global architectural channels and high-performance infrared-reflective pigment systems. Their scale in commercial and industrial coatings makes them a go-to for integrated roofing system specifications.
- PPG Industries — focuses on high solar-reflectivity formulations and global distribution reach; delivers solutions that exceed aggressive reflectance thresholds sought by white-paper led sustainability teams.
- AkzoNobel — pushes elastomeric and durability-led offerings, emphasizing long-life solutions for commercial roofs in variable climates.
- RPM (Tremco and others) — operates at the intersection of liquid-applied systems and restoration economics; positions warranty and system-level performance as a commercial differentiator.
- BASF, Dow, and Sika — supply base chemistries, dispersions, and system components; their role is critical in upstream innovation and scale manufacturing economics.
- GAF, Henry (Carlisle), Gardner-Gibson, Karnak, Western Colloid — regional and specialty brands that compete on substrate compatibility, installer relationships, and cost-effective restoration solutions.
- Niche innovators (NanoTech Materials, Castagra, Neogard) — targeting high-value points with ceramic-insulative technologies, VOC-free systems, and high-performance urethanes that meet CRRC listings and regional regulatory standards.
Recent industry moves underscore competitive dynamics: new product launches combining fiber reinforcement and low-VOC chemistry; extended warranty programs tied to installer certification; and standards evolution with CRRC updating ANSI/CRRC S100-2025 and accrediting the first international independent testing lab. These developments alter the barrier-to-entry calculus: product performance alone no longer suffices without certified testing and clearly articulated lifecycle economics.
Key Market Dynamics and Risks for 2026 Decision-Making
- Raw-material volatility: Acrylics, silicones, and pigment inputs remain linked to petrochemical cycles and titanium dioxide supply chains. Our scenario models show margin sensitivity when price spikes occur and when product portfolios skew heavily toward premium chemistries without price-protection mechanisms.
- Premiumization vs. Cost-Accessibility: Silicone-based systems command a notable price premium versus acrylic alternatives due to longevity and weathering performance. Manufacturers and specifiers need playbooks for justifying higher upfront costs via lifecycle TCO and warranty transferability.
- Standards and certification: ANSI/CRRC S100-2025 reshapes testing expectations for liquid-applied coatings and composite materials. Producers who are early to secure CRRC listings and who can demonstrate test-to-spec performance on rough substrates will gain faster entry into code-driven procurement streams.
- Installer and warranty ecosystems: Extended warranties backed by installer certification are becoming table stakes in commercial retrofit contracts. Programs that combine training, serial-quality audits, and conditional warranty economics materially reduce project risk for large building owners.
- Consolidation potential: With CR3 and CR5 concentration levels indicating moderate dominance by a handful of firms, M&A remains a strategic lever for both market incumbents seeking technology and channel for new entrants searching scale.
Top Strategic Moves for 2026 — What Leaders Should Do Now
- Prioritize certification and testing: Allocate R&D and lab budgets to secure CRRC-compliant listings under the S100-2025 framework. Factor third-party lab timelines into product launch calendars — the recently accredited international testing capacity shortens time-to-market for globally distributed SKUs.
- Design warranty-linked commercial offers: Build installer certification pathways tied to multi-tiered warranty products. Our financial models show that warranty programs, when coupled with performance-based pricing, accelerate procurement inclusion with national contractors.
- Hedge raw-material exposure: Implement multi-source procurement and index-linked supply contracts for pigments and base polymers. Consider strategic inventory cushions for titanium dioxide and specialty resins to avoid costly production halts during feedstock shocks.
- Rebalance portfolio for lifecycle value: Segment offerings into “performance longevity” and “cost-accessible” lines. Use targeted pilots to validate TCO narratives in different climates and asset classes, and capture case studies that justify premium positioning.
- Expand retrofit-as-a-service pilots: For manufacturers and service providers, co-develop financing and performance-guarantee offers with building owners to lower adoption friction and demonstrate near-term energy savings.
- Use M&A as capability-buying: Target bolt-ons that bring proprietary chemistries, localized installer networks, or testing lab capacity instead of purely acquiring incremental volume.
Why This Matters for 2026 Budgets and Boardroom Priorities
Decisions made in 2026 will influence several years of revenue mix and margin profile. The market’s steady CAGR supports growth investments, but the operational execution — certification timing, warranty economics, and raw-material management — determines which players capture durable value. PW Consulting’s study equips leaders with the quantitative scenarios and executable playbooks needed to convert regulatory momentum and sustainability commitments into repeatable business models.
Next Steps — Accessing the Full Intelligence
This preview reflects the strategic contours of PW Consulting’s Cold Roof Coating Market report. The full dossier contains the granular scenario models, procurement negotiation templates, product-specification matrices, and the proprietary financial model that underpins our forecasts. For executives who require board-ready briefing decks, supply-chain simulations, or tailored M&A screening lists, PW Consulting offers bespoke workshops and implementation sprints aligned with the report.
Contact PW Consulting or visit our website to download the executive summary and to arrange a briefing. Our clients use the report to de-risk 2026 product launches, shape warranty-backed commercial offers, and prioritize capex and M&A that produce measurable, near-term returns.
For detailed analysis of this topic, please visit the official page: Cold Roof Coating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com