

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Ocean Wave Energy Market Poised for Rapid Expansion — Forecasted 16.52% CAGR

Ocean Wave Energy Technology Market — Strategic Preview for 2026 Decision-Makers
Executive summary
As governments and utilities accelerate decarbonization pathways, ocean wave energy is transitioning from niche pilots to commercially credible projects. PW Consulting’s new market study — grounded on a 2025 base year and projecting through 2032 — quantifies this transition and provides the operational playbooks that executives, project developers, investors, and policymakers need to make high‑confidence decisions in 2026.
Ocean Wave Energy Technology Market
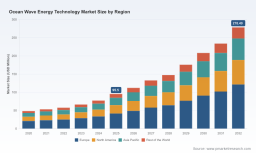
At the macro level, the global ocean wave energy market has more than doubled in reported revenue since 2020 and is forecast to expand at a compound annual growth rate (CAGR) of approximately 16.5% across the 2026–2032 forecast window. This trajectory reflects a convergence of maturing device designs, targeted public funding, emerging commercial offtake mechanisms, and early evidence of sustainable operations cost profiles. Importantly, while the sector remains fragmented with a moderate degree of concentration among the leading technology providers, the pace of scale‑up in key markets creates clear windows for strategic entrants and incumbents alike.
Ocean Wave Energy Technology Market
Why the report matters for 2026 corporate strategy
- Timing: 2026 is a pivotal year for first commercial array deployments and test‑site commercialization. Decisions made this year on partner selection, site contracting, and supply‑chain commitments will materially influence 2027–2029 cost trajectories and equity returns.
- Capital allocation: The market profile in our study translates technology readiness and operational risk into investable scenarios. That enables CFOs and investment committees to compare probabilistic IRR outcomes across device classes, geographies, and business models.
- Policy leverage: New and scheduled public programs — including sizable competitive grants and infrastructure support — change the economics for early movers. Incorporating these into commercial negotiations and project timelines is now table stakes.
Market trajectory — the numbers that drive boardroom decisions
PW Consulting’s topline time series tracks the market from a modest commercial base in 2020 to accelerated commercial activity by 2025 (base year). The study documents a clear inflection: market revenue more than doubled during the 2020–2025 historical window and continues on an accelerated path into the forecast period. The report models this expansion under multiple scenarios, with a central case CAGR of ~16.52% for the forecast horizon. By tying market size, cost curves, and deployment schedules together, the analysis transforms headline growth rates into actionable timing for procurement, manufacturing scale‑up, and O&M planning.
Ocean Wave Energy Technology Market
What’s in the report — practical, decision‑grade content
- Investment framework: Deal‑ready financial models (sensitivity matrices, return profiles, and de‑risking mechanisms) tailored for equity, project finance, and blended finance structures.
- Technology and performance playbooks: Device‑agnostic acceptance criteria, site‑selection checklists, survivability testing protocols, and commissioning milestones mapped to commercial revenue triggers.
- Operational cost modeling: Benchmarks and drivers for CAPEX, OPEX, lifecycle replacement schedules, and logistics footprints; comparative scenarios for onshore/nearshore vs. offshore deployments.
- Supply chain mapping: Critical node analysis from composite hull manufacturing to PTO (power take‑off) systems and mooring/anchor supply, with supplier risk ratings and localization pathways.
- Policy & market readiness toolkit: Contract templates, PPA negotiation playbooks, regulatory roadmaps, and public funding capture strategies specific to marine energy corridors.
- Commercialization roadmaps: Step‑by‑step pathways to move from pilot to pilot‑plus to commercial array — including partner archetypes, staging timelines, and sample procurement schedules.
- Proprietary datasets and models: Interactive scenario tools that convert macro growth into project‑level demand, supply, and price forecasts — core subsegment data is excluded from this public summary to preserve the report’s subscription value.
Competitive landscape — who matters and why
The sector’s competitive map is characterized by a broad set of specialized device developers, several of whom have achieved meaningful operational milestones in the past 18–24 months. This creates a buyer’s market for offtake partners and a competitive pool for project developers seeking validated technologies.
- Eco Wave Power — With a practical onshore model that leverages existing marine infrastructure and recent U.S. pilot completion, Eco Wave demonstrates the near‑term commercial pathway for land‑connected approaches. Their automation and O&M metrics from recent projects point to tangible reductions in operational uncertainty.
- CorPower Ocean — CorPower’s compact point absorbers and demonstrated survivability at commercial test sites make it a candidate for high‑energy array deployments. Device efficiency and hull composite choices influence overall array productivity and lifecycle costs.
- Carnegie Clean Energy — CETO’s combined wave power and desalination capability represents a differentiated value proposition for co‑located utility and water‑security projects, particularly in water‑stressed coastal regions.
- Ocean Power Technologies , AW‑Energy , Mocean Energy — These established players span key device classes and have moved toward utility‑scale readiness, each offering alternative reliability and deployment profiles attractive to specific market niches.
- U.S. innovators (Oscilla Power, CalWave, ORPC) — Benefiting from domestic test sites and federal support, these companies are advancing drivetrain and multi‑degree‑of‑freedom capture technologies, which could shift cost curves if scaled rapidly.
- Seabased, NoviOcean, Marine Power Systems — Representing seabed, inverted hydropower, and hybrid platform approaches, these firms expand the technology mix available to project developers and system integrators.
Collectively, the top three companies account for a modest share of the market by revenue, and the top five capture under half of market revenues — a structure that favors strategic consolidation, selective partnership, and differentiated niche strategies.
Recent developments that change commercial calculus
- Deployment momentum: Multiple firms completed pilots and commercial‑scale tests in 2025–2026, including the first U.S. onshore project deployments and successful survivability trials in high‑energy environments.
- Offtake and revenue signaling: A landmark power purchase agreement for wave‑generated energy from a U.S. test facility (covering multi‑MW outcomes) establishes precedent for utility procurement terms and credit structures.
- Public funding & infrastructure: Major competitive programs are now resourcing device development and open‑water testing — including a dedicated multi‑year federal funding window that materially lowers early‑stage cost burdens for developers and sponsors.
- Operational cost evidence: Real project O&M results have begun to surface, with at least one onshore project reporting OPEX at a low single‑digit percentage of initial CAPEX in its inaugural full‑year operations, validating lifecycle cost assumptions used in many commercial models.
- Materials and manufacturing trends: Adoption of advanced composites (e.g., filament‑wound GFRP) and modular PTO designs is driving weight‑to‑cost improvements and improving manufacturability for serial production.
Policy and infrastructure outlook
Public programs and test infrastructure are now aligned to accelerate commercialization. The U.S. Department of Energy has launched a targeted funding opportunity over multiple years that allocates over one hundred million dollars to marine energy development, supporting device maturation, open‑water testing, and utility‑scale demonstrations. Complementary test sites are scheduled to host first prototype deployments in the near term, creating focal points for procurement, grid integration trials, and supply‑chain clustering.
Strategic recommendations — actions for 2026
- Prioritize early commercial PPAs and staged offtake: Secure staged offtake tied to commissioning milestones to share technology and grid‑integration risk with developers.
- Adopt a modular procurement strategy: Favor options that allow rapid substitution of PTO and mooring components as suppliers prove serial production metrics.
- Form hybrid consortia: Pair device developers with desalination, offshore energy, or port infrastructure partners to capture co‑value streams and improve IRR profiles.
- Lock in manufacturing partnerships now: Lead times for specialized composite hulls and PTO components will lengthen with scaling; early supplier agreements reduce schedule risk and improve pricing certainty.
- Use public funding as de‑risking capital: Blend grants and concessional capital into first arrays to improve bankability for private lenders.
- Invest in O&M intelligence: Remote monitoring, automation upgrades, and condition‑based maintenance can materially lower lifecycle costs — evidenced by operational pilots that have achieved sub‑4% OPEX-to‑CAPEX ratios in early operation.
Risk & concentration assessment
Market concentration metrics indicate that leadership is distributed among several specialized vendors rather than dominated by a single incumbent. This structure reduces single‑point technology risk for buyers but increases the importance of rigorous due diligence on supply chain capacity, failure modes, and retrieval/repair logistics. The report’s risk matrices convert technology, market, and regulatory risks into investable mitigation steps and reserving strategies.
Conclusion & how to use the full study
Our market study serves as a strategic playbook: it turns macro growth forecasts and public funding levers into operational plans and investment actions for 2026. Senior executives will find the report particularly valuable for timing capital calls, structuring PPAs, designing supply‑chain agreements, and prioritizing R&D pathways.
To preserve the report’s tactical value for subscribers, this public synopsis intentionally omits the granular subsegment breakdowns, regional and application‑level percentage allocations, and device‑level revenue schedules that underpin project‑specific financials. Organizations preparing procurement strategies, investment commitments, or regulatory engagement plans should access the full report for the proprietary datasets, interactive scenario models, and deal‑ready templates that convert sector growth into executable projects.
Contact PW Consulting to obtain the full Ocean Wave Energy Technology Market report and subscriber access to the interactive financial models and procurement playbooks designed specifically for 2026 commercial decision cycles.
For detailed analysis of this topic, please visit the official page: Ocean Wave Energy Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com