

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: High-Barrier MDO-PE Film Market Poised for 14.5% CAGR as Food Packaging Fuels Demand

High-Barrier MDO-PE Film Market: Strategic Imperatives for 2026 — PW Consulting Preview
The High-Barrier MDO-PE Film market is transitioning from a technically interesting niche to a strategic vector for packaging resiliency and circularity. Our new PW Consulting market study — based on a 2020–2025 historical base and a 2026–2032 forecast horizon — shows a sustained double‑digit expansion trajectory, underpinned by regulatory pressure, materials substitution and targeted product innovation. The total market, which approximately doubled over the 2020–2025 period, is projected to grow at a robust compound annual growth rate (CAGR) of about 14.5% through the forecast window, outpacing many conventional flexible packaging segments and signaling material strategic choices for 2026 planning cycles.
High Barrier Mdo Pe Film Market
Why this report matters for 2026 decisions
-
Regulatory inflection points are compressing timelines. Packaging requirements in major markets are accelerating adoption of mono‑material, recyclable structures; brand owners and converters must reconcile performance needs (oxygen and moisture protection, aroma retention, heat resistance) with compliance and recyclability targets.
High Barrier Mdo Pe Film Market -
Technology substitutions are materializing. Developments in EVOH co‑extrusion, vacuum coatings (AlOx/SiOx) and optimized MDO processing are enabling PE‑based constructions to replace multi‑material films and even aluminum foil in selected use cases—changing lifecycle economics and recycling pathways.
High Barrier Mdo Pe Film Market -
Commercial dynamics are noisy but directional. Resin price volatility and regional resin availability are affecting landed costs and arbitrage opportunities for converters. Meanwhile, practical product launches and collaborations from leading suppliers are lowering the technical and commercial barriers to broader adoption.
What the PW Consulting report delivers (practical, executable content)
-
Market sizing and scenario forecasts: multi‑scenario total market forecasts through 2032 with sensitivity to resin price cycles, regulatory adoption rates and downgauging potential.
-
Technology playbook: side‑by‑side technical comparisons of EVOH co‑extrusion vs. vacuum coatings vs. specialty polyamide/PE structures, including performance envelopes (OTR/WVTR ranges), process implications, and quality‑control checklists for scale‑up.
-
Commercial models and ROM (run‑of‑model) cost decks: unit cost drivers, contract negotiation levers, and blended landed cost scenarios under different resin price regimes.
-
Supplier and competitive maps: capability heatmaps, technology roadmaps of key producers, and a diligence checklist for qualification of new suppliers or partnerships.
-
Go‑to‑market playbooks: pilot design templates, validation protocols for barrier performance and shelf‑life studies, and retailer‑facing sustainability narratives that align with recyclability claims.
-
M&A & investment screening: thresholds and bet sizes for vertical integration (coating lines, EVOH compounding) versus long‑term supply agreements.
Competitive landscape—who is shaping the market now
The competitive picture blends multinational film specialists, regional champions and technology‑driven newcomers. Several firms have moved from concept to commercial scale in 2024–2025, demonstrating both product credibility and emerging commercial traction. Our study includes detailed profiles and strategic assessments of leading players and market entrants, with pragmatic advice for partnership, sourcing and competitive response.
-
RKW Group (Mannheim, Germany) — RKW’s RKW Horizon® MDO‑PE family exemplifies the co‑extruded EVOH approach that targets mono‑material recyclability without sacrificing oxygen protection. For brand owners seeking rapid substitution of multi‑material structures, RKW represents a low‑integration partner with strong marketing and application support. Risk: premium positioning and supply constraints during ramp phases.
-
Polifilm (Germany) — With solutions that can function as print substrates or barrier layers, Polifilm is focused on enabling converters to replace traditional PET/OPP/OPA laminates while improving recyclability and stiffness. Opportunity: converters seeking a drop‑in optics/print solution; watch for how Polifilm balances price and availability.
-
CloudFilm (Qingdao, China) — A supplier of high‑barrier MDO‑PE grades and AlOx coated variants aimed at food, pet food and pharmaceutical laminates. Strengths include local supply density and coating capability that supports 100% PE recyclable constructions—critical for APAC demand growth.
-
TOPESOL (Guangdong, China) — Producing high‑barrier grades that in some cases rival traditional aluminum foil, TOPESOL’s portfolio is notable for extremely low OTR/WVTR performance. Strategic consideration: these grades enable brand owners to pursue high‑barrier mono‑PE pack formats for aroma‑sensitive goods but may require altered sealing and form‑fill processes.
-
Longdapac (Hebei, China) — Positioned as a large‑scale producer of single‑material, high‑barrier MDO‑PE films, Longdapac is important for buyers prioritizing scale and cost‑efficiency, especially for commodity packaging categories.
-
Novel Packaging, Silvalac, ISOFlex — Each brings differentiated value—competitive pricing and polymer film expertise (Novel), rigidity‑focused mono‑material films (Silvalac), and BOPP/PET to MDO‑PE transition services with How2Recycle alignment (ISOFlex). Suppliers like these are closing technical gaps and expanding converter choices.
Signals from the field: product launches and collaborations
-
RKW’s mid‑2025 launch of integrated EVOH MDO‑PE films signals that high‑functionality mono‑material options are commercially viable and available to converters and brand owners.
-
Strategic collaborations like the late‑2025 TotalEnergies partnership to develop downgauged unlaminated MDO‑PE for deep‑freeze applications illustrate the industry focus on downgauging and line‑speed optimization—both critical to reduce mass per pack while maintaining barrier performance.
Market dynamics and risk map
Three structural dynamics will dominate boardroom debates in 2026:
-
Regulatory cadence: Tightening packaging regulations in major markets are making recycled‑content mandates and recyclability claims business‑critical, not optional. Adoption speed will differ by market segment, but timing risk is real for businesses delaying material transition.
-
Input cost volatility: Resin price swings and regional HDPE availability continue to inject cost uncertainty into conversion economics. Procurement strategies that incorporate indexed contracts, regional sourcing diversification and value‑share conversations with suppliers will materially de‑risk margins.
-
Performance vs. circularity tradeoffs: While MDO‑PE solutions close many functional gaps, some ultra‑high‑barrier applications still require hybrid or metallic layers. The strategic choice is whether to accept incremental performance differences in return for clear recyclability and simplified end‑of‑life pathways.
2026 playbook — recommended executive actions
-
Mandate cross‑functional pilots: procurement, R&D and sustainability must jointly run application pilots to quantify shelf‑life, downgauging potential and total cost of ownership within 12 months.
-
Supplier qualification with staged commitments: prefer flexible offtake agreements that reward incremental volume growth and include technical KPI clauses (OTR/WVTR, seal integrity, optics).
-
Hedge resin and logistics risk: adopt blended procurement approaches, including regional contracts, strategic safety stock and indexed pricing to protect gross margins.
-
Invest in capability vs. outsourcing analysis: evaluate capex thresholds for installing coating lines or EVOH compounding against strategic supplier partnerships and long‑term cost models.
-
Align brand claims with verification: create consumer‑facing narratives tied to measurable recyclability outcomes and validated by third‑party recyclers to avoid greenwashing risk.
-
Prepare for consolidation and M&A: prioritize targets that fill capability gaps (coating capability, EVOH compounding, regional footprint) to accelerate time to market.
What we deliberately withhold here and why
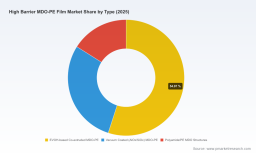
This preview emphasizes strategic implications and actionable frameworks while intentionally withholding the granular segment tables, regional and application split percentages, and the full price‑sensitivity matrices that drive procurement contracts. Those detailed inputs — including interactive dashboards, downloadable financial models and supplier share analyses — are contained in the full PW Consulting report and our supporting data portal. This “preview” approach is designed to show the analysis depth and practical utility without replacing the full dataset that commercial decision‑makers require for execution.
Conclusion — positioning for 2026
For executives setting 2026 priorities, High‑Barrier MDO‑PE is not merely a product innovation; it is a strategic lever that addresses regulatory compliance, sustainability targets and unit cost pressures simultaneously. The technology is sufficiently mature to support scaled commercialization in many packaging segments, but success will depend on disciplined supplier qualification, joint piloting, and careful cost‑risk management. Our full study contains the granular market splits, supplier scorecards and financial models needed to convert these strategic priorities into operational roadmaps.
To access the complete report, interactive datasets and a tailored briefing for your executive team, visit the PW Consulting research portal or contact our High Barrier MDO‑PE practice lead. The next 12 months will separate companies that merely discuss circularity from those that operationalize it—make 2026 the year your packaging strategy shifts from compliance risk to commercial advantage.
For detailed analysis of this topic, please visit the official page: High Barrier Mdo Pe Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com