

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Polyelectrolyte Market Set to Grow at a 5.31% CAGR During 2026–2032

Polyelectrolyte Market 2026 Strategic Outlook — Tactical Intelligence for Decision-Makers
PW Consulting’s newest market research provides a strategic roadmap for executives, investors, and technical leaders preparing for 2026 and beyond. Built on a 2025 base year and a 2020–2025 historical foundation, the study delivers a 2026–2032 forecast that is both granular and execution-oriented. At the macro level, the global polyelectrolyte market is on a steady expansion trajectory: from approximately USD 3.12 billion in 2023 to USD 3.45 billion in 2025, with a modeled compound annual growth rate (CAGR) of 5.31% that projects the market to nearly USD 4.95 billion by 2032. These headline numbers form the quantitative spine of our analysis; the remainder of the report translates them into near-term strategic actions.
Polyelectrolyte Market
The Strategic Imperative for 2026
-
From procurement to product development, 2026 will be a year in which marginal performance and supply-chain resilience determine winners. A mid-single-digit market expansion masks structural reallocation across applications, feedstocks, and geographies — dynamics that require targeted responses rather than generic volume plays.
Polyelectrolyte Market -
Key commercial and technical choices — localization of supply, premiumization of product portfolios, and alignment with tightening environmental standards — will have outsized impact on profitability given the market’s measured growth rate. The PW report converts the macro CAGR and multi-year projections into break-even matrices, margin sensitivity tables, and prioritized investment scenarios.
Polyelectrolyte Market -
Because the industry is not homogenous, 2026 is the year to choose focus: optimization (operations, cost) or differentiation (specialty chemistries, sustainability). Our findings identify which bets are likely to offer leadership-level returns within the forecast window.
What the Report Contains — Practical, Transaction-Ready Content
-
Demand and revenue model (2020–2032): a bottoms-up build that links end-market drivers to volume and pricing outcomes.
-
Scenario analysis: three forward-looking scenarios (base, upside, downside) with trigger conditions, tactical playbooks, and portfolio impact assessments.
-
Raw-material cost and pricing toolkit: sensitivity matrices that translate acrylamide and related feedstock swings into margin and contract pricing implications.
-
Manufacturing and logistics playbook: plant-utilization benchmarks, break-even scales, and recommendations for localized versus centralized manufacturing footprints.
-
Commercial acceleration assets: procurement negotiation templates, value-based pricing blueprints, and customer segmentation for premium offerings.
-
M&A and partnership framework: acquisition screening criteria, integration checklists, and synergy estimation templates for roll-ups or technology buys.
-
Regulatory and compliance matrix: jurisdiction-level obligations, compliance roadmaps, and capex implications for 2026–2028 planning.
Key Market Dynamics Shaping 2026 Decisions
-
Raw-material volatility: In 2025, regional polyacrylamide pricing exhibited divergent trends driven by demand variability and capacity moves. China saw price pressure over the year, while prices in Northeast Asia and Europe showed modest upward adjustments toward year-end. More fundamentally, acrylamide production depends on acrylonitrile — a petroleum-derived feedstock — exposing producers to crude-oil driven volatility and supply-chain shocks. Our cost models quantify the margin exposure for typical product formulations and recommend hedge ratios and contract structures for 2026 procurement cycles.
-
Regulatory tightening: Stricter wastewater discharge and chemical-safety standards are accelerating adoption of higher-performance polyelectrolytes and premium formulations that enable tighter treatment limits and easier compliance. The report maps regulatory trajectories and identifies the technical attributes buyers will demand (e.g., lower residual monomer, improved dewatering performance) and the capex implications for suppliers.
-
Demand-side shifts: Water reuse, circular-economy initiatives, and the digitalization of dosing and monitoring are changing how end-users buy chemistry — shifting value from commodity price to service, performance guarantees, and total cost of ownership. We quantify the premium pools emerging from service-oriented commercial models and the investment needed to capture them.
-
Capacity and regional competition: Capacity additions in certain markets have produced price pressure in recent cycles. Our analyses identify where overcapacity is most likely to compress margins and where differentiated chemistries will insulate pricing power.
Competitive Landscape — Players, Positioning, and Strategic Moves to Watch
The polyelectrolyte industry is characterized by a mix of global integrators, specialty chemical players, and regional producers. Overall market concentration metrics indicate meaningful space for scale players while leaving room for regional champions and specialized entrants.
-
Global leaders such as SNF Floerger, BASF SE, Kemira, Solenis, and Ecolab (Nalco Water) compete on scale, breadth of formulation, and integrated service offerings. Their common playbook is to combine large-volume manufacturing with application engineering and digital dosing capabilities — a combination that raises switching costs for large industrial customers.
-
Traditional chemical majors (e.g., Dow, Arkema) bring broad raw-material integration and global sales networks, enabling them to protect margins through sourcing advantages and portfolio bundling.
-
Regional producers and contract manufacturers — including several China- and India-based firms — emphasize cost-competitiveness and local service. Some operate high-capacity plants dedicated to commodity grades; others are pivoting toward specialty formulations to escape commodity-style margin pressure.
-
Strategic implications: Scale players will continue to invest in premium products and service models; regional players should prioritize differentiation or cost leadership. M&A is likely to feature tuck-ins that add application know-how, localized footprint, or complementary product lines.
Strategic Playbook for 2026 — Actions by Role
-
For global producers: accelerate development of higher-value formulations that reduce total-treatment costs for end users; expand digital dosing services; and selectively localize production where logistics and regulatory complexity justify it.
-
For regional producers: prioritize niche specialization (e.g., mining tailings, advanced sludge dewatering) and formalize partnerships with global players to access technology and premium customers.
-
For end-users and water utilities: renegotiate contracts to include performance SLAs and indexed pricing clauses tied to feedstock benchmarks; pilot service-based procurement models that shift supplier incentives toward performance.
-
For investors and M&A teams: focus on targets that combine application expertise with demonstrable customer retention; value extraction is highest where bolt-on acquisitions bring immediate cross-selling and procurement synergies.
-
For R&D teams: prioritize low-residual-monomer chemistries, biodegradable options where possible, and polymer formulations that reduce sludge volume and energy demand during dewatering.
How PW Consulting’s Analysis Converts Insight into Decisions
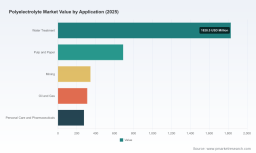
Beyond top-line projections, our report supplies the decision-support assets that convert market insight into executable plans: plant-level economics (including capex/back-of-envelope returns), customer segmentation by value-to-supplier, procurement templates indexed to raw-material cost drivers, and a time-phased investment roadmap. We intentionally keep this press briefing at a strategic level — omitting the granular segment-level tables and regional/application revenue splits that are included in the licensed report. That detailed intelligence is the fulcrum for capital deployment, pricing strategy, and M&A diligence, and it is available in the full study.
Conclusion — What Leaders Should Do Next
2026 will be a year of selective consolidation and premiumization in polyelectrolytes. With a projected mid-single-digit CAGR and a market approaching the USD 5 billion mark by the early 2030s, the opportunity is substantial but nuanced: scale still matters, but so does specialization, regulatory alignment, and service-model execution. PW Consulting’s report is designed to shorten the path from insight to decision — providing the playbooks, models, and risk matrices that corporate leaders need to allocate capital, negotiate contracts, and prioritize R&D for maximum return.
To access the full dataset, segmented forecasts, supplier scorecards, and downloadable toolkits that underpin these conclusions, request the complete Polyelectrolyte Market Report and executive dashboards from PW Consulting’s publications page or contact our advisory desk for a briefing tailored to your strategic questions.
For detailed analysis of this topic, please visit the official page: Polyelectrolyte Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com