

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Palm Kernel Shells Biomass Market to Expand at 8.5% CAGR, Reaching USD 2.32 Billion by 2032

Palm Kernel Shells Biomass Market: Strategic Imperatives for 2026 — PW Consulting Insights
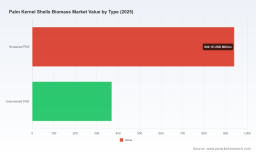
PW Consulting’s latest Palm Kernel Shells (PKS) Biomass Market report, with a 2025 base year and forecast horizon through 2032, is designed as a decision-useful tool for energy executives, commodity traders, project financiers and procurement leads preparing for a pivotal 2026. Our analysis shows the PKS market expanding from roughly USD 820.5 million in 2020 to about USD 1,310.0 million in 2025, and on a path to near USD 2.32 billion by 2032 — an 8.5% compound annual growth rate across the forecast period. This briefing outlines why the 2026 planning cycle requires recalibrated commercial strategies and what practical intelligence the full report delivers to support those choices.
Palm Kernel Shells Biomass Market
Why 2026 Is a Strategic Inflection Point
-
Policy and market demand are aligning. Accelerated decarbonization targets in major energy-consuming economies, combined with incentives for biomass co-firing and renewable power, are translating into steadier off-take commitments and longer lead-time purchase agreements. For buyers and suppliers alike, 2026 will be the year when short-term spot behavior gives way to contract portfolios that favour sustainability-compliant volumes.
Palm Kernel Shells Biomass Market -
Supply-side volatility is resurfacing as a commercial risk. Recent national measures — including Indonesia’s export tax framework tied to palm oil reference prices and additional levies, and Malaysia’s upward adjustment of export service tariffs — increase landed cost uncertainty for international buyers and nudge marginal supply back to domestic markets or higher-margin export channels.
Palm Kernel Shells Biomass Market -
Certification and traceability are non-negotiable for premium markets. Green Gold Label (GGL) and equivalent sustainability credentials are already gateway requirements for buyers in Japan, and will be a central negotiation point in long-term supply agreements. Firms without certified sourcing pathways risk price discounts or exclusion from priority tenders.
-
Consolidation signals and capacity moves are accelerating. Visible industry activity — from capacity expansions to multi-year offtake MOUs — indicates that incumbent suppliers and strategic entrants are racing to lock export-eligible, certified volumes ahead of anticipated demand growth.
What the Report Delivers — Practical, Actionable, and Ready for 2026
Our report is structured for immediate application in commercial planning and investment decision-making. Key deliverables include:
-
Robust market sizing and forward-looking scenarios. We provide a base model calibrated to 2020–2025 historicals and three stress-tested demand trajectories through 2032. The headline projection uses an 8.5% CAGR, but embedded scenario tools quantify downside risk (policy rollback, logistical disruption) and upside sensitivity (accelerated co-firing mandates).
-
Supply-chain heat maps and trade-flow analytics. Interactive modules identify chokepoints, principal export hubs, and seaborne routing options that materially affect freight lead times and landed price volatility — essential for procurement scheduling and LNG/coal co-firing retrofit planning.
-
Price benchmarking and procurement playbooks. We provide normalized pricing series, delivered-cost models, and sample contract terms that illustrate how to structure indexed contracts (CPO-linked, fixed+variable blends), credit support, and quality acceptance clauses that reflect real-world vessel sampling and moisture/ash tolerances.
-
Supplier scorecards and counterparty risk matrices. Each major supplier is assessed across production footprint, certification status, export compliance history, balance-sheet resilience and logistics competence — enabling prioritization in multi-supplier sourcing strategies.
-
Technical dossiers and combustion compatibility guidance. Concise engineering notes cover typical PKS fuel specifications (net calorific value, moisture, ash content) and co-firing integration considerations — essential when evaluating boiler modifications or switchgear tolerances.
-
Investment and M&A playbook. For investors, we include valuation benchmarks, capex/opex reference models for processing plants, and acquisition checklists tuned to the sector’s operating realities and regulatory exposures.
Competitive Landscape: What We Observed and What it Means
The PKS supply base remains commercially active but not fully consolidated. Our concentration analysis indicates the top three players account for roughly one‑third of market share, while the top five approach close to half — a structure that supports both continued competition and selective consolidation. Implications for market participants include:
-
For buyers: diversify counterparty exposure while prioritizing certified suppliers. Large suppliers are expanding capacity and securing multi-year offtakes; smaller suppliers can offer flexibility but may struggle to meet certification and volume stability requirements for premium markets.
-
For suppliers: scale and traceability are key differentiators. Recent corporate moves demonstrate that investments in processing capacity and GGL-style certifications materially improve access to high-value export markets. Securing mill-level feedstock and investing in consistent sizing/low-ash processing will command a premium.
-
For investors: look for vertically integrated platforms that combine feedstock control, processing, and logistics. Entities that can internalize the supply chain reduce exposure to export levy swings and freight shocks, while certified production brings price differentiation.
Representative corporate dynamics we examined include: BIO ENECO’s recent ramp-up of processing capacity and multi-year supply agreements to premium markets; global trading houses maintaining long-term arrangements with mills to secure supply and spread delivery risk; and specialized European and Asian players emphasizing product specification uniformity and low-ash output for industrial boiler and activated carbon applications. These developments underscore a market in which strategic partnerships and certification credentials are decisive commercial levers.
Regulatory and Cost Drivers to Watch in 2026
-
Export charges and domestic levies. Recent adjustments in export taxation and service tariffs have immediate implications for international arbitrage and landed cost structures. Procurement teams must incorporate tariff scenarios into contract negotiations and cost pass-through clauses.
-
Sustainability compliance. Certification regimes are evolving; buyers will increasingly require proof of traceability, chain-of-custody and sustainability adherence. Non-compliant volumes face discounting or market exclusion.
-
Technical standardization. Expect demand for screened/graded product and tighter moisture/ash limits, especially where PKS is used in co-firing or as feedstock for higher-value conversion (charcoal, activated carbon). Investments in quality control will reduce downstream operating risk.
Top-Line Strategic Recommendations for 2026 Planning
-
Buyers: negotiate staged multi-year agreements with flexible volume bands and indexation to CPO or an agreed composite index, coupled with a spot allocation strategy to capture short-term discounts without sacrificing security of supply.
-
Suppliers: prioritize certification and capacity investments that target export-grade product streams; develop export-ready logistics hubs to shorten lead times and mitigate port-side bottlenecks.
-
Investors and lenders: stress-test asset-level returns against tariff and certification scenarios; favour assets with integrated feedstock access or long-term take-or-pay offtakes to de-risk cashflow.
-
Project developers: quantify retrofit economics for co-firing projects using a range of fuel price paths; build contractual flexibility to switch fuel blends in periods of PKS scarcity or elevated premiums.
Conclusion — The Strategic Value of the Full Report
Our Palm Kernel Shells Biomass Market report is engineered to convert market observation into executable strategy. It pairs a quantitatively robust headline forecast (2025 base, 2026–2032 horizon, 8.5% CAGR) with operational tools — pricing models, counterparty due diligence templates, risk matrices and certification checklists — that leaders can deploy immediately during 2026 planning cycles. The market dynamics we document signal selective opportunity: those who move early to secure certified supply, hedge regulatory exposure, and invest in logistics and quality control will capture disproportionate value as demand scales.
PW Consulting intentionally withholds detailed regional and application sub-breakdowns in this summary to preserve the report’s full-scope commercial intelligence for subscribers. For the complete dataset, interactive models, supplier scorecards and the detailed annexes that support 2026 decision-making, access the full report on our website or contact PW Consulting’s advisory desk for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Palm Kernel Shells Biomass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com