

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Chemical & Materials
Cobalt Market 2026: Strategic Intelligence for Boardroom Decisions
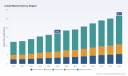
As PW Consulting’s lead industry analyst, I present an executive preview of our Cobalt Market research — a targeted, decision-focused briefing structured to help executives calibrate strategy in 2026. Built on a base year of 2025 and a historical lens covering 2020–2025, the full study projects the market across 2026–2032. Our headline finding: the global cobalt market is on a sustained growth trajectory with a compound annual growth rate of 6.69%, expanding materially from an assessed USD 16.96 billion in 2025 toward a projected market north of USD 26 billion by 2032. This preview outlines the strategic implications, competitive dynamics, and the precise operational modules included in the full report — while intentionally withholding granular segment tables and regional splits to preserve the analytic value available only in the report itself.
Cobalt Market
Why this research matters for 2026 decision cycles
-
Timing capital allocation: The medium-term growth path (2026–2032) is clear and durable, driven by electric mobility, industrial metallurgy, and high-performance applications. Boards and CFOs evaluating capex, offtake agreements, or refinery investments in 2026 need an evidence-based view of demand momentum and realistic upside scenarios. Our forecast provides that trajectory and quantifies growth sensitivity to key demand levers.
Cobalt Market -
Supply-chain resilience and sourcing strategy: Geopolitical concentration of upstream supply and concentrated refining capacity are constraining factors that can amplify price volatility and availability risk. Strategic procurement teams must weigh long-term supply contracts, backward integration, and inventory policy against heightened policy risk and trade frictions.
Cobalt Market -
M&A and partnership prioritization: With midstream and downstream pockets of value, 2026 is a year for opportunistic consolidation and strategic partnerships — particularly where firms can secure feedstock, battery-grade refinement, or end-market integration. The full study identifies the most accretive deal archetypes and valuation benchmarks.
-
Regulatory and ESG readiness: Increasing regulatory intervention, import tariffs, and scrutiny of cobalt sourcing and processing require a proactive compliance and traceability posture. Our analysis maps regulatory vectors and provides an operational readiness checklist for 2026 implementation.
Market dynamics: what the numbers reveal (and what we do not disclose here)
From a macro perspective, the cobalt market has expanded significantly during the 2020–2025 vintage years. Our base-year assessment (2025) and the forecast window (2026–2032) demonstrate a steady compound growth rate of approximately 6.69% — enough to justify multi-year investments but not so steep as to rule out meaningful substitution or efficiency gains in adjacent technologies. By 2032 the market is projected to exceed USD 26 billion, confirming a multi-billion-dollar incremental pool of demand for participants along the value chain.
What we are not publishing in this teaser are the full segment-level revenue schedules, regional and application-level percentage splits, and granular cost curves — the core analytic assets in our paid model. These withheld datasets are central to contract negotiation strategies, plant-sizing, and region-specific entry/exit decisions; they are accessible in the full briefing.
Supply-side structure and concentration
Two structural features stand out and carry immediate implications for 2026 strategy:
-
Concentration among producers and refiners: Market concentration is non-trivial — our study estimates that the top three companies control a near-majority share of the market, and the top five account for roughly 60% of global supply. For buyers, this implies counterparty concentration risk and potential price-setting dynamics that favor large incumbent suppliers.
-
Geopolitical supply risk: Recent industry reporting and public data indicate that a substantial share of mine production and refining feedstock comes from a very limited set of source countries and integrated refiners. This centralization elevates the impact of export restrictions, tariffs, and policy shifts on global availability and pricing.
These structural realities inform several high-priority actions: diversification of supplier networks, strategic inventory buffers, increased due diligence of midstream partners, and accelerated investment in processing capability outside highly concentrated basins.
Competitive landscape: profiles and strategic posture
Our research evaluates the strategic positions of major global actors. A selection of these profiles and inferred strategic implications follows.
-
Glencore (Baar, Switzerland) — A major integrated miner and trader active across nickel-copper assets and byproduct cobalt. Its diversified footprint and trading capabilities make it a pivotal swing supplier. Notably, Glencore reported full-year 2025 cobalt production of 36.1 kt, a decline versus 2024 as the company prioritized copper processing amid regional export constraints. For counterparties, Glencore’s flexibility makes it a key partner for spot and strategic purchases, but its allocation decisions can create transient supply tightness.
-
CMOC Group (Beijing, China) — A leading miner with integrated cathode and hydroxide production geared toward battery-grade markets. CMOC’s vertical integration into battery-materials production positions it as a strategic supplier for OEMs and battery manufacturers seeking secure, quality-assured feedstock.
-
Zhejiang Huayou Cobalt (Tongxiang, China) — A large refiner and precursor supplier with operations in multiple jurisdictions. Its strength lies in downstream refinement capability and established offtake relationships with battery makers; for companies requiring consistent chemical-grade material, Huayou is a go-to partner.
-
Vale S.A. (Rio de Janeiro, Brazil) — Produces cobalt as a byproduct of nickel and copper mining, offering geographic diversification to buyers. Vale’s assets provide optionality for offtake and incremental supply security outside the most concentrated mining basins.
-
BHP Group (Melbourne, Australia) — Supplies cobalt principally as a nickel byproduct and benefits from stable regulatory environments in core jurisdictions. BHP can be a strategic supplier for long-duration contracts tied to nickel-cobalt chemistry demands.
-
Rio Tinto (London, UK) — With byproduct flows from large copper operations, Rio Tinto’s role is complementary but strategically significant for customers seeking North American or diversified sourcing.
These profiles are supplemented in the full report by supplier scorecards that quantify operational scale, counterparty risk, ESG performance, and integration potential — information that underpins supplier selection and M&A screening.
Regulatory and trade environment: the 2026 playbook
Policy and trade measures have altered the operational landscape: public data show tariff adjustments and an active regulatory emphasis on traceability and import origin. Notably, recent government disclosures highlight tariff rate increases affecting ores and concentrates from certain origins and record-high mine and refinery production dynamics concentrated in a few jurisdictions. China remains the largest consumer of refined cobalt products, primarily driven by the lithium-ion battery sector, and a meaningful portion of refinery feedstock has been derived from partially refined imports from key producing countries. For corporate strategists, this means:
-
Increased compliance risk and the need to validate supply chains end-to-end.
-
Potential for sudden cost impacts due to tariff regimes or export controls that require dynamic scenario planning.
-
An incentive to localize or regionalize refining and recycling capabilities where feasible.
What’s in the full PW Consulting Cobalt Market report (operational overview)
The full deliverable is designed as a practical playbook for 2026 action, not an academic exercise. Core modules include:
-
Top-line market forecast (2026–2032) with scenario variants tied to EV adoption curves, battery chemistry transitions, and recycling uptake.
-
Supply-demand balancing by year with sensitivity runs for key shocks (export restrictions, rapid substitution, macro downturns).
-
Comprehensive supplier scorecards and a ranked watchlist for strategic partnerships or acquisition targets.
-
Price-modeling engine that decomposes landed cost by origin, processing tier, and tariff/regulatory overlay for contract negotiation support.
-
Risk matrix covering geopolitical, regulatory, ESG, technical, and reputational vectors, with mitigation playbooks.
-
Operational toolkits: negotiation templates, RFP frameworks for long-term offtake, and refinery project financial model baselines.
-
Scenario-based recommendations for OEMs, battery manufacturers, traders, and upstream miners on optimal strategies through 2032.
Immediate tactical recommendations for 2026
-
Lock in a portion of three-year supply via staggered offtake agreements to smooth price exposure while preserving spot optionality.
-
Invest in third-party supplier audits and blockchain-enabled traceability pilots to de-risk sourcing and satisfy downstream clients’ ESG demands.
-
Accelerate feasibility work on regional refining or recycling to reduce dependence on single-source refining hubs.
-
Define clear substitution thresholds and R&D milestones for cathode chemistry adjustments to keep procurement flexible.
Next steps
For executives preparing 2026 budgets, procurement strategies, or M&A pipelines, this preview should be treated as a directional roadmap. The full PW Consulting Cobalt Market report contains the actionable data feeds, segmented forecasts, supplier scorecards, and contractual templates necessary to execute the recommendations outlined here. To convert insight into advantage, access to the complete dataset and models is required — the detailed segmentation and scenario outputs are intentionally reserved to preserve their strategic value for subscribers and clients.
Contact PW Consulting to obtain the full report, interactive models, and an implementation workshop tailored to your organization’s role in the cobalt value chain.
For detailed analysis of this topic, please visit the official page: Cobalt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electrical Insulation Paper Market Poised for 3.9% CAGR Through 2032
By pmarketresearch, 2026-07-09
Electrical Insulation Paper Market — Strategic Preview for 2026 Decision-Makers
As energy systems, electrification programs, and industrial modernization accelerate globally, the humble but mission-critical category of electrical insulation paper is re-emerging as a strategic supply-chain and technology priority. PW Consulting’s new market research—anchored on a 2025 base year, five-year historical analysis (2020–2025) and a forward-looking forecast to 2032—translates market dynamics into decision-ready implications for procurement leaders, product strategists, and M&A teams planning for 2026.
Electrical Insulation Paper Market
Snapshot: Where the market stands and where it’s headed
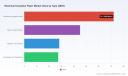
Our top-line analysis shows a resilient market trajectory. After a modest dip and recovery in the early 2020s, total market revenue reached approximately USD 172.8 Million in 2025 and is projected to grow to about USD 224.9 Million by 2032. The underlying compound annual growth rate (CAGR) over the forecast window is 3.9%, reflecting steady, structurally-driven demand rather than speculative expansion.
Electrical Insulation Paper Market
These headline numbers conceal important texture: growth is being driven by a mixture of incremental replacement demand in traditional power equipment and higher-specification requirements tied to grid modernization, increased deployment of power electronics, and stricter reliability standards in distribution and transmission assets. For executives preparing 2026 budgets, the takeaway is clear—this is a market characterized by steady, technically nuanced growth that rewards manufacturers and buyers who can master quality, compliance, and cost volatility.
Electrical Insulation Paper Market
Why this report matters for 2026 strategy
- Operational resilience: The report identifies how raw-material price volatility and compliance costs translate into margin pressure. It quantifies the material sensitivity of insulation-paper production and models scenarios that show near-term cost shocks propagating through supply chains.
- Product positioning: As transformers, capacitors, and cable systems demand ever-higher dielectric performance, product differentiation (e.g., creped vs. plain grades, coated variants, thermal upgrading) becomes the primary lever for margin expansion. The study maps which technical attributes correlate most closely with premium pricing and specification wins.
- M&A and partnership targets: With a moderately concentrated vendor base (notably, top-three and top-five shares indicating room for consolidation), the research highlights pockets of fragmented supply where acquisitive players can rapidly scale technical capability and geographic reach.
- Procurement optimization: Practical roadmaps for raw-material sourcing, hedging strategies, and contract structures are included, enabling buyers to lock in supply without sacrificing flexibility amid cyclical pulp markets.
Supply dynamics and cost pressure — what to watch in 2026
Two structural themes dominate near-term economics:
- Raw-material volatility: Kraft pulp remains the principal feedstock for cellulose-based electrical insulation papers. Recent price signals—illustrated by short-term fluctuations in pulp markets—demonstrate how quickly input cost can swing. Our modeling uses observed volatility to show that insulation-paper producers can experience up to roughly 28% variation in production cost across cycles, driven primarily by pulp price movements. We also flag that cellulose-pulp prices have risen materially (single-digit to low double-digit percentage movements) in recent production cycles, a trend that episodically compresses margins unless passed through via contracts or product premiuming.
- Regulatory and compliance overlay: Environmental controls on paper processing emit additional operating costs. Regions with strict emissions rules can impose compliance burdens that add an estimated 6–11% to operational expenditure for producers. These incremental costs influence strategic choices about plant locations, capital investments in abatement technology, and vertical integration into pulp sourcing.
Segments and technical differentiation (teaser)
The market is multi-faceted: products are optimized for transformers, cables, capacitors, and rotating machines, and come in grades such as kraft flat paper, creped and coated papers, presspaper and pressboard, and specialty capacitor tissues. Each application imposes distinct mechanical and dielectric performance criteria—creping, coating, thermal upgrading, and surface finish are not cosmetic choices but design decisions that materially affect asset lifetime and failure modes.
PW Consulting’s full report provides granular performance matrices linking technical features to typical field failure modes and lifecycle costs. This is deliberately summarized here to preserve the competitive edge the full dataset delivers; decision-makers will find the detailed matrices invaluable when optimizing design-specifications for total cost of ownership rather than first-cost alone.
Competitive landscape — who matters and why
The supplier landscape blends established specialty mills and vertically integrated European players with resilient family-owned firms in local markets. Key vendors profiled in our study include firms headquartered in Switzerland, Finland, Germany, and the United States—each bringing distinct strengths:
- Quality-driven specialty mills: Several leaders focus on electrical-grade kraft pulp processing, creping, coating and value-added finishing tailored for transformer applications. Their technical documentation and controlled production environments command trust among OEMs and asset owners.
- Brand and technical-service differentiation: Some global companies pair product families with thermal upgrading or specific processing technologies under proprietary brands, enabling clearer specification pathways for high-voltage and instrument transformer markets.
- Regional specialists and niche innovators: Long-established family manufacturers and smaller companies continue to hold meaningful positions in local and legacy markets—especially where tailored product formats (e.g., glazed variants or specialty composites) are needed.
Recent market activity also demonstrates the importance of continuous product refinement: for example, a leading supplier published updated technical guidance on optimizing transformer insulation systems in March 2026, a signal that technical leadership and customer education are core competitive tools.
Strategic implications for buyers, producers and investors
- Buyers (OEMs, utilities, EPCs): Move beyond unit-price procurement. Create multi-year specification contracts that reward suppliers for quality assurance, traceability, and guaranteed dielectric performance. Include clauses that allocate raw-material-driven cost adjustments transparently to avoid surprise shocks.
- Producers: Prioritize investments in process control, thermal upgrading capabilities, and emissions abatement. These are not marginal compliance costs but strategic enablers—facilities that achieve both tight quality control and regulatory compliance unlock premium customers and geographic expansion.
- Investors and M&A teams: The market shows moderate concentration with room for consolidation. Target acquisitions that bring complementary technical capabilities (e.g., creping/coating expertise) or access to feedstock security. The most accretive deals will improve margin resilience against pulp-price cycles and regulatory costs.
What PW Consulting’s report delivers (practical contents)
- Comprehensive historic and forecast market model (2020–2032) with scenario-ready sensitivities to raw-material price swings and regulatory cost factors.
- Technical feature-to-application matrices that map product grades to performance outcomes and lifecycle economics for transformers, cables, capacitors, and rotating machines.
- Supplier benchmarking that ranks vendors on quality control, technical services, geographic coverage, and strategic strengths—plus recent commercial and technical developments.
- Operator-focused playbooks for procurement, hedging, and specification governance that reduce total cost of ownership and failure risk.
- Strategic M&A screening criteria and a shortlist of subsegments where consolidation or capability acquisition can yield high IRR in a 3–5 year horizon.
How to use this intelligence in 2026 planning cycles
Practical steps informed by the report:
- Incorporate insulation-paper cost sensitivities into capital-cost models for transformer procurements and life-cycle cost analyses for grid assets.
- Revise supplier scorecards to weight technical conformity and emissions-compliance capabilities more heavily than price alone.
- Negotiate multi-year supply agreements with indexed cost pass-throughs and quality milestones to stabilize manufacturing throughput for both buyers and sellers.
- Prioritize investment cases for plants or upgrades that reduce exposure to pulp-price shocks and regulatory compliance risk—these investments often pay back through access to premium contracts.
Concluding perspective and next step
Electrical insulation paper is no longer a commodity relegated to procurement checklists—its quality, availability, and cost dynamics materially influence transformer reliability, capacitor performance, and the economics of power asset fleets. The market’s 3.9% forecast CAGR and the path from roughly USD 172.8 Million in 2025 toward USD 224.9 Million in 2032 indicate steady demand growth, but the real strategic battleground is margin resilience: mastering raw-material volatility, regulatory compliance, and technical differentiation.
PW Consulting’s full study contains the granular tables, country-level forecasts, product-grade economics, and supplier performance metrics that organizations need to convert this insight into 2026 action. For procurement teams, product strategists, and investors preparing budgets and deal pipelines this year, the report functions as both a risk-heatmap and an opportunity playbook.
Contact PW Consulting or visit the report landing page to access the full dataset and obtain a tailored briefing for your organization’s 2026 planning cycle. The executive summary here outlines the strategic contours—our full deliverable gives you the precise, source-level intelligence required to act with confidence.
For detailed analysis of this topic, please visit the official page: Electrical Insulation Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Hydrazine Hydrate Market at USD 280.6M in 2025 — PW Consulting Market Insight
By pmarketresearch, 2026-07-09
Hydrazine Hydrate Market 2026 — Strategic Outlook and Decision Framework
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise yet substantive preview of our Hydrazine Hydrate Market research — designed specifically to inform executive decisions across procurement, R&D, regulatory affairs, and M&A in 2026. This briefing synthesizes the market’s trajectory, structural dynamics, and the practical intelligence contained in the full study. It deliberately illustrates the analytical depth you can expect while withholding detailed segment-level financial tables and proprietary model outputs — the strategic “teaser” intended to guide you to the full report for transaction- and project-critical granularity.
Hydrazine Hydrate Market
High-level market trajectory: what the numbers mean for 2026 decisions
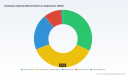
The global hydrazine hydrate market shows a steady expansion through the mid-2020s. From a baseline that rose materially across 2020–2025, the market size reached USD 280.6 Million in our base year (2025). Under our central case assumptions the market continues to expand at a compound annual growth rate (CAGR) of approximately 5.5% across the 2026–2032 forecast window, reaching an overall valuation north of USD 400 Million by the end of the horizon. This pace is consistent with a specialty-chemicals product experiencing mixed cyclical demand — solid industrial applications balanced by regulatory and logistics frictions that constrain unfettered upside.
Hydrazine Hydrate Market
For 2026 corporate planning, this implies a market environment where demand growth is reliable but not explosive. Firms should prioritize operational resilience, selective capacity investments, and downstream partnerships that capture higher-margin specialty applications rather than broad-volume plays that assume rapid commoditization.
Hydrazine Hydrate Market
Drivers shaping near-term supply and demand
- End-market mix and downstream pull: Demand is anchored in legacy industrial uses (water treatment, polymer and foam systems, agrochemical synthesis, pharmaceutical intermediates) and is being reshaped by pockets of higher technical intensity (high-purity grades for aerospace and advanced synthesis).
- Regulatory tightening: Classification and authorization requirements in major markets (notably the EU) are raising compliance costs and influencing sourcing choices, favoring suppliers that can demonstrate robust regulatory dossiers and chain-of-custody controls.
- Logistics and handling constraints: Shipping and handling standards, including insulated pressure-rated packaging and certified handlers under international transport rules, increase landed costs and favor regional supply hubs or nearshoring strategies.
- Feedstock and input inflation: Upstream feedstock cost pressures have increased production costs materially in recent periods — a factor that constrains margin expansion unless offset by product mix optimization or pass-through pricing.
Market structure and competitive landscape — how to interpret concentration metrics
The hydrazine hydrate sector is best characterized as a specialized, moderately fragmented market. Aggregate concentration metrics show that the largest few players do not dominate the sector to the degree seen in highly consolidated commodities; instead, a handful of established chemical manufacturers, particularly those with integrated synthesis capabilities and regional production assets, capture a meaningful share while a broad tail of regional producers serves local demand.
Key industry participants whose strategies merit attention include:
- Otsuka-MGC Chemical Company, Inc. (Japan): The largest global manufacturer and the sole domestic producer in Japan; its scale and domestic footprint make it a natural price-maker for Asian flows and a critical counterparty for supply continuity in the region.
- Arkema S.A. (France): A diversified specialty-chemicals group that offers hydrazine hydrate across a range of concentrations and derivatives. Arkema’s strengths are its formulation know-how and customer relationships in polymer foam and crop protection intermediates.
- LANXESS AG (Germany): A supplier with a strong agrochemical orientation and recent strategic moves into higher-purity grades aimed at aerospace and advanced industrial applications — signaling a play for margin differentiation.
- Nippon Carbide Industries, Japan Finechem, Kanto Chemical (Japan): These firms provide a mix of regional supply, technical grades, and specialty services (e.g., analytical and technical-grade products), supporting localized supply chain needs and regulatory compliance for customers in pharmaceuticals and agrochemicals.
The competitive picture is dynamic: product-quality differentiation (e.g., high-purity, aerospace-grade variants), supply security, and regulatory readiness are increasingly salient axes of competition. Recent corporate activity — product launches targeted at high-value applications and focused trade-show engagement — underscores a strategic shift from volumetric growth to capability-led differentiation.
Regulatory, safety and logistics headwinds
Regulation is a central constraint on market development and a primary driver of supplier selection:
- Hydrazine’s inclusion as a substance of very high concern in some regulatory regimes raises the cost and time-to-market for affected uses through authorization dossiers and tighter EHS controls.
- Recent alignment of domestic rules in the United States to updated international standards created near-term compliance costs — relabeling, retraining, and revised transport protocols — with ongoing implications for cross-border supply chains.
- Transport regulations under the UN model require pressure-rated, insulated packaging and certified handlers, which limits the pool of logistics providers and raises barriers to ad hoc cross-border shipments.
Companies that prioritize regulatory compliance, invest in documented stewardship programs, and develop certified logistics footprints will reduce both operational risk and the total cost of ownership for customers, creating a defensible commercial position in 2026.
Cost pressure and margin implications
Upstream feedstock inflation has been a material margin headwind, with recent periods showing a significant rise in input costs. This forces hard choices for producers: absorb margin contraction, pursue product-mix upgrades toward higher-margin specialty grades, or pass costs through — each option has different competitive and commercial consequences. Procurement leaders should stress-test supplier contracts for indexation, hedging mechanisms, and flexibility clauses as part of sourcing decisions in 2026.
Practical content of the full PW Consulting report
Our full report is structured to support immediate decision-making and project planning. It includes:
- Proprietary demand-modeling across 2020–2032 with base-year calibration to 2025 and scenario runs that reflect regulatory, feedstock, and logistics shocks;
- Price and cost decks that reconcile raw material inputs, production OPEX, and regional logistics cost components;
- Supplier and capacity maps with facility-level commentary, permitting status, and compliance readiness;
- Applications-level demand narratives (water treatment, polymerization & blowing agents, agrochemicals, pharmaceuticals, and others) with qualitative substitution and elasticity analysis — note: detailed segment-level value tables are available in the premium dataset;
- Regulatory impact assessment and a practical compliance checklist for market entry and product stewardship programs;
- An actionable M&A and partnership playbook: screening criteria for targets, indicative valuation sensitivities given feedstock and regulatory risk, and integration checklists;
- Scenario-driven go-to-market recommendations for producers and downstream buyers, including procurement contracting templates and a supplier-risk matrix;
- Executive-ready slide sets and editable data extracts to embed in board materials or investor decks.
How to use this intelligence in 2026 — four priority actions
- For producers: prioritize investments in higher-purity product lines, regulatory dossier completion, and certified logistics to capture premium end-markets. Defer greenfield capacity focused purely on volume unless backed by long-term offtake.
- For buyers/procurement: rebalance sourcing toward suppliers that combine price competitiveness with demonstrated regulatory robustness and logistics certification; negotiate clauses that mitigate feedstock inflation through shared-index mechanisms or measured pass-throughs.
- For M&A and private equity: target niche, regionally entrenched assets with clean regulatory records and technical-grade capabilities; valuation multiples must explicitly account for authorization risk and potential capex to meet higher-purity specifications.
- For R&D and product teams: accelerate workstreams that enable substitution into higher-value applications and explore formulation strategies that reduce hydrazine load while retaining performance to avoid regulatory bottlenecks.
Risk framework — exposures to monitor
Key risks that will affect strategy in 2026 include regulatory authorization outcomes in major markets, sudden feedstock price spikes, disruptions to certified logistics capacity, and technological substitution in downstream formulations. Our report provides a quantified risk matrix and mitigation playbook tailored to each stakeholder group.
Next steps — where to find the granular intelligence
This preview outlines the strategic contours and practical imperatives that PW Consulting’s Hydrazine Hydrate Market report delivers. The full study contains the segment-level revenue tables, regional and application splits, supplier facility maps, and the proprietary scenario models that are intentionally omitted here to preserve the value of the primary dataset. For procurement tenders, M&A diligence, or capital expenditure approvals in 2026, those dataset elements are the operational inputs you will need.
Contact PW Consulting to request the complete report package, which includes editable data extracts, scenario-model access, and a one-hour briefing with our lead analysts to align the findings to your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Hydrazine Hydrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Pharma-Grade Sodium Chloride Market to Reach USD 630M by 2032, 5.6% CAGR (PW Consulting)
By pmarketresearch, 2026-07-09
Pharmaceutical Grade Sodium Chloride Market: Strategic Primer for 2026 Decision-Makers
As healthcare systems normalize post‑pandemic and manufacturers recalibrate supply chains, pharmaceutical grade sodium chloride has re‑emerged as a quietly critical commodity underpinning therapies, diagnostics and life‑saving procedures. This primer synthesizes the key market dynamics from PW Consulting’s new study (base year 2025) and frames the concrete strategic choices executives must make in 2026. It demonstrates the analytical depth available in the full report while intentionally withholding detailed sub‑segment tables and regional breakouts to preserve the value of the underlying intelligence.
Pharmaceutical Grade Sodium Chloride Market
Market trajectory at a glance
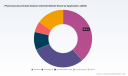
The market for pharmaceutical grade sodium chloride has expanded steadily through the historical window (2020–2025), moving from an estimated USD 470.0 Million in 2020 to USD 525.0 Million in the base year 2025. PW Consulting’s forecast for 2026–2032 models a compound annual growth rate (CAGR) of 5.6%, projecting continued expansion to an estimated USD 630.0 Million by 2032. This secular growth is underpinned by rising procedural volumes in mature health systems, expanding dialysis and injectable drug markets in growth regions, and an elevated emphasis on pharmaceutical‑grade raw materials driven by regulatory scrutiny and patient safety demands.
Pharmaceutical Grade Sodium Chloride Market
Why this matters for 2026 strategic planning
-
Supply resilience is no longer optional. The 5.6% forecast CAGR implies meaningful incremental demand that will collide with constrained processing capacity and quality‑assured supply chains. Firms that secure validated, multi‑sourced supply lines and invest in buffer inventories will avoid margin‑eroding disruptions.
Pharmaceutical Grade Sodium Chloride Market -
Quality and compliance are premium drivers. Regulatory expectations for pharmaceutical excipients and APIs are tightening. Manufacturers and contract buyers must architect traceable processes, third‑party audit readiness and documentation ecosystems that differentiate their products in tender processes.
-
Commercial negotiations will hinge on value‑added services. Buyers are increasingly purchasing “assurance” — validated supply, chain transparency, and packaging/sterilization options — not simply commodity salt. Suppliers that bundle technical support, certification, and logistics will command better economic terms.
-
Medium‑term investment choices (2026–2028) are pivotal. Decisions on capacity additions, greenfield vs brownfield projects, and automation will determine market positioning for the majority of the forecast period. PW Consulting’s scenario models show that early movers who calibrate capacity to projected demand corridors capture disproportionate share with limited price concessions.
Data‑driven implications for different business functions
-
Procurement: Shift from single‑source contracts to a tiered, qualification‑based supplier portfolio. Introduce contractual KPIs for lead times, batch release, and recall response, and price mechanisms that reflect service components.
-
Manufacturing & Quality: Prioritize investments in analytical capacity (impurity profiling, particulate monitoring) and batch release automation. Prepare for increased regulatory audits and expand documentation control to support cross‑border distribution.
-
Commercial: Reframe value propositions — sell risk mitigation and compliance as much as volume. Tender strategies should weigh lower unit costs against supplier resilience and service guarantees.
-
M&A & Corporate Development: The market’s moderate concentration profile creates opportunities for bolt‑on acquisitions that expand geographic coverage, technical capabilities, or API credentials.
Report highlights — what the full study delivers (practical, deal‑ready outputs)
-
Demand forecasting and scenario planning for 2026–2032 with sensitivity analyses across macro, regulatory and clinical adoption levers.
-
Detailed supplier assessment framework and benchmarking templates to expedite vendor qualification and risk scoring.
-
Commercial playbooks tailored to buyers and sellers: tender construction, price indexation clauses, and logistics optimization strategies.
-
Capex decision support: cost‑benefit models for capacity expansion, including break‑even timelines under conservative and aggressive demand scenarios.
-
Regulatory & quality readiness checklist aligned to FDA, EMA and major emerging market authorities, enabling faster market entry and fewer audits.
-
Consumer safety and sustainability pathway: roadmaps to reduce carbon intensity of salt production, water management best practices, and end‑to‑end traceability blueprints.
Competitive landscape — contours and strategic moves
The pharmaceutical grade sodium chloride market remains fragmented by design: a mix of global chemicals companies, regional salt specialists and life sciences suppliers. Aggregate concentration metrics indicate that leading groups do not overwhelmingly dominate — a structural feature that preserves negotiation leverage for well‑organized buyers and creates acquisition openings for strategic consolidators.
-
K+S Aktiengesellschaft (Germany): A vertically integrated player with deep experience in mining and processing. Their strengths are consistent raw material access and scale in bulk operations. Strategic focus for 2026 should be on converting industrial scale into pharma‑grade throughput via enhanced purification lines and pharmaceutical QA systems.
-
Nouryon (Netherlands): A specialty chemicals incumbent with global distribution and technical service capabilities. Nouryon’s advantage lies in formulation know‑how and regulatory familiarity — assets that facilitate partnerships with injectable and dialysis solution manufacturers.
-
Tata Chemicals Ltd. (India): A low‑cost producer with regional reach and experience across food and industrial sectors. For 2026, opportunities include upgrading facilities to meet pharma GMP, and leveraging domestic contract manufacturing growth.
-
Dominion Salt Ltd. (Canada): A producer whose market position is strengthened by regional logistics and stable feedstock. Their strategic play is to offer near‑market supply resilience and to target adjacent life‑science customers requiring tight lead times.
-
Cargill (Salt Business, USA): A global CPG and ingredient giant with strong customer relationships across healthcare and nutrition. Cargill’s distribution network and quality systems enable it to be a preferred supplier for multinational pharmaceutical manufacturers.
-
Salinen Austria AG & Sudsalz GmbH (Austria & Germany): European salt specialists with longstanding production assets. Their niche is high‑purity crystalline salt and regional regulatory know‑how — attractive to European pharma customers prioritizing short, controlled supply chains.
-
Cheetham Salt (Australia) & Compass Minerals (USA): Producers with logistics and bulk supply advantages. Their strategic differentiation rests on export capabilities and the ability to serve both industrial and pharma verticals by dedicating GMP lines.
-
Swiss Saltworks: A smaller, specialty supplier able to offer tight traceability and tailored packaging solutions for sensitive applications.
-
Merck KGaA & Spectrum Chemical (Germany & USA): Life‑science oriented suppliers that bridge commodity supply and application support. They possess distribution channels into clinical and research labs, making them credible partners for high‑margin pharma uses.
-
Hubei Xingfa Chemicals Group (China): A high‑volume producer with strong manufacturing scale. Their growth vector is serving local API and contract manufacturing hubs while investing selectively in GMP upgrades for export markets.
Across these players, three strategic fault lines define competition in 2026: (1) quality and compliance versus cost leadership, (2) global scale and distribution versus regional responsiveness, and (3) sustainable production credentials as a differentiator for sophisticated buyers.
Recommended strategic moves for 2026
-
For suppliers: Prioritize certification roadmaps (GMP, ISO and client‑specific standards), modularize capacity to support both large‑volume contracts and high‑margin small‑batch production, and develop transparent chain‑of‑custody reporting to command premium pricing.
-
For buyers: Implement multi‑tier sourcing with contractual service level metrics, invest in supplier development programs to uplift capability in strategic regions, and adopt hedging or collaborative inventory models to smooth price and availability volatility.
-
For investors/M&A teams: Target regional leaders with strong quality credentials or smaller specialists with proprietary purification technologies that can be scaled through capital and distribution assets.
-
For policy and sustainability officers: Begin capital projects and supplier dialogues that reduce freshwater usage and energy intensity — both regulatory risk and buyer preference are converging on environmental performance.
Methodology & confidence intervals
PW Consulting’s analysis uses a bottoms‑up synthesis of historical consumption (2020–2025), industry audit trails, company disclosures, and proprietary channel checks. The base year is 2025 (USD, revenue unit: Million). Forecasts for 2026–2032 reflect a central scenario at a 5.6% CAGR with alternate upside and downside pathways modeled for policy shifts, major capacity additions, or abrupt clinical demand changes. Where the market shows fragmentation, concentration ratios were computed to assess competitive intensity and acquisition potential.
Conclusion — next steps for executives
Pharmaceutical grade sodium chloride presents a classic strategic choice: treat it as a routine commodity or recognize it as a mission‑critical input whose availability, quality and provenance materially affect product safety, regulatory compliance and economics. PW Consulting’s full report transforms that choice into operationally actionable plans — detailed supplier scorecards, capex calculators, and regulatory readiness templates that executives can deploy immediately. The executive summary here is a preview of the decision‑grade intelligence behind the paywall; for the granular regional, application and company segment data that will shape contracting and investment rounds in 2026, consult the full study.
For detailed analysis of this topic, please visit the official page: Pharmaceutical Grade Sodium Chloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PVB Film Market to hit USD 344.8M by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-09
PVB Film Market Outlook — Strategic Imperatives for 2026 Decision Makers
As PW Consulting’s lead industry strategist, I present a forward-looking briefing drawn from our new PVB Film Market study — an operationally focused intelligence product designed to inform boardroom decisions in 2026. This executive “trailer” synthesizes the macro trajectory, competitive shifts, and strategic levers that will determine winners and laggards in laminated interlayers over the next investment cycle. It intentionally surfaces the analysis framework and actionable takeaways while withholding granular segment and regional splits to encourage direct access to the full dataset and model.
PVB Film Market
Executive snapshot: growth, structure, and pace
The global PVB film market reached a material scale by the 2025 base year and, after pandemic-era volatility, is positioned for steady expansion through our forecast window. Our topline model projects a compound annual growth rate of approximately 6.98% from the 2026 base into the 2032 horizon, reflecting sustained demand across safety glass, architectural innovation, and emerging photovoltaic applications. The market is also structurally concentrated: the three largest suppliers command the majority of market influence, and the top five players consolidate most commercial capacity — a dynamic that creates both stability and strategic friction for newcomers and mid-market producers.
PVB Film Market
Why this study matters for 2026 strategic choices
- Capital allocation timing: With mid-single-digit CAGR and visible policy-driven tailwinds for sustainable materials, the next 12–24 months are pivotal for committing greenfield expansions, retrofitting lines for recycled-content PVB, or negotiating offtake terms. Missed timing reduces the optionality premium embedded in later-cycle demand surges.
- Supply-chain positioning: Inputs and energy are major drivers of margin variability. Our report quantifies raw-material exposure and offers hedging and supplier-contract archetypes that protect margin without forfeiting growth.
- Product roadmap alignment: Innovations in stiffness, optical effects, and recycled-resin content are already reshaping procurement specifications across automotive and architectural OEMs. Firms that translate material technology into validated safety and aesthetic claims will capture premium pricing bands.
- M&A and partnerships: High concentration creates opportunities for bolt-on consolidation, regional capability plays, and joint ventures that provide rapid access to certification and OEM contracts. The report’s candidate-screening engine accelerates target identification based on technological fit and balance-sheet thresholds.
- Regulatory and ESG compliance: Certification regimes and decarbonization mandates materially affect contract viability. Early certification (or rapid roadmap implementation) for recycled-content and low-carbon production de-risks long-term revenue and unlocks sustainability-linked incentives.
Demand drivers and supply dynamics — what to watch in 2026
Three convergent forces underpin the market’s trajectory:
PVB Film Market
- End-market innovation: Automotive safety regulations, architectural design trends favoring large-format glazing and minimal profiles, and nascent PV module laminates are each expanding technical requirements for interlayers. These use-cases place different emphases on optical clarity, structural stiffness, and durability — pressuring producers to broaden product portfolios or specialize for higher-margin niches.
- Sustainability and certification: Buyers and regulators are accelerating material-quality demands. Industry-leading suppliers have already announced recycled-content PVB offerings and secured third-party sustainability certifications, creating a bifurcated market between certified low-carbon products and conventional grades. Certificate-backed supply is becoming a procurement precondition for major OEMs and façade contractors.
- Raw material and energy volatility: Cost exposure is non-trivial — key feedstocks and energy inputs can swing margins sharply. Some producers are actively deploying derivatives and long-term procurement contracts to smooth cost profiles; others remain exposed, creating differentiated margin outcomes that will show up in financial results and competitively significant pricing moves.
Competitive landscape — capabilities, bets, and recent moves
The market’s leading players combine global manufacturing footprints, brand recognition, and long-term OEM relationships. Four archetypes illustrate strategic divergence:
- Global integrators — Firms that combine resin production, interlayer manufacture, and multi-market distribution. These players leverage scale to invest in certification, recycled-content offerings, and regional service models that OEMs require for just-in-time supply.
- Product innovators — Companies focused on differentiated interlayers (e.g., enhanced stiffness, visual effects) that command specification preference in architectural marquee projects and safety-critical automotive applications.
- Regional specialists — Producers that concentrate assets in select geographies to serve local energy, regulatory, or logistics advantages; they are attractive partners or acquisition targets for global players seeking faster market entry.
- Niche premium brands — Small but high-margin firms that target design-oriented architectural projects with unique finishes and optical effects.
Recent commercial moves illustrate these archetypes in action: several major suppliers have commercialized next‑generation interlayers with improved structural performance and novel aesthetic finishes. Others have announced low‑carbon product variants that incorporate recycled resin inputs and/or migrate production to renewable energy sources. Certification wins and product launches in 2024–2025 signal that sustainability credentials and technical differentiation will be decisive procurement filters in 2026.
Operational implications: procurement, manufacturing, and R&D
For commercial and operations leaders, the study translates macro insights into specific levers:
- Procurement redesign: Move from spot buying to blended contracting: a mix of long-term fixed-price supply for critical feedstocks, indexed volumes for flexibility, and optionality for recycled-content streams. The report provides contract templates and elasticity curves to quantify the trade-offs.
- Manufacturing roadmaps: Prioritize retrofits that enable higher recycled-content runs without sacrificing optical quality, and modularize investments so scale can be accelerated if demand trajectories exceed base-case assumptions.
- Product differentiation: Invest in a tiered product architecture — standard grades for cost-sensitive volumes, high-performance grades for margin capture, and certified low-carbon SKUs for sustainability-driven tenders.
- Channel and service models: OEMs increasingly value certified, traceable supply chains and product-testing support. Building capabilities in technical support, on-site testing, and logistics reliability is a low-cost route to win share.
Scenario thinking: timing your moves under three plausible futures
Our forecast framework uses a three-scenario approach to stress-test timing decisions:
- Base Case (reference): Reflects continued mid-single-digit expansion driven by steady automotive and architectural demand and measured adoption in PV applications. This scenario supports deliberate capacity additions phased against validated offtake.
- Sustainability Upside: Accelerated policy adoption and rapid OEM procurement shifts toward certified recycled-content and low-carbon PVB. Under this path, early movers with certified supply unlock premium price realization and faster volume growth — justifying earlier and larger capacity investments or strategic acquisitions.
- Downside / Volatility: Raw-material shocks, adverse currency movements, or delays in certification adoption compress margins and delay pickup in discretionary architectural projects. In this case, operational flexibility and hedging discipline preserve cash and maintain service levels while avoiding margin-diluting spot sales.
Each scenario includes triggers and tactical playbooks — the full report maps those triggers to decision gates for capital projects, procurement commitments, and M&A timelines.
What the full PVB Film Market report delivers
PW Consulting’s full study is built as a decision-support suite for executives and investors. Key deliverables include:
- Granular market model and dashboard (2020–2032) with downloadable scenarios and sensitivity toggles.
- Competitive matrix and supplier scorecards covering technology, certification, capacity, and regional footprint.
- Detailed supply-chain maps with raw-material exposure analysis and hedging strategies.
- Commercial playbooks: pricing levers, contract templates, and channel strategies tailored to OEM and architectural buyer archetypes.
- M&A and partnership shortlist methodology with candidate filters and valuation ranges (confidential annex available).
- Regulatory and certification roadmaps, including timelines and expected cost implications for certification programs relevant to low-carbon and recycled-content claims.
- Implementation roadmaps for manufacturing retrofits to accommodate recycled-content blends and high-performance grades.
To preserve the strategic advantage for paying subscribers and corporate clients, the preview above intentionally omits detailed regional and application splits and the specific revenue breakdown by subsegment — those are provided in the interactive model and appendices of the full report.
How PW Consulting supports execution
Beyond research, PW Consulting partners with clients to translate insight into outcomes: we co-develop capex timing decisions, run procurement optimization pilots, structure JV and M&A diligence, and validate product commercialization plans with OEM procurement teams. Our modular engagement templates let clients buy only the parts they need — from a rapid 8-week market-entry feasibility to a full-scale program that embeds PW leaders in your capital approval and supply-chain negotiations.
For executives making 2026 decisions, the strategic choices are straightforward in concept but complex in execution: align product strategy with certified supply, lock cost exposure on critical feedstocks, and time capacity moves to where demand and value converge. The PVB Film Market study arms you with the quantitative models, supplier intelligence, and scenario playbooks to make those choices with conviction.
Access the full report and the interactive market model on our publications page to unlock the complete dataset, subsegment detail, and operational templates.
For detailed analysis of this topic, please visit the official page: PVB Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hydrogen Peroxide Market to Grow at 5.2% CAGR Through 2032
By pmarketresearch, 2026-07-09
Hydrogen Peroxide Market — Strategic Imperatives for 2026 Decision‑Makers
As PW Consulting’s senior industry analyst, I present a concise, decision‑focused preview of our new Hydrogen Peroxide Market study. This briefing synthesizes the macro trajectory, competitive moves, regulatory shocks and practical decision tools that corporate leaders will need in 2026. It highlights why hydrogen peroxide (H2O2) is rapidly re‑shaping upstream capital plans, specialty product strategies and procurement playbooks — and why leaders must act now. The market grew from roughly USD 3,073.5 Million in 2020 to about USD 3,624.4 Million in 2025 and, under our base forecast, is on course to reach approximately USD 5,096.5 Million by 2032, reflecting a compound annual growth rate of 5.2% across the 2026–2032 forecast window.
Hydrogen Peroxide Market
Why this study matters for 2026 strategic decisions
- Demand momentum is shifting from commodity bulk to value‑added, low‑carbon and super‑pure grades. That changes margin pools, qualification cycles and capital intensity.
- Recent capacity projects and joint ventures in Asia are remapping the supply map for high‑purity and specialty grades — creating both opportunity and risk for Western producers and buyers.
- Regulatory uplifts and food‑use clarifications have real commercial consequences for producers, formulators and food processors that rely on H2O2 as an antimicrobial, bleaching and oxidizing agent.
- Market concentration is material but not prohibitive: the sector shows a notable share held by top players, leaving room for niche specialists and M&A to reshape regional balances.
- Price and feedstock volatility (energy, hydrogen availability, and catalyst/chemical intermediates) require new contracting and hedging approaches beyond spot purchasing.
Market trajectory — what the headline numbers tell you
The market’s historical climb from USD ~3.07 billion in 2020 to about USD 3.62 billion in 2025 reflects resilient end‑market demand: traditional users such as pulp & paper and textiles remain important, while growth pockets have emerged in electronics, photovoltaics, water treatment and healthcare/disinfection. Our forecast to 2032 captures both baseline industrial demand and accelerated adoption in specialty segments driven by semiconductor and solar wafer fabrication, alongside incremental volumes from regulatory approvals for food uses.
Hydrogen Peroxide Market
Interpreting the 5.2% CAGR: this is not uniform growth across all grades or regions. Instead it signals services and product bifurcation — steady demand for established industrial grades contrasted with faster expansion for high‑purity and low‑carbon solutions. For corporate planners, the CAGR therefore implies two concurrent strategic imperatives: 1) protect commodity margins through operational efficiency and integrated procurement; and 2) pursue higher‑margin differentiation where technical qualification and secure offtake create durable pricing power.
Hydrogen Peroxide Market
Competitive landscape — who’s shaping supply and capability
The industry is composed of global incumbents with integrated capacities and a cohort of regional specialists. Top strategic archetypes we track:
- Global integrated majors scaling specialty and electronic grades through capacity expansion and JV activity.
- Regional producers capturing local industrial demand and cost advantages in feedstock‑intensive applications.
- Specialty players and super‑pure manufacturers focusing on semiconductor and photovoltaics where qualification barriers are high.
Key corporate moves to watch (recent, verified):
- Solvay: completed a major expansion in Zhenjiang (China), substantially increasing production capacity for high‑purity electronic‑grade hydrogen peroxide to address semiconductor demand. That move recalibrates supplier options for Asian device manufacturers and intensifies competition on quality and logistics.
- Evonik: in partnership with Fuhua Tongda Chemicals, started trial production at a Leshan (China) specialty‑grade facility, with full operations expected in mid‑2026 to serve photovoltaics, semiconductors and food‑contact applications.
- Nouryon: launched a low‑carbon hydrogen peroxide product (Eka® HP Puroxide™), signalling that decarbonized product lines are becoming commercially available and marketable differentiators rather than niche R&D topics.
- Mitsubishi Gas Chemical: remains the market leader in super‑pure segments, a critical supplier to semiconductor fabs and electronics supply chains.
These moves underscore three strategic tensions for market participants: scale versus specialisation, localised supply security versus global optimisation, and carbon intensity versus cost competitiveness.
Regulatory and demand shocks to factor into 2026 planning
- Regulatory change: On September 3, 2025, the FDA amended food additive regulations for hydrogen peroxide, expanding permitted food uses and removing certain restrictions. This materially alters the addressable market for food processors and ingredient suppliers who can qualify H2O2 within food manufacturing processes.
- Procurement & qualification timelines: semiconductors and photovoltaics require lengthy qualification; new capacity can take quarters to meaningfully relieve supply tightness despite construction completion.
- Environmental policy and decarbonisation incentives: product lines labelled as “low‑carbon” command new buyer interest and potentially pricing premiums from sustainability‑driven customers and procurement standards.
What the PW Consulting report delivers — practical tools and coverage
We designed the study for executable decisions. Highlights within the full report (operational and advisory outputs):
- Detailed market sizing and growth drivers (historical 2020–2025 and forecast 2026–2032) with sensitivity testing across macroeconomic and end‑market scenarios.
- Plant‑level capacity map, utilisation analysis and a timeline of announced, under‑construction and planned projects. (Note: this preview deliberately omits plant‑level figures — full dataset available in the report.)
- Company profiles and competitive scorecards for global and regional producers, including strategy, product portfolio (commodity vs specialty), sustainability initiatives, and recent M&A/activity trackers.
- Supply chain and logistics risk matrix: feedstock exposure, energy intensity, shipping/warehousing constraints and contingency planning for supply disruptions.
- Commercial playbooks: procurement contracting templates, sample offtake structures for specialty grades, price pass‑through models and margin protection strategies.
- Regulatory impact assessment aligned to recent FDA amendments and regional chemical policy scenarios, with compliance timing and cost estimates.
- Strategic M&A and JV screening frameworks to identify attractive targets by technology, geography and capacity vintage.
- Comprehensive Excel datasets and model access for client bespoke scenario runs.
Scenario lenses & recommended strategic pivots for 2026
- Base Case (reference): steady industrial demand with specialty outperformance — actions: optimise cost to defend commodity margins and selectively invest in specialty grade qualification.
- Electronics/PV Upside: accelerated fab/solar capacity leads to tight super‑pure demand — actions: secure long‑term offtake agreements, prioritise supply to high‑value customers, and accelerate qualification pipelines.
- Low‑Carbon Premium: corporate and procurement buyers pay premiums for verified low‑carbon H2O2 — actions: invest in low‑carbon production or partner with low‑carbon suppliers; quantify premium vs incremental cost.
- Regulatory Expansion: expanded food and pharmaceutical uses following enforcement updates — actions: fast‑track regulatory approvals and expand food‑grade production lines where cost‑effective.
- Supply Disruption: feedstock/energy shocks or logistics disruptions — actions: diversify suppliers regionally, increase buffer inventories for critical grades, and adopt flexible contracting.
Top priority actions for executives in 2026
- Stress‑test supplier dependencies by grade and region; create a prioritized mitigation plan for super‑pure and low‑carbon shortages.
- Negotiate a portfolio of contracting approaches (short‑term spot, intermediate‑term indexed, and long‑term fixed offtakes) tailored to grade and strategic value.
- Invest in product qualification for high‑purity and low‑carbon grades today — the sales lead time to realize margin uplift is measured in quarters, not weeks.
- Assess strategic partnerships or minority equity positions in regional capacity projects as a faster alternative to greenfield build‑out.
- Embed regulatory monitoring into commercial planning: the FDA amendment in 2025 is a live example of how rules can expand addressable markets overnight.
Why PW Consulting’s study is indispensable for 2026
For leadership teams evaluating capex, M&A, supply contracts, product roadmaps or procurement strategies, the value of timely, granular and executable intelligence cannot be overstated. This preview demonstrates the analytical depth we bring — but, in keeping with a “trailer” approach, we have intentionally withheld the granular segmentation tables, plant‑level capacities and certain proprietary model outputs that clients use to make binding investment and commercial decisions.
To access the full data‑rich report, plant‑level capacity maps, company scorecards, regulatory impact models and downloadable Excel workbooks that support 2026 decision cycles, consult the PW Consulting Hydrogen Peroxide Market study page. The full study provides the exact metrics, split analyses and model granularity needed to convert strategic options into executable plans.
For detailed analysis of this topic, please visit the official page: Hydrogen Peroxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sodium Permanganate Market to Grow at 4.6% CAGR Through 2032
By pmarketresearch, 2026-07-09
Sodium Permanganate Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a focused, decision-grade briefing on the sodium permanganate market that frames the strategic choices organizations will face in 2026. This market is no longer a niche chemical business insulated from broader industrial trends — it sits at the intersection of water infrastructure, semiconductor and electronics manufacturing, and evolving battery- and critical-materials policy. The briefing that follows synthesizes our market sizing, competitive mapping, supply-chain stress testing, and scenario-driven recommendations. It is designed to signal the levers that matter to procurement, commercial strategy, operations, and M&A teams while deliberately withholding full segment-level detail to encourage access to the full PW Consulting report.
Sodium Permanganate Market
Market snapshot: scale, trajectory, and concentration
Using 2025 as the base year, our topline market model values global sodium permanganate demand at approximately USD 357.7 Million (USD Million). The market is projected to expand to roughly USD 379.9 Million in 2026 and to approach USD 488.0 Million by 2032, implying a compound annual growth rate (CAGR) of 4.6% over the 2026–2032 forecast horizon. These figures reflect a steady expansion driven by sustained municipal water-treatment procurement, growth in specialty industrial applications, and incremental gains in electronics and high-purity use cases.
Sodium Permanganate Market
Market structure matters: the industry shows a high degree of concentration (CR3 ≈ 70%; CR5 ≈ 75%), which shapes competitive dynamics, pricing behavior, and the speed at which supply shocks are transmitted to end markets. For corporate decision-makers, this concentration implies that a relatively small set of incumbent suppliers will continue to set commercial norms — but it also creates pockets of opportunity for differentiated entrants and vertically integrated players.
Sodium Permanganate Market
Why 2026 is a pivotal year for strategic choices
- Procurement inflection: Recent upstream volatility has shortened suppliers’ planning cycles and increased the value of contract certainty. Buyers who act early to secure flexible, indexed contracts will reduce margin exposure.
- Regulatory realignments: New critical-materials rules and public investment programs are shifting the economics of manganese sourcing and downstream processing, creating both compliance burdens and investment incentives.
- Demand mix evolution: While water treatment remains the backbone of demand, higher-value segments — notably electronics and research-grade supplies — are growing faster and require different quality, packaging, and service models.
Key market dynamics shaping 2026 decisions
- Raw material tightness and cost pass-through: Price volatility at the manganese sulfate and ore level has become a persistent theme. Q1 2026 data showed a notable quarter-over-quarter uptick in manganese sulfate pricing linked to rising sulphuric acid costs. That spike, combined with legacy supply disruptions (for example, mine suspensions following severe weather events in 2024), has amplified input-cost transmission into finished sodium permanganate prices.
- Policy and strategic-materials pressure: The European Union’s Critical Raw Materials Act (effective May 2024) explicitly flagged high-purity manganese as strategic, creating compliance and sourcing implications for anyone competing in EU markets. At the same time, U.S. Department of Energy and Department of Defense grant programs supporting domestic battery-grade manganese production are altering the competitive landscape for manganese feedstocks, potentially diverting material and investment into the battery supply chain.
- Public procurement as a demand anchor: Municipal tendering remains a stable and predictable revenue channel for certified suppliers. Recent public awards — exemplified by a municipal contract award in March 2025 — underscore the premium placed on certifications (e.g., NSF, AWWA), logistics reliability, and compliance documentation.
Supply chain and margin levers
Our scenario analysis highlights three levers that determine supplier and buyer outcomes through 2026:
- Sourcing strategy: Vertical integration into manganese sulfate conversion or long-term offtake agreements can buffer margin swings but require capital and lead time.
- Product differentiation: Certification, purity grading, and service (e.g., just-in-time deliveries, on-site dosing solutions) create defensible pricing tiers, especially for municipal and electronics customers.
- Contract design: Indexed pricing with caps/floors and blended-term structures reduces the probability of one-sided shocks while preserving supplier economics.
Competitive landscape — strategic positioning and implications
The market is populated by incumbent suppliers that follow distinct routes to competitive advantage. Below is a synthesis of the strategic posture of core industry players covered in our research.
- Carus Corporation (Peru, Illinois) — A major U.S. producer with a strong focus on water-treatment liquid grades and recognized certifications. Carus’s strengths lie in scale, certification credentials, and a deep municipal-sales footprint. Strategy implication: Carus is well positioned to defend municipal share and expand into adjacent treatment services; competitors should consider niche specialization or superior service models to counteract its scale.
- Hawkins, Inc. (Roseville, Minnesota) — A domestic manufacturer, blender, and distributor focused on municipal and government contracts through B2B channels. Hawkins’s distribution-centric model emphasizes localized supply and contract flexibility, a differentiator in municipal procurement cycles.
- Valudor Products, LLC (Encinitas, California) — A supplier of certified 40% solution grades with complete safety and compliance documentation. Valudor’s emphasis on certified formulations and documentation makes it a natural supplier to regulated water-treatment buyers and specialty industrial users.
- American Elements (Los Angeles, California) — Provider of very high-purity sodium permanganate grades targeting research, electronics, and high-end industrial customers. Their product focus allows premium pricing but requires tight quality controls and traceability.
- Rock Chemicals, Inc. — A bulk supplier that differentiates on reliable sourcing, compliance documentation, and logistics. Rock is attractive to buyers seeking scale purchasing and straightforward compliance support.
Collectively, these players illustrate three viable strategic archetypes: scale/certification (large incumbents), distribution-led reliability (regional blenders/distributors), and quality-differentiation (high-purity specialists). Our competitive scorecards in the full report benchmark each against CAPEX plans, certification breadth, and logistics resilience.
Strategic playbook for 2026
Below are actionable recommendations tailored to different organizational roles — buyers, producers, and investors — grounded in our market modeling and stress tests.
- For buyers and municipal procurement teams: Revisit sourcing cadence and contract design. Prioritize suppliers with dual strengths in certification and logistics. Build 12–18 month buffer inventories for critical projects and negotiate indexed, two-way price adjustment mechanisms tied to transparent input-cost proxies.
- For producers and distributors: Accelerate investments that raise barriers to entry — NSF/AWWA certifications, high-purity production lines for electronics, and traceable sourcing agreements. Consider selective vertical integration into manganese sulfate processing or structured partnerships with miners to manage feedstock risk.
- For investors and corporate development: Look for bolt-on opportunities that add either certification capabilities or localized logistics footprints. The concentrated supplier base presents M&A potential, but diligence must stress test feedstock exposure and regulatory compliance readiness, particularly for EU market access.
What PW Consulting’s full report provides (practical deliverables)
- Granular market model (2020–2032) with base-year 2025 calibration, scenario runs, and sensitivity matrices.
- Segmented demand analysis by region, grade, and application with adoption curves and forecasted unit consumption patterns (note: detailed segment tables are only available in the full report).
- Supplier scorecards covering certification breadth, capacity, contract history, and logistical strengths, plus a CR3/CR5 concentration assessment.
- Raw-material flow maps, stress-test results (including the impacts of manganese sulfate price shocks), and mitigation playbooks for buyers and sellers.
- Contract templates, procurement negotiation checklists, and a shortlist of strategic M&A targets aligned to three archetypal buyer/investor strategies.
Closing—why this matters for your 2026 agenda
Decisions made in 2026 around contracting, capacity investments, and certification will determine who captures the upside of the projected 4.6% CAGR through 2032 and who remains exposed to raw-material and regulatory dislocations. The concentrated nature of the market rewards strategic clarity: incumbents can protect margins through certification and logistics; new entrants must pursue either niche quality premiums or stronger supply-chain control to scale.
For executives preparing 2026 plans, the most valuable near-term actions are pragmatic: secure flexible supply terms, prioritize certifications demanded by large public buyers, and align capex to segments showing above-average growth in our forecasts. PW Consulting’s full Sodium Permanganate Market report operationalizes these priorities with the models, templates, and supplier analytics needed to convert insight into measurable outcomes.
To access the full dataset, including segment-level shares, price forecasts, and supplier scorecards, please refer to the complete PW Consulting report. The executive-level summary above is intentionally high-level — it surfaces the structural risks and strategic levers without disclosing the proprietary segment splits and microdata that underpin our proprietary conclusions.
For detailed analysis of this topic, please visit the official page: Sodium Permanganate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Hard Coating Film Market Outlook: 6.44% CAGR to USD 1,116M by 2032 – PW Consulting
By pmarketresearch, 2026-07-08
Hard Coating Film Market 2026: Strategic Imperatives for Decision-Makers
As companies prepare strategy and capital allocation plans for 2026, the hard coating film market presents a blend of steady growth, concentrated pockets of technological differentiation, and rising regulatory and materials complexity. Our PW Consulting market model pegs the industry at USD 715.0 Million in the base year (2025) and projects a clear expansion through the 2026–2032 forecast window, consistent with a compound annual growth rate of approximately 6.44%. This trajectory translates into a mid‑single‑digit growth path that rewards timely investments in product innovation, supply-chain resilience, and targeted go‑to‑market plays.
Hard Coating Film Market
Why this research matters for 2026 decisions
-
Timing of capacity and product launches: The market’s steady CAGR means capital deployment must be selective — favoring projects with differentiated IP, scalable manufacturing economics, and near-term OEM qualification paths. Firms that move from lab innovation to certified volume production in 2026 position themselves to capture disproportionate share as demand converts from prototypes to mainstream designs.
Hard Coating Film Market -
Technology inflection points: Display trends (foldable and flexible form factors), automotive interior/heads‑up displays, and medical device demands are shifting technical requirements toward multilayer coatings, self‑healing chemistries, and dual‑function surface treatments (e.g., anti‑glare + anti‑fingerprint). Our analysis highlights where first‑mover advantage matters and where incremental improvements will be table stakes.
Hard Coating Film Market -
Regulatory and procurement gating: Safety and biocompatibility standards (e.g., ANSI Z87.1 for specific applications, ISO 10993 for medical devices) and chemical compliance regimes (RoHS, REACH) materially affect supplier selection and qualifying timelines. Procurement teams must bake these regulatory milestones into supplier scorecards and R&D roadmaps in 2026.
-
Competitive positioning: The market shows moderate concentration — leadership clusters exist, but no single incumbent dominates. Our CR analysis indicates enough fragmentation to allow well‑executed entrants to scale quickly through targeted partnerships and differentiated value propositions.
Market dynamics executives must internalize
The hard coating film market is evolving from a materials problem into an integrated solution business where chemistry, substrate selection, laminating processes, and application engineering converge. Key dynamics to prioritize:
-
Application convergence: Electronic displays, touch panels, and consumer electronics still underpin demand, but automotive interiors, medical devices, and industrial hardware are increasing share of wallet for suppliers that can meet durability, optical, and regulatory thresholds.
-
Material supply and upstream partnerships: Polyester and polycarbonate substrates remain strategic inputs. Leading chemical suppliers and film producers are increasing coordination with coating formulators to secure upstream feedstocks and to accelerate scale‑up of functional films.
-
Performance layer innovation: Self‑healing coatings, multilayer stacks for foldables, and hybrid functional surfaces (e.g., anti‑glare plus anti‑fingerprint) are moving from demonstration to volume. These technologies demand new qualification protocols and often longer lead times for OEM acceptance.
-
Sustainability and process chemistry: Water‑based coating lines, solvent‑free chemistries, and lifecycle considerations are becoming procurement filters for Tier‑1 OEMs, particularly in automotive and medical categories.
Four strategic plays for 2026
-
Invest selectively in differentiated IP and scale economics — Not all capacity is equal. Prioritize investments that reduce unit cost while protecting differentiation (e.g., unique self‑healing formulations or verified multilayer stacks for flexible displays). Capital plans should include phased ramps tied to OEM qualification milestones to minimize stranded capacity risk.
-
Lock upstream and downstream partnerships — Secure substrate and chemical supply through long–term agreements or co‑development arrangements with major upstream suppliers; simultaneously, create OEM pilots that validate end‑to‑end performance. This reduces time‑to‑qualification and shields margins from raw‑material volatility.
-
Modular product portfolios — Offer core hard‑coated film platforms that can be configured via surface treatments (anti‑fingerprint, anti‑glare, antimicrobial, self‑healing) to meet divergent vertical needs. This modularity reduces SKU proliferation and accelerates OEM integration.
-
Embed regulatory readiness into go‑to‑market playbooks — For medical, automotive, and industrial applications, prepare pre‑emptive compliance dossiers (biocompatibility, chemical compliance, optical standards). Being “qualification‑ready” is a commercial advantage that shortens procurement cycles.
Competitive landscape — who is shaping the market
The competitive map blends specialized coating houses, large diversified materials groups, and regional scale players. A non‑exhaustive, representative set of firms illustrates the range of strategic postures:
-
Specialized innovators: Companies that focus on precision optical and functional coatings for displays and medical applications, offering proprietary hardness and ultra‑thin formats. These players differentiate on technical depth and OEM servicing.
-
Large materials groups: Diversified chemical and film producers that are developing multilayer systems for next‑generation displays and automotive use cases, often pairing coating science with substrate expertise and broader distribution networks.
-
Regional scale suppliers: Firms leveraging roll‑to‑roll processing efficiencies and localized service models to serve fast‑growing consumer electronics assembly hubs.
Notable companies characterized in our competitive analysis include leaders in precision optical coatings, multilayer and flexible film systems, dual‑function surface technologies, self‑healing chemistries, and regional coatings specialists. Each profile includes corporate strategy, technical capabilities, geographic orientation, and recent strategic moves — ranging from capacity expansion and product launches to expanded distribution agreements and volume deployments. These profiles illuminate replication risk and partnership opportunities alike.
Supply‑chain and regulatory checklist for 2026
-
Map critical upstream exposures: Identify single‑source risk for specialty resins and functional monomers, and quantify the lead times for qualification of substitute chemistries.
-
Build compliance slates early: Align product design with ANSI, ISO, RoHS/REACH, and medical biocompatibility standards to avoid last‑mile rejection by OEMs.
-
Plan for intelligent sourcing: Consider co‑development or toll‑coating arrangements in key regions to reduce logistics friction and accelerate OEM approvals.
-
Design quality economics: Invest in in‑line metrology and accelerated lifetime testing to validate self‑healing and multilayer performance at scale.
What the PW Consulting report delivers (practical takeaways)
Our full Hard Coating Film Market study combines quantitative forecasting with hands‑on, executable guidance for executives planning 2026 strategies. Highlights include:
-
Market sizing and demand model calibrated to 2020–2025 historicals and a 2026–2032 forecast horizon — enabling scenario analysis for conservative, base, and accelerated adoption curves.
-
Segment mapping by substrate, coating type, and application with supplier benchmarking and qualitative adoption trajectories — structured to support commercial and technical decision‑making.
-
Technology deep dives covering self‑healing chemistries, multilayer constructions for foldables, and dual‑function surface treatments — including validation approaches and OEM qualification pathways.
-
Practical go‑to‑market playbooks and procurement scorecards: supplier shortlists, qualification templates, and ramp‑to‑volume checklists for 2026 execution.
-
Three investment cases (conservative, base, upside) tied to entry options: greenfield capacity, toll coating partnerships, and licensing/co‑development — each with expected breakeven windows and sensitivity to raw‑material pricing and OEM adoption timing.
How to use this intelligence in your 2026 planning cycle
-
Boardroom readiness: Use the market model to stress‑test CAPEX requests — link each tranche of spend to concrete OEM milestones and compliance gates.
-
R&D prioritization: Allocate R&D budgets to technologies with the shortest path to qualification for target verticals (e.g., automotive HUDs vs. consumer foldables) and to chemistries that reduce lifecycle costs or improve sustainability metrics.
-
Commercial alignment: Integrate product modularity into sales engineering material so that channel partners and OEM customers can rapidly prototype and qualify configurations.
-
M&A and partnerships: Identify acquisition targets that provide missing capabilities (e.g., self‑healing formulations or specific functional surface treatments) and consider structured earn‑outs tied to volume milestones.
Closing perspective and next steps
The hard coating film market in 2026 rewards disciplined execution more than broad bets. The sector’s steady growth and increasing technical requirements create room for both high‑margin niche specialists and scaled producers that can integrate substrate and coating value chains. Short‑term winners will be those who (1) secure upstream inputs, (2) demonstrate rapid OEM qualification, (3) build modular product platforms, and (4) embed regulatory readiness into product roadmaps.
PW Consulting’s full report provides the granular segmentation, supplier scorecards, and actionable templates that senior leaders need to convert 2026 planning into executed outcomes. For decision‑makers who require the detailed splits, supplier matrices, and the complete scenario model — including downloadable financial templates calibrated to our base and upside forecasts — please access the full Hard Coating Film Market report on the PW Consulting research portal.
For detailed analysis of this topic, please visit the official page: Hard Coating Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Trehalose Market Poised to Hit USD 275.0M by 2032 at 5.45% CAGR
By pmarketresearch, 2026-07-08
Trehalose Market 2026: Strategic Preview for C-Suites and Growth Teams
PW Consulting’s forthcoming Trehalose Market study positions decision-makers to move confidently into 2026. The trehalose market has transitioned from a niche specialty ingredient to a strategically important raw material across food, pharma, supplements and personal care. Our base-year analysis (2025) and seven-year forecast (2026–2032) synthesize historical performance, supplier economics, regulatory developments and commercialization levers so that commercial, procurement and corporate development teams can convert market signals into profitable actions.
Trehalose Market
Headline market trajectory
From a clearly identifiable recovery in the early 2020s, trehalose has recorded sustained expansion: PW Consulting estimates the global market increased from roughly USD 130.0 Million in 2020 to USD 190.85 Million in 2025. Looking ahead, the market is projected to grow at a compound annual growth rate (CAGR) of approximately 5.45% during the 2026–2032 forecast period, reaching roughly USD 275.0 Million by 2032. These headline figures reflect the combined effects of application-led demand (notably premium food and stabilizing pharma uses), diversification of supply routes, and incremental product innovation in formulation and processing.
Trehalose Market
Why this study matters for 2026 decision-making
- Timing: 2026 will be the inflection year for many strategic bets — new facility ramps, pharmacopeia-compliant supply commitments, and regulatory clarity in key markets. The supply-demand balance and pricing elasticity we model give executives the basis for capacity planning and long-term contracting.
- Cross-functional implications: Trehalose sits at the intersection of R&D (formulation benefits), procurement (feedstock and processing economics), regulatory affairs (food and pharma approvals), and sales (clean-label and premium positioning). Our study clarifies trade-offs and prioritization paths for each function.
- Scenario readiness: We provide scenario-based outcomes that translate macro assumptions into P&L and working-capital impacts — essential for boards and investors evaluating greenfield vs. brownfield expansion or M&A.
What’s inside the report (practical, executable content)
- Market size and historical trend analysis (2020–2025) plus granular forward-looking demand curves through 2032, with base-year calibration.
- Segment and channel architecture (product forms, application classes, regional frameworks) together with sensitivity testing — enabling custom “what-if” modeling.
- Supply-chain diagnostics: feedstock inputs, process technologies, conversion economics, CAPEX/OPEX benchmarks and time-to-market implications for new capacity.
- Regulatory and quality mapping for food and pharmaceutical use-cases, including pharmacopeial compliance pathways and label/claim constraints in priority jurisdictions.
- Competitive landscape and capability matrices: supplier profiles, production footprints, proprietary technologies, and route-to-market comparisons.
- Commercial playbooks: price/distribution strategies, customer segmentation, and go-to-market templates for ingredient producers and formulators.
- Investment and M&A scorecards: valuation levers, synergies, and due-diligence checklists tailored to targets in Asia, Europe, and North America.
- Risk and resilience framework: supply shocks, regulatory shifts, ESG metrics and mitigation actions with concrete KPIs.
- Appendices: data tables, methodology notes, primary interviews and a repository of regulatory citations.
Note: this preview intentionally omits detailed segment-level percentages and region/application breakdowns — the full intelligence package contains the granular split tables, primary-sourced pricing curves and scenario workbooks that clients use for operational and M&A decisions.
Trehalose Market
Competitive landscape — who to watch and why
The trehalose industry exhibits a moderate concentration profile: a small group of established suppliers hold a meaningful share of accessible capacity, while a broader set of regional producers competes on cost and proximity. The market’s concentration dynamics reward scale in capability (high-purity grades, low-endotoxin production for pharma) and investment in branded, standardized processes.
- Nagase & Co., Ltd. (Tokyo, Japan) — a strategic technology owner in the TREHA® brand, Nagase’s proprietary enzymatic starch-to-trehalose process is a differentiation vector. Their emphasis on high-purity trehalose tailored for food and beverage formulators makes them an attractive partner for co-developments and licensing arrangements (source: Nagase Food Ingredients).
- Shandong Fuyang Biotechnology Co., Ltd. (Pingyuan, Shandong, China) — a cost-competitive food-grade producer embedded in corn deep-processing networks. Their export orientation and integrated feedstock access are key competitive advantages when volume and price sensitivity dominate procurement decisions.
- Meihua Holdings Group Co., Ltd. (Langfang, Hebei, China) — a broad ingredient player supplying trehalose as a colloidal polysaccharide for freshness and quality retention. Meihua’s full ISO 14001 coverage highlights a parallel focus on operational sustainability (Meihua ESG Report, 2024), an increasingly material consideration for global buyers.
- Cargill, Incorporated (Minneapolis, USA) — as a major distributor and ingredient systems house, Cargill plays a pivotal channel role for bakery, confectionery and clean-label applications, enabling rapid customer access in North America and parts of Europe.
- Pfanstiehl (Waukegan, Illinois, USA) — differentiated by pharmacopeia-compliant trehalose (USP-NF, EP, JP, ChP), Pfanstiehl is the go-to for biopharma stabilization and cryopreservation uses, where regulatory-grade consistency and low endotoxin are non-negotiable (product information, 2026).
- Regional suppliers (e.g., Shandong Deshang, Changyi Longchang) — numerous manufacturers supply competitive volumes for food and ingredient markets. Their advantage lies in regional logistics, flexible MOQ, and localized commercial terms.
Regulatory and quality developments shaping 2026 moves
- Regulatory acceptance is advancing in major markets: Health Canada has communicated no objection to trehalose for human food applications (February 2025), reducing a critical barrier for North American commercialization paths.
- Pharma-grade certification and pharmacopeia listings (USP, EP, JP) are decisive enablers for higher-margin stabilization and cryopreservation segments; suppliers achieving these certifications command premium pricing and longer contract horizons (Pfanstiehl product information, 2026).
- Sustainability credentials — such as full ISO 14001 coverage — are becoming commercial differentiators for global retailers and ingredient buyers, and can materially influence supplier selection in RFPs (Meihua ESG Report, 2024).
Strategic implications and recommended actions for 2026
We translate market dynamics into concrete options executives should evaluate immediately. The recommended actions differ by role but cohere around three priorities: secure differentiated supply, capture premium applications, and harden commercial resilience.
- Procurement & Supply Chain
- Lock in staggered long-term contracts with tiered volume-price triggers to manage feedstock volatility and secure capacity for high-priority SKUs.
- Audit supplier capabilities against pharmacopeial and sustainability KPIs; qualify at least two independent sources for critical pharma and clean-label grades to minimize single-source exposure.
- R&D & Product Strategy
- Prioritize formulation projects where trehalose’s humectant, stabilization and freezing-point depression properties unlock premium claims (e.g., clean-label texture retention, biopharma stabilization).
- Co-invest in application trials with technology-holding partners (e.g., enzymatic process proprietors) to secure early access to next-generation grades.
- Commercial & Marketing
- Segment accounts by value capture: pursue bespoke pharma contracts and supply agreements for high-value formulators, while leveraging distribution partners for broad food and bakery penetration.
- Develop price cadence and promotional playbooks that preserve margin in an environment of periodic low-cost regional supply saturation.
- Corporate Development & Finance
- Evaluate tuck-in acquisitions in regions where feedstock integration or regulatory certifications are scarce — these deals can compress time-to-market for pharmacopeial grades.
- Use scenario P&L models to test CAPEX choices: a small biotech-grade line vs. scaling commodity volumes—each path has distinct payback and risk profiles aligned to different buyer segments.
- Regulatory & ESG
- Proactively engage regulators in key markets to accelerate acceptance for new applications and claims; maintain transparent ESG disclosures to meet buyer requirements.
Risks to monitor in 2026
- Feedstock price volatility and corn-processing throughput changes in major producing regions, which can compress margins during oversupply cycles.
- Regulatory shifts or delays in pharmacopeial recognition in target jurisdictions, impacting time-to-revenue for pharma-grade initiatives.
- New process entrants or capacity additions that alter regional pricing dynamics — our monitoring framework indicates windows of acute oversupply that require tactical response.
How PW Consulting helps executives convert insight into action
Clients use our study to calibrate three deliverables in the first half of 2026: (1) a supply and procurement playbook with contracting templates and cost-to-serve analysis; (2) a go-to-market plan for prioritized applications (food, pharma, supplements, personal care) with channel economics; and (3) an M&A pre-deal diligence pack including synergy capture models and de-risking checklists.
If your team must decide on capacity commitments, pricing architecture, or a targeted acquisition in 2026, our trehalose market model provides the scenario outputs, sensitivity ranges and supplier scorecards necessary for prudent, high-confidence decisions.
Next step
PW Consulting’s full Trehalose Market report contains the proprietary segment tables, regional and application-level forecasts, and the interactive scenario workbook that operational teams use to stress-test investment choices. For executives preparing strategic plans and budgets for 2026, the full dataset and playbooks are essential. Access the complete study and advisory services via our report landing page to receive the full intelligence package and schedule a custom briefing.
For detailed analysis of this topic, please visit the official page: Trehalose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Transformer Oil Market to Hit USD 3,905 Million by 2032 at 6.5% CAGR
By pmarketresearch, 2026-07-08
Transformer Oil Market: Strategic Imperatives for 2026
As power systems evolve — driven by electrification, renewables, urbanization and tighter energy-efficiency mandates — the transformer oil market is moving from a commoditized backwater into a strategically important input for utilities, OEMs and industrial buyers. PW Consulting’s latest Transformer Oil Market study (base year 2025; forecast 2026–2032) synthesizes five years of historical behaviour with forward-looking scenario analysis to deliver the market intelligence executives need to set resilient, opportunity-focused strategies for 2026.
Transformer Oil Market
Macro snapshot you can act on
Our market model places the global transformer oil market at USD 2,530 Million in 2025, growing at a compound annual growth rate (CAGR) of 6.5% through the 2026–2032 forecast window, reaching roughly USD 3,905 Million by 2032. Those headline dynamics mask important second-order forces: raw material price volatility, regulatory tightening on energy performance and hazardous substances, and an accelerating shift toward ester, bio-based and circular fluids in specific high-value use cases. The full report translates this macro trajectory into decision-ready scenarios — from conservative procurement hedges to aggressive product and M&A playbooks — without exposing the proprietary segment-level data you’ll find in the paid study.
Transformer Oil Market
Why 2026 is a strategic inflection point
-
Regulatory acceleration: Since early 2025 the EU introduced stricter energy performance and greenhouse gas reduction requirements for transformers, raising the bar for dielectric fluids’ thermal and oxidative performance. Concurrently, legacy regulatory rules (for example, EPA TSCA requirements that require incineration for oils with PCB concentrations above specified thresholds) continue to impose disposal and remediation costs that change total cost of ownership calculations for older assets.
Transformer Oil Market -
Input-cost shocks and supply-side repricing: Base oil prices have shown renewed upward pressure — with reported US base oil prices around USD 1,842/MT in March 2026 — and crude volatility historically translating into rapid cost shifts. These dynamics compress margins on commodity mineral oils while improving the economics of premium, long-life fluids that lower lifecycle maintenance and replacement spending.
-
Market consolidation and buyer leverage: The market exhibits a moderate concentration profile (CR3 ~46.3%; CR5 ~61.2%), creating a structure where leading suppliers exert meaningful influence over product innovation, certification pathways and supply chain arrangements — but also where differentiated, sustainable products can carve premium niches.
Competitive landscape: where capability meets strategy
The competitive map is a mix of global majors with deep logistics and R&D footprints, regional specialists with application-specific expertise, and emerging leaders in sustainable fluids. Key supplier archetypes identified and profiled in the report include:
-
Innovation-led incumbents: European and multinational players have pushed premium grades, certification frameworks and circular initiatives. Recent commercial and deployment news underline this trend — for example, the uptake of circular transformer oils by OEMs and factory-level deployments in 2026 highlights how sustainability credentials are moving from pilot to production readiness.
-
Regional scale players: Large refiners and chemical groups supply base mineral grades at scale for domestic markets and exports, using integrated supply chains to preserve cost advantage. Their strength in price-sensitive segments coexists with an increasing focus on compliance and certification.
-
Niche specialists: Producers of natural esters and re-refined oils are building selective advantages in urban substations, offshore wind, and other fire-sensitive or sustainability-conscious applications. These suppliers often combine technical testing support with field qualification programs tailored to utilities and OEMs.
Full company profiles in the report unpack go-to-market strategies, technology differentiators, certification footprints and recent commercial developments for leading players — enabling buyers to match supplier capabilities to specific asset strategies and procurement levers.
Operational levers and strategic playbook for 2026
PW Consulting recommends a prioritized set of actions for corporate decision-makers, organized by horizon and informed by stress-tested scenarios in the full report.
-
Immediate (0–6 months) — Harden procurement and compliance. Implement hedging and flexible contracting tied to base oil indices; audit aging transformer fleets for PCB risk and disposal cost exposure; and fast-track qualification of at least one circular or natural-ester fluid as a pilot for high-value substations.
-
Near-term (6–18 months) — Shift product and capital allocation. Reallocate OPEX/CAPEX toward long-life fluids where lifecycle cost models justify higher unit prices; invest in in-situ testing capability; and establish recycling partnerships or off-take agreements with re-refiners to reduce disposal risk and capture circular premiums.
-
Mid-term (18–36 months) — Reconfigure supplier networks and M&A scouting. Pursue bolt-on acquisitions or strategic JV arrangements to secure niche ester or re-refining capability; renegotiate supply terms based on total-cost-of-ownership metrics; and embed regulatory scenario triggers into capital planning for new transformer builds.
Risk management and scenario analysis you can use
The report includes sensitivity matrices showing how +/-10–30% swings in base oil costs, varying adoption curves for ester fluids, and differentiated regulatory paths affect price, margin and NPV for buyers, suppliers and investors. It also provides a practical risk heatmap focused on supply disruption, regulatory penalties, certification delay, and reputational exposure from non-compliant disposal. These tools convert headline CAGR and market-size projections into actionable thresholds for contract clauses, inventory policy and capital allocation.
Actionable contents of the full study (high level)
-
Proprietary market model (2020–2025 historical; 2026–2032 forecast) with scenario toggles for price shocks, regulatory regimes and adoption curves for alternative fluids.
-
Supplier benchmarking and capability maps, including certification matrices, regional logistics strength and technical validation timelines.
-
Procurement playbook and sample contractual language for indexation, quality warranties and circular off-take agreements.
-
Lifecycle cost calculators and field-qualification protocols for mineral, synthetic and bio-based fluids.
-
M&A and partnership targets: screening criteria and shortlist derived from market concentration analytics and technology readiness levels.
-
Regulatory impact assessment covering PCB disposal rules, EU energy-performance measures, recent duty changes affecting trade flows, and recommended compliance pathways.
To honour the “preview” purpose of this article, we intentionally withhold proprietary granular splits and segment-by-region revenue tables; the full study includes detailed segmentation and quantitative matrices that power the tactical recommendations above.
Signals to watch in 2026
-
Certification and factory deployments: Major OEMs integrating circular and ester fluids into production lines will be an early indicator that field adoption is becoming de‑risked.
-
Raw-material and index behaviour: Sustained high base oil prices or renewed crude volatility will accelerate buyer interest in longer-life, higher-margin fluids.
-
Regulatory shifts: Any tightening of energy-performance or hazardous-waste rules materially changes lifecycle economics for legacy oils, increasing conversion activity.
-
Competitive moves: M&A by majors to acquire re-refining or ester capabilities will compress time-to-market for circular products and alter supplier bargaining dynamics.
What this means for executives
For procurement leaders, the decision calculus in 2026 must move beyond unit price to lifecycle value: qualification timelines, disposal costs, and supplier sustainability credentials will determine true TCO. For product and R&D leaders, allocating resources to ester and circular chemistry — plus the validation infrastructure to shorten qualification cycles — offers a high-return hedge against both regulation and raw material inflation. For corporate strategists and deal teams, the market’s moderate concentration suggests attractive pick-and-build opportunities to stitch regional scale to differentiated products.
PW Consulting’s Transformer Oil Market study converts the headline growth path (USD 2,530 Million in 2025 growing at 6.5% CAGR to 2032) into a clear sequence of choices: where to protect margins, where to innovate, and where to consolidate. The actionable tools in the full study — scenario models, procurement playbooks, supplier scorecards and target lists — are designed to be executed against a 2026 planning calendar.
Next steps
If you are preparing budgets, portfolio plans or acquisition screens for 2026, PW Consulting offers executive briefings and custom modelling workshops that use the report’s underlying data and scenario engines to produce bespoke recommendations for your asset base and strategic priorities. For access to the full segmentation, company profiles, and the quantitative annex that underpins the recommendations in this preview, please visit our report page or contact our industry team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Transformer Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com