

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Hydrogen Peroxide Market to Grow at 5.2% CAGR Through 2032

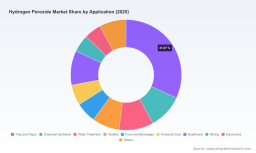
Hydrogen Peroxide Market — Strategic Imperatives for 2026 Decision‑Makers
As PW Consulting’s senior industry analyst, I present a concise, decision‑focused preview of our new Hydrogen Peroxide Market study. This briefing synthesizes the macro trajectory, competitive moves, regulatory shocks and practical decision tools that corporate leaders will need in 2026. It highlights why hydrogen peroxide (H2O2) is rapidly re‑shaping upstream capital plans, specialty product strategies and procurement playbooks — and why leaders must act now. The market grew from roughly USD 3,073.5 Million in 2020 to about USD 3,624.4 Million in 2025 and, under our base forecast, is on course to reach approximately USD 5,096.5 Million by 2032, reflecting a compound annual growth rate of 5.2% across the 2026–2032 forecast window.
Hydrogen Peroxide Market
Why this study matters for 2026 strategic decisions
- Demand momentum is shifting from commodity bulk to value‑added, low‑carbon and super‑pure grades. That changes margin pools, qualification cycles and capital intensity.
- Recent capacity projects and joint ventures in Asia are remapping the supply map for high‑purity and specialty grades — creating both opportunity and risk for Western producers and buyers.
- Regulatory uplifts and food‑use clarifications have real commercial consequences for producers, formulators and food processors that rely on H2O2 as an antimicrobial, bleaching and oxidizing agent.
- Market concentration is material but not prohibitive: the sector shows a notable share held by top players, leaving room for niche specialists and M&A to reshape regional balances.
- Price and feedstock volatility (energy, hydrogen availability, and catalyst/chemical intermediates) require new contracting and hedging approaches beyond spot purchasing.
Market trajectory — what the headline numbers tell you
The market’s historical climb from USD ~3.07 billion in 2020 to about USD 3.62 billion in 2025 reflects resilient end‑market demand: traditional users such as pulp & paper and textiles remain important, while growth pockets have emerged in electronics, photovoltaics, water treatment and healthcare/disinfection. Our forecast to 2032 captures both baseline industrial demand and accelerated adoption in specialty segments driven by semiconductor and solar wafer fabrication, alongside incremental volumes from regulatory approvals for food uses.
Hydrogen Peroxide Market
Interpreting the 5.2% CAGR: this is not uniform growth across all grades or regions. Instead it signals services and product bifurcation — steady demand for established industrial grades contrasted with faster expansion for high‑purity and low‑carbon solutions. For corporate planners, the CAGR therefore implies two concurrent strategic imperatives: 1) protect commodity margins through operational efficiency and integrated procurement; and 2) pursue higher‑margin differentiation where technical qualification and secure offtake create durable pricing power.
Hydrogen Peroxide Market
Competitive landscape — who’s shaping supply and capability
The industry is composed of global incumbents with integrated capacities and a cohort of regional specialists. Top strategic archetypes we track:
- Global integrated majors scaling specialty and electronic grades through capacity expansion and JV activity.
- Regional producers capturing local industrial demand and cost advantages in feedstock‑intensive applications.
- Specialty players and super‑pure manufacturers focusing on semiconductor and photovoltaics where qualification barriers are high.
Key corporate moves to watch (recent, verified):
- Solvay: completed a major expansion in Zhenjiang (China), substantially increasing production capacity for high‑purity electronic‑grade hydrogen peroxide to address semiconductor demand. That move recalibrates supplier options for Asian device manufacturers and intensifies competition on quality and logistics.
- Evonik: in partnership with Fuhua Tongda Chemicals, started trial production at a Leshan (China) specialty‑grade facility, with full operations expected in mid‑2026 to serve photovoltaics, semiconductors and food‑contact applications.
- Nouryon: launched a low‑carbon hydrogen peroxide product (Eka® HP Puroxide™), signalling that decarbonized product lines are becoming commercially available and marketable differentiators rather than niche R&D topics.
- Mitsubishi Gas Chemical: remains the market leader in super‑pure segments, a critical supplier to semiconductor fabs and electronics supply chains.
These moves underscore three strategic tensions for market participants: scale versus specialisation, localised supply security versus global optimisation, and carbon intensity versus cost competitiveness.
Regulatory and demand shocks to factor into 2026 planning
- Regulatory change: On September 3, 2025, the FDA amended food additive regulations for hydrogen peroxide, expanding permitted food uses and removing certain restrictions. This materially alters the addressable market for food processors and ingredient suppliers who can qualify H2O2 within food manufacturing processes.
- Procurement & qualification timelines: semiconductors and photovoltaics require lengthy qualification; new capacity can take quarters to meaningfully relieve supply tightness despite construction completion.
- Environmental policy and decarbonisation incentives: product lines labelled as “low‑carbon” command new buyer interest and potentially pricing premiums from sustainability‑driven customers and procurement standards.
What the PW Consulting report delivers — practical tools and coverage
We designed the study for executable decisions. Highlights within the full report (operational and advisory outputs):
- Detailed market sizing and growth drivers (historical 2020–2025 and forecast 2026–2032) with sensitivity testing across macroeconomic and end‑market scenarios.
- Plant‑level capacity map, utilisation analysis and a timeline of announced, under‑construction and planned projects. (Note: this preview deliberately omits plant‑level figures — full dataset available in the report.)
- Company profiles and competitive scorecards for global and regional producers, including strategy, product portfolio (commodity vs specialty), sustainability initiatives, and recent M&A/activity trackers.
- Supply chain and logistics risk matrix: feedstock exposure, energy intensity, shipping/warehousing constraints and contingency planning for supply disruptions.
- Commercial playbooks: procurement contracting templates, sample offtake structures for specialty grades, price pass‑through models and margin protection strategies.
- Regulatory impact assessment aligned to recent FDA amendments and regional chemical policy scenarios, with compliance timing and cost estimates.
- Strategic M&A and JV screening frameworks to identify attractive targets by technology, geography and capacity vintage.
- Comprehensive Excel datasets and model access for client bespoke scenario runs.
Scenario lenses & recommended strategic pivots for 2026
- Base Case (reference): steady industrial demand with specialty outperformance — actions: optimise cost to defend commodity margins and selectively invest in specialty grade qualification.
- Electronics/PV Upside: accelerated fab/solar capacity leads to tight super‑pure demand — actions: secure long‑term offtake agreements, prioritise supply to high‑value customers, and accelerate qualification pipelines.
- Low‑Carbon Premium: corporate and procurement buyers pay premiums for verified low‑carbon H2O2 — actions: invest in low‑carbon production or partner with low‑carbon suppliers; quantify premium vs incremental cost.
- Regulatory Expansion: expanded food and pharmaceutical uses following enforcement updates — actions: fast‑track regulatory approvals and expand food‑grade production lines where cost‑effective.
- Supply Disruption: feedstock/energy shocks or logistics disruptions — actions: diversify suppliers regionally, increase buffer inventories for critical grades, and adopt flexible contracting.
Top priority actions for executives in 2026
- Stress‑test supplier dependencies by grade and region; create a prioritized mitigation plan for super‑pure and low‑carbon shortages.
- Negotiate a portfolio of contracting approaches (short‑term spot, intermediate‑term indexed, and long‑term fixed offtakes) tailored to grade and strategic value.
- Invest in product qualification for high‑purity and low‑carbon grades today — the sales lead time to realize margin uplift is measured in quarters, not weeks.
- Assess strategic partnerships or minority equity positions in regional capacity projects as a faster alternative to greenfield build‑out.
- Embed regulatory monitoring into commercial planning: the FDA amendment in 2025 is a live example of how rules can expand addressable markets overnight.
Why PW Consulting’s study is indispensable for 2026
For leadership teams evaluating capex, M&A, supply contracts, product roadmaps or procurement strategies, the value of timely, granular and executable intelligence cannot be overstated. This preview demonstrates the analytical depth we bring — but, in keeping with a “trailer” approach, we have intentionally withheld the granular segmentation tables, plant‑level capacities and certain proprietary model outputs that clients use to make binding investment and commercial decisions.
To access the full data‑rich report, plant‑level capacity maps, company scorecards, regulatory impact models and downloadable Excel workbooks that support 2026 decision cycles, consult the PW Consulting Hydrogen Peroxide Market study page. The full study provides the exact metrics, split analyses and model granularity needed to convert strategic options into executable plans.
For detailed analysis of this topic, please visit the official page: Hydrogen Peroxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com