

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Hydrazine Hydrate Market at USD 280.6M in 2025 — PW Consulting Market Insight

Hydrazine Hydrate Market 2026 — Strategic Outlook and Decision Framework
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise yet substantive preview of our Hydrazine Hydrate Market research — designed specifically to inform executive decisions across procurement, R&D, regulatory affairs, and M&A in 2026. This briefing synthesizes the market’s trajectory, structural dynamics, and the practical intelligence contained in the full study. It deliberately illustrates the analytical depth you can expect while withholding detailed segment-level financial tables and proprietary model outputs — the strategic “teaser” intended to guide you to the full report for transaction- and project-critical granularity.
Hydrazine Hydrate Market
High-level market trajectory: what the numbers mean for 2026 decisions
The global hydrazine hydrate market shows a steady expansion through the mid-2020s. From a baseline that rose materially across 2020–2025, the market size reached USD 280.6 Million in our base year (2025). Under our central case assumptions the market continues to expand at a compound annual growth rate (CAGR) of approximately 5.5% across the 2026–2032 forecast window, reaching an overall valuation north of USD 400 Million by the end of the horizon. This pace is consistent with a specialty-chemicals product experiencing mixed cyclical demand — solid industrial applications balanced by regulatory and logistics frictions that constrain unfettered upside.
Hydrazine Hydrate Market
For 2026 corporate planning, this implies a market environment where demand growth is reliable but not explosive. Firms should prioritize operational resilience, selective capacity investments, and downstream partnerships that capture higher-margin specialty applications rather than broad-volume plays that assume rapid commoditization.
Hydrazine Hydrate Market
Drivers shaping near-term supply and demand
- End-market mix and downstream pull: Demand is anchored in legacy industrial uses (water treatment, polymer and foam systems, agrochemical synthesis, pharmaceutical intermediates) and is being reshaped by pockets of higher technical intensity (high-purity grades for aerospace and advanced synthesis).
- Regulatory tightening: Classification and authorization requirements in major markets (notably the EU) are raising compliance costs and influencing sourcing choices, favoring suppliers that can demonstrate robust regulatory dossiers and chain-of-custody controls.
- Logistics and handling constraints: Shipping and handling standards, including insulated pressure-rated packaging and certified handlers under international transport rules, increase landed costs and favor regional supply hubs or nearshoring strategies.
- Feedstock and input inflation: Upstream feedstock cost pressures have increased production costs materially in recent periods — a factor that constrains margin expansion unless offset by product mix optimization or pass-through pricing.
Market structure and competitive landscape — how to interpret concentration metrics
The hydrazine hydrate sector is best characterized as a specialized, moderately fragmented market. Aggregate concentration metrics show that the largest few players do not dominate the sector to the degree seen in highly consolidated commodities; instead, a handful of established chemical manufacturers, particularly those with integrated synthesis capabilities and regional production assets, capture a meaningful share while a broad tail of regional producers serves local demand.
Key industry participants whose strategies merit attention include:
- Otsuka-MGC Chemical Company, Inc. (Japan): The largest global manufacturer and the sole domestic producer in Japan; its scale and domestic footprint make it a natural price-maker for Asian flows and a critical counterparty for supply continuity in the region.
- Arkema S.A. (France): A diversified specialty-chemicals group that offers hydrazine hydrate across a range of concentrations and derivatives. Arkema’s strengths are its formulation know-how and customer relationships in polymer foam and crop protection intermediates.
- LANXESS AG (Germany): A supplier with a strong agrochemical orientation and recent strategic moves into higher-purity grades aimed at aerospace and advanced industrial applications — signaling a play for margin differentiation.
- Nippon Carbide Industries, Japan Finechem, Kanto Chemical (Japan): These firms provide a mix of regional supply, technical grades, and specialty services (e.g., analytical and technical-grade products), supporting localized supply chain needs and regulatory compliance for customers in pharmaceuticals and agrochemicals.
The competitive picture is dynamic: product-quality differentiation (e.g., high-purity, aerospace-grade variants), supply security, and regulatory readiness are increasingly salient axes of competition. Recent corporate activity — product launches targeted at high-value applications and focused trade-show engagement — underscores a strategic shift from volumetric growth to capability-led differentiation.
Regulatory, safety and logistics headwinds
Regulation is a central constraint on market development and a primary driver of supplier selection:
- Hydrazine’s inclusion as a substance of very high concern in some regulatory regimes raises the cost and time-to-market for affected uses through authorization dossiers and tighter EHS controls.
- Recent alignment of domestic rules in the United States to updated international standards created near-term compliance costs — relabeling, retraining, and revised transport protocols — with ongoing implications for cross-border supply chains.
- Transport regulations under the UN model require pressure-rated, insulated packaging and certified handlers, which limits the pool of logistics providers and raises barriers to ad hoc cross-border shipments.
Companies that prioritize regulatory compliance, invest in documented stewardship programs, and develop certified logistics footprints will reduce both operational risk and the total cost of ownership for customers, creating a defensible commercial position in 2026.
Cost pressure and margin implications
Upstream feedstock inflation has been a material margin headwind, with recent periods showing a significant rise in input costs. This forces hard choices for producers: absorb margin contraction, pursue product-mix upgrades toward higher-margin specialty grades, or pass costs through — each option has different competitive and commercial consequences. Procurement leaders should stress-test supplier contracts for indexation, hedging mechanisms, and flexibility clauses as part of sourcing decisions in 2026.
Practical content of the full PW Consulting report
Our full report is structured to support immediate decision-making and project planning. It includes:
- Proprietary demand-modeling across 2020–2032 with base-year calibration to 2025 and scenario runs that reflect regulatory, feedstock, and logistics shocks;
- Price and cost decks that reconcile raw material inputs, production OPEX, and regional logistics cost components;
- Supplier and capacity maps with facility-level commentary, permitting status, and compliance readiness;
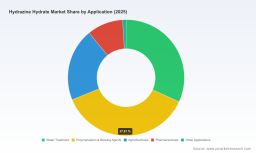
- Applications-level demand narratives (water treatment, polymerization & blowing agents, agrochemicals, pharmaceuticals, and others) with qualitative substitution and elasticity analysis — note: detailed segment-level value tables are available in the premium dataset;
- Regulatory impact assessment and a practical compliance checklist for market entry and product stewardship programs;
- An actionable M&A and partnership playbook: screening criteria for targets, indicative valuation sensitivities given feedstock and regulatory risk, and integration checklists;
- Scenario-driven go-to-market recommendations for producers and downstream buyers, including procurement contracting templates and a supplier-risk matrix;
- Executive-ready slide sets and editable data extracts to embed in board materials or investor decks.
How to use this intelligence in 2026 — four priority actions
- For producers: prioritize investments in higher-purity product lines, regulatory dossier completion, and certified logistics to capture premium end-markets. Defer greenfield capacity focused purely on volume unless backed by long-term offtake.
- For buyers/procurement: rebalance sourcing toward suppliers that combine price competitiveness with demonstrated regulatory robustness and logistics certification; negotiate clauses that mitigate feedstock inflation through shared-index mechanisms or measured pass-throughs.
- For M&A and private equity: target niche, regionally entrenched assets with clean regulatory records and technical-grade capabilities; valuation multiples must explicitly account for authorization risk and potential capex to meet higher-purity specifications.
- For R&D and product teams: accelerate workstreams that enable substitution into higher-value applications and explore formulation strategies that reduce hydrazine load while retaining performance to avoid regulatory bottlenecks.
Risk framework — exposures to monitor
Key risks that will affect strategy in 2026 include regulatory authorization outcomes in major markets, sudden feedstock price spikes, disruptions to certified logistics capacity, and technological substitution in downstream formulations. Our report provides a quantified risk matrix and mitigation playbook tailored to each stakeholder group.
Next steps — where to find the granular intelligence
This preview outlines the strategic contours and practical imperatives that PW Consulting’s Hydrazine Hydrate Market report delivers. The full study contains the segment-level revenue tables, regional and application splits, supplier facility maps, and the proprietary scenario models that are intentionally omitted here to preserve the value of the primary dataset. For procurement tenders, M&A diligence, or capital expenditure approvals in 2026, those dataset elements are the operational inputs you will need.
Contact PW Consulting to request the complete report package, which includes editable data extracts, scenario-model access, and a one-hour briefing with our lead analysts to align the findings to your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Hydrazine Hydrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com