

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Chemical & Materials
PW Consulting: Marine Anti-Fouling Coatings to Reach USD 5.53M by 2032 at 6.18% CAGR
By pmarketresearch, 2026-07-13
Marine Anti-Fouling Coatings Market — Strategic Outlook for 2026 Decision‑Makers
Executive teaser
PW Consulting’s latest industry briefing frames the Marine Anti‑Fouling Coatings market as a mid‑decade inflection zone where regulation, decarbonisation pressures, and chemistry innovation intersect to reshape supplier economics and buying behaviour. Anchored to a 2025 base year and a 2026–2032 forecast horizon, the market is projected to grow at a compound annual growth rate (CAGR) of 6.18% over the forecast window. After a pronounced near‑term disturbance observed in 2025, the sector rebounds in 2026 and is on a steady expansion path toward the end of the decade. This preview outlines the strategic implications for organisations making capital, procurement and R&D choices in 2026 — while intentionally withholding detailed sub‑segment tables and regional splits to preserve the value of the full report.
Marine Anti-Fouling Coatings Market
Why this study matters for decisions in 2026
Three characteristics make 2026 a pivotal year for stakeholders in marine anti‑fouling coatings:
Marine Anti-Fouling Coatings Market
- Regulatory crystallisation: International maritime authorities are moving from guidance to enforceable expectations for biofouling management.
- Commercialisation of next‑generation chemistries: Biocide‑reduction and fouling‑release systems are transitioning from niche proof‑points to commercially validated offerings that can materially affect fuel consumption.
- Market consolidation pressure: A relatively concentrated supplier base (the top three and top five suppliers account for meaningful shares of the market) is converging with new entrants and partnerships that specialize in bio‑repellents and sustainable resins.
For CFOs, fleet managers, suppliers and investors, the net effect is simple: choices made in 2026 on specification, testing, partner selection and capital allocation will determine competitive positioning and regulatory exposure for at least the next contracting cycle.
Marine Anti-Fouling Coatings Market
Data‑driven snapshot (what we disclose)
- Base year: 2025; forecast period: 2026–2032.
- Forecast CAGR (2026–2032): 6.18%.
- Market trajectory: a recovery beginning in 2026 and a steady climb through 2032 as fleet renewal, retrofit activity and offshore energy demand support volumes.
- Market concentration: the leading three and five suppliers hold a collective share that indicates a moderately concentrated competitive structure, with implications for pricing and technology access.
Note: This preview deliberately omits granular regional, application and type‑level revenue breakdowns. The full dataset and segment tables are available in the complete study.
Macro & regulatory dynamics shaping 2026 strategies
The policy backdrop is a primary near‑term driver. Recent developments at the IMO and in European chemicals regulation are moving the industry toward stricter management of biofouling and tighter controls on biocidal components. Key regulatory inflection points that inform procurement and compliance roadmaps include:
- IMO guidance upgrades and the progression of a potential legally binding framework for biofouling management — these raise expectations for documented hull maintenance, in‑water cleaning regimes and antifouling system performance.
- Capacity building initiatives and pilot projects that accelerate adoption in markets previously lagging on biofouling enforcement, altering demand geographies and service models.
- Regional chemical control regimes that drive reformulation costs and increase the capital intensity of product development for coatings that rely on restricted biocides.
In tandem, decarbonisation agendas are turning antifouling into a fuel efficiency lever. Recent product validations claiming meaningful fuel savings highlight a new procurement criterion: coatings are now evaluated not only on fouling control but on lifecycle fuel‑burn impacts and resulting emissions reductions.
Technology and value‑chain shifts
Innovation trajectories fall into three converging streams: biocide reduction (including biocide‑free fouling‑release systems), targeted bio‑repellents and advanced resin systems that improve durability and biodegradability. Complementary trends include digital hull monitoring and service models that combine coating supply with maintenance contracts and validated fuel‑saving guarantees.
These shifts create new commercial configurations: coatings vendors forming partnerships with biotechnology specialists, resin suppliers and offshore developers; shipowners experimenting with performance‑linked contracting; and service providers bundling application, monitoring and periodic cleaning into single agreements.
Competitive landscape: how incumbents and challengers are positioning
The market is populated by well‑capitalised global coatings groups, specialist marine formulators and niche biochemical innovators. Leading manufacturers differentiate along several axes: proven field performance, breadth of product portfolio (ablative, self‑polishing, fouling‑release, copper‑free), R&D pipelines, shipyard relationships and service capabilities.
- Global coatings majors are leveraging scale to fund reformulation and validation programmes and to secure shipyard and OEM channels.
- Specialist players and biotech providers are driving chemistry innovation — often via licensing or strategic partnerships — creating asymmetric competitive threats to legacy chemistries.
- Regional and niche manufacturers compete on responsiveness, customisation and service bundles for leisure craft and specialised offshore assets.
Recent strategic moves — collaborative R&D agreements combining bio‑repellent molecules with advanced biodegradable resins, launches of PFAS‑free silicone lines, and strategic alliances with offshore renewable developers — demonstrate a market pivot from ingredient optimisation to systems thinking. These developments point to an emerging playbook: partner for differentiated actives, validate fuel‑saving claims under third‑party protocols, and align product roadmaps with evolving compliance timelines.
Strategic imperatives for 2026 (actionable guidance)
Decisions in 2026 should be structured around four parallel tracks:
- Compliance & risk mitigation: Adopt a regulatory‑first product and maintenance selection process. Prioritise suppliers with robust validation data and documented exposure assessments aligned to anticipated IMO and regional mandates.
- Performance economics: Move beyond upfront coating price to lifecycle TCO models that incorporate validated fuel‑savings, re‑coating intervals and in‑water cleaning costs. Consider performance‑linked procurement where suppliers guarantee measured fuel benefits.
- Technology & partnerships: For suppliers, secure access to next‑generation actives and resin technologies either through in‑house R&D acceleration or through strategic partnerships and licensing. For buyers, use pilot programmes to de‑risk adoption of novel systems on a cohort of vessels before fleet‑wide roll‑out.
- Commercial models & M&A: Expect consolidation opportunities where established players acquire speciality chemistries or service providers to round‑out offerings. Investors should prioritise assets that combine validated performance data with scaleable service models and intellectual property protection.
90/180/360‑day playbook
- 90 days: Audit fleet or product portfolios for regulatory exposure, identify high‑value assets for pilot trials, and initiate supplier dialogues requesting performance validation data and third‑party test protocols.
- 180 days: Run controlled pilot trials, negotiate performance clauses tied to fuel‑consumption metrics, and map supply‑chain resilience for critical resin and active ingredients.
- 360 days: Finalise roll‑out decisions informed by pilot outcomes, pursue strategic partnerships or M&A to fill capability gaps, and embed coating lifecycle economics into capital planning and emissions reporting.
What the full PW Consulting report contains (high level)
The complete study builds a repeatable decision framework for 2026 and beyond. Core deliverables include:
- Methodology and assumptions underpinning our market model (historical analysis 2020–2025, verified supplier intake and primary interviews).
- Comprehensive forecast to 2032 with scenario variants reflecting regulatory acceleration and technology adoption curves.
- Competitive profiles and capability matrices for leading suppliers, including R&D pipelines, manufacturing footprints and commercial routes to market.
- Regulatory scenario analysis and compliance roadmaps tailored to buyers and suppliers.
- Go‑to‑market playbooks, procurement templates and M&A heatmaps focused on the three most attractive routes to value creation.
- Practical case studies: validated fuel‑savings trials, offshore foundation coatings pilots, and in‑water cleaning programmes that illustrate lifecycle economics.
To preserve the report’s commercial value as a strategic decisioning tool, detailed regional and application revenue breakdowns as well as type‑level revenue tables are included only in the full deliverable.
Final perspective
The Marine Anti‑Fouling Coatings market entering 2026 is not a static materials market — it is an ecosystem challenge combining chemistry, marine operations, regulatory compliance and digital services. Organisations that treat coatings as a tactical line item risk higher lifecycle costs, emissions exposure and regulatory non‑compliance. Conversely, players that integrate validated performance claims, partner to access differentiated actives, and adopt lifecycle procurement practices will extract the most value as the market expands at the forecasted mid‑single‑digit CAGR through 2032.
PW Consulting’s full report equips decision‑makers with the granular inputs and executable playbooks required to act confidently in 2026. For access to the full dataset, detailed segment tables and supplier scorecards, please visit our report page or contact our industry team to arrange a briefing.
For detailed analysis of this topic, please visit the official page: Marine Anti-Fouling Coatings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Bagged Salt Market — 2026 Strategic Primer
Executive summary
As companies finalize budgets and strategic plans for 2026, a calibrated understanding of the bagged salt market is essential. PW Consulting’s latest market intelligence positions the industry on a steady-growth trajectory: using 2025 as the base year, the global bagged salt market reached a multi‑million USD scale and exhibits a baseline compound annual growth rate (CAGR) of roughly 4.0% over the 2026–2032 forecast horizon. Our historical view (2020–2025) shows a resilient recovery from cyclical pressures with demand drivers that differ materially by end‑use and channel.
Bagged Salt Market
This briefing is designed as a high‑signal trailer: it synthesizes the implications of the full study — markets, players, regulatory dynamics, and actionable playbooks — while intentionally withholding the report’s granular segment numbers so you will consult the source for detailed breakdowns and downloadable models.
Bagged Salt Market
Market trajectory and key inflection points to watch in 2026
-
Continuing growth with structural nuance — The market is expected to expand from its 2025 base into the forecast period, reflecting steady demand across de‑icing, industrial feedstock, and specialty commercial uses. Aggregate growth is moderate (CAGR ~4.0%), but the underlying drivers vary by seasonality, geography and application.
Bagged Salt Market -
Seasonal volatility remains a strategic factor — Weather variability and winter severity drive short‑term procurement cycles and working capital swings for manufacturers and resellers. Inventory management and flexible logistics are high‑return levers.
-
Input and price signals — Broad industry reporting shows salt production and distribution remain substantial in scale, with stable average unit values for bulk and packaged products in recent public data. Expect pricing sensitivity in tight winter seasons and in regions with concentrated supply points.
-
Regulatory and ESG inflection — Environmental requirements for salt handling, runoff, and packaging are intensifying. Compliance and demonstrable mitigation measures will shift procurement preferences toward suppliers that can document lower environmental impact and reliable end‑to‑end stewardship.
Why this matters for 2026 decision‑makers
-
Procurement and supply‑chain resilience: With the market's moderate growth profile, incremental supply‑side shocks (plant maintenance, logistic constraints, labor issues) can create outsized price and availability impacts during peak demand windows. Short‑term tactical steps — longer lead contracts for key seasons, inventory hedging strategies, and multi‑supplier sourcing — must be balanced against working capital objectives.
-
Portfolio and channel strategy: Companies with exposure to multiple end‑uses should reassess portfolio mix given differing margins and growth outlooks. Specialty products and value‑added blends are increasingly important to capture premium channels (commercial snow‑management, specialty industrial customers), and investment here can outpace growth in commoditized segments.
-
Capital allocation and M&A: The industry’s structure favors players with scale in production, packaging and distribution. For 2026, inorganic growth remains a pragmatic pathway to secure geographic fill‑ins, gain packaging capacity, or acquire specialty formulations. Firms should prioritize targets that offer immediate synergies in distribution or seasonal storage.
-
Pricing architecture and customer contracts: Dynamic pricing clauses tied to seasonal indices, index floors for critical raw inputs, and capacity reservation fees are effective: they preserve margin during peak demand while keeping customers committed. Revisit contracting language to reflect volatility observed in recent seasons and to de‑risk both suppliers and buyers.
-
ESG and stakeholder value: Visibility into sourcing footprints, handling of brine and runoff, and packaging recyclability are no longer table stakes — they are commercial differentiators. Buyers increasingly incorporate supplier ESG performance into vendor selection; producers must operationalize traceability and compliance to protect market access.
Competitive landscape — strategic profiles and implications
The bagged salt market is characterized by a small set of well‑established producers and regional specialists that together determine supply flexibility and price dynamics. Below we profile core players and pragmatic strategic implications for competitors, procurement teams and potential investors.
-
American Rock Salt Company (Mt. Morris, NY) — Strength: high underground‑mine throughput and established logistics for de‑icing. Strategic implication: its capacity and operational scale make it a natural partner for large municipal and highway contracts. For buyers, lock‑in options or multi‑year agreements can secure access during peak seasons. For competitors, incremental efficiency improvements in packaging or last‑mile logistics are required to counter its scale advantage.
-
Compass Minerals (Overland Park, KS) — Strength: diversified feedstock (rock and evaporated salts) and integrated distribution networks from major mines. Strategic implication: Compass’s recent fiscal disclosures underscore disciplined capacity utilization. Firms evaluating partnership or supplier rationalization should consider the benefits of stable year‑round supply versus localized cost advantages from smaller suppliers.
-
Morton Salt (Chicago, IL) — Strength: brand strength across consumer and industrial channels, broad product slate including specialty and food‑grade salts. Strategic implication: Morton's channel reach offers premium pricing opportunities in retail and specialty segments. Competitors should consider channel specialization or private‑label strategies to protect margin erosion in retail corridors.
-
Gunther Salt (St. Louis, MO) — Strength: regional distribution and product variety serving commercial, institutional and municipal customers. Strategic implication: regional players retain renewal advantages through local relationships and rapid replenishment capabilities; national players should evaluate bolt‑on acquisitions to close regional service gaps.
-
K+S Aktiengesellschaft (Hannover, Germany) — Strength: global portfolio and cross‑border supply capabilities to serve industrial and food markets. Strategic implication: multinational firms and industrial buyers value K+S for supply security and compliance pedigree; domestic players should pursue operational differentiation or niche product lines to defend against imports in regions with cross‑border exposure.
Recent public developments reinforce these strategic imperatives: American Rock Salt’s 2026 operational communications emphasize strong production continuity, and Compass Minerals’ latest fiscal update highlights capacity utilization trends that are shaping supply availability for the 2026 planning cycle.
Risks, regulation and industry “noise” to monitor
-
Regulatory environment: Recent industry data confirm the chemical sector captures a large share of salt demand and that production and usage volumes remain significant nationally. Regulators are sharpening focus on brine management, stormwater controls and road salt impacts on freshwater — anticipate stricter local ordinances and procurement specifications in the near term.
-
Supply concentration and geographic exposure: A limited number of mines and plants supply substantial portions of the market. This concentration creates vulnerability to regional outages and maintenance cycles; scenario planning should quantify the impacts of short‑term production disruptions on procurement costs and service levels.
-
Market noise vs. signal: Not every weather event or short‑term price spike signals a structural shift; our scenario suite differentiates transient shocks from persistent trend changes. Use those scenarios to stress‑test contract language and inventory strategies.
-
Stable unit values reporting: Publicly available industry analyses indicate relative stability in average unit values across bulk and packaged salt in recent reporting — a useful baseline when modeling price exposure.
What PW Consulting’s full report delivers — practical contents
The full PW Consulting Bagged Salt Market study is designed for immediate operational use by procurement teams, commercial leaders, strategic planners and M&A professionals. Highlights include:
- Proprietary forecast model (2026–2032) with scenario toggles and downloadable datasets (USD, Million).
- Demand driver decomposition by end‑use and channel (methodology and elasticities included).
- Supply‑side mapping and a risk heatmap of production nodes, logistics corridors and seasonal bottlenecks (interactive GIS layer included in the report package).
- Supplier scorecards and playbooks for procurement (performance, capacity, ESG readiness — anonymized benchmarking included).
- Commercial strategy toolkits: pricing clauses templates, channel segmentation playbooks, and packaging/brand premiuming strategies.
- M&A and investment screening framework: target prioritization and quick‑win integration checklists tailored to bagged salt economics.
- Regulatory compliance checklist and mitigation playbook for brine/runoff, storage and transport.
Note: to preserve the strategic value of the report and align with client confidentiality, this primer omits the granular regional and application splits and the full numeric segmentation tables included in the paid study. Those details, along with the interactive model, are available on the report page.
Immediate actions for Q1 2026
- Update 2026 procurement strategy using a 4.0% CAGR baseline and run upside/downside scenarios for winter severity.
- Negotiate capacity reservation or indexed pricing for peak seasons; include force majeure and allocation clauses informed by our scenario outputs.
- Inventory optimization: blend safety stock with seasonal forward buys to balance cash and availability risks.
- ESG and compliance: initiate supplier audits for runoff and storage controls; prioritize partners with demonstrable mitigation programs.
- Shortlist M&A or partnering targets using our supplier scorecard to close geographic or channel gaps.
Conclusion & next step
The bagged salt market for 2026 is not a single homogeneous opportunity — it is a portfolio of interrelated plays across seasonality, geography and end‑use. PW Consulting’s full report equips leaders with data, scenarios and executable playbooks to convert the market’s moderate growth and stability into predictable commercial advantage. For access to the complete dataset, interactive forecast model, and the detailed segment intelligence omitted here, please visit the full report page or contact PW Consulting for a briefing and model walkthrough.
For detailed analysis of this topic, please visit the official page: Bagged Salt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hydrogenated MDI Market Poised for 5.22% CAGR Through 2032
By pmarketresearch, 2026-07-09
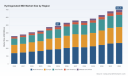
Hydrogenated MDI (H12MDI/HMDI) Market — Strategic Prelude for 2026 Decision-Makers
Executive snapshot
As PW Consulting’s Chief Industry Analyst, I present a concise strategic preview of our comprehensive Hydrogenated MDI Market study (base year: 2025; historical: 2020–2025; forecast: 2026–2032). The market’s steady expansion — underpinned by a compound annual growth rate (CAGR) of approximately 5.22% — is reshaping supplier strategies, downstream formulations, and capital allocation choices across polyurethane value chains. Measured in USD (Million), the market has grown from roughly USD 359 million in 2020 to about USD 491 million in 2025 and is projected to approach roughly USD 696 million by 2032. This trajectory signals meaningful, sustained opportunity for suppliers, converters, and end-users who can navigate supply, regulatory, and technology inflection points.
Hydrogenated MDI Market
Why this preview matters for 2026 planning
-
Investment timing: With mid-decade capacity additions and targeted product roadmaps by key producers, 2026 is a pivotal year to decide whether to secure long-term offtake, invest in backward/forward integration, or prioritize alternative chemistries.
Hydrogenated MDI Market -
Commercial positioning: The market’s structure — notably its high top-tier concentration — rewards scale, integrated feedstock strategies, and differentiated technical support. Our report quantifies concentration metrics and maps how these translate into pricing leverage, logistics resilience, and customer lock-in.
Hydrogenated MDI Market -
Regulatory and safety governance: Diisocyanate classification continues to tighten global handling standards; companies that preemptively invest in compliant processes and training will reduce operational risk and gain access to premium industrial and coatings segments.
Market dynamics: what is actually driving growth
The demand profile for hydrogenated MDI stems from a convergence of technical performance requirements and sustainability pressures. H12MDI/HMDI’s cycloaliphatic character offers improved light stability, lower yellowing, and enhanced mechanical performance relative to many aromatic alternatives — making it the material of choice for durable coatings, premium foams, elastomers, and specialty adhesives. Simultaneously, downstream trends — waterborne systems, low-VOC regulations, and electrification-driven automotive interiors — are expanding use cases for hydrogenated diisocyanates.
-
End-market pull: Automotive, architectural and industrial coatings, and high-performance polyurethane systems are key demand engines. Shifts to waterborne and low-VOC formulations increase the technical premium commanded by hydrogenated variants.
-
Supply-side adjustments: Recent capacity initiatives and producer-led vertical integration are reducing structural supply risk in some regions while concentrating market power. These moves will influence contract terms, spot availability, and grade diversity through 2032.
-
Regulatory overlay: Global diisocyanate regulations (notably in Europe and reflected in industry associations’ guidance) create elevated compliance costs and handling requirements. Firms with advanced safety systems and training protocols can convert regulatory compliance into commercial advantage.
Competitive landscape — players and strategic posture
The hydrogenated MDI market exhibits significant concentration at the top, and strategic intent among incumbents is clear. Leading manufacturers combine product portfolios, branded grades, and technical services to defend premium segments and extend applications into coatings, dispersions, and specialty foams.
-
Covestro AG (Leverkusen, Germany) — a recognized provider of hydrogenated MDI grades (Desmodur W family). Covestro competes on grade breadth and application know-how, targeting polyurethane elastomers, adhesives, and coating systems where weathering and aesthetic longevity are mission-critical.
-
Evonik Industries AG (Essen, Germany) — markets high-performance crosslinkers (e.g., VESTANAT H12MDI) and emphasizes light-stable, dispersion-friendly chemistries for premium coatings and advanced polyurethane systems. Evonik’s strength lies in coupling specialty chemistries with formulation science.
-
Wanhua Chemical Group Co., Ltd. (Yantai, China) — notable for operational scale and integration. Wanhua is an industrial-scale HMDI producer with strategic capacity in China and an active program to expand hydrogenated isocyanate output. Recent public filings and presentations demonstrate a concerted move to capture growing demand in coatings and automotive applications.
These incumbents are not merely competing on tonnage; they are optimizing feedstock integration, grade differentiation (viscosity, functionality, and impurity profiles), and downstream partnerships. The result is a market where the top three players control a majority share, and the top five capture a substantial supermajority — a configuration that shapes contract terms and innovation pathways.
Recent developments and their strategic implications
-
Capacity expansions: Announcements around increasing hydrogenated MDI output are material. Expansions on the order of tens of thousands of tonnes annually — when executed — change regional supply balances and open opportunities for new formulations that had previously been constrained by availability.
-
Technical outreach: Industry presentations highlighting hydrogenated MDI as an enabler for waterborne dispersions and low-VOC coatings suggest a proactive commercial pivot toward environmentally driven formulations. This is an early signal that producers view coatings and dispersions as growth vectors, not just niche specialties.
-
Integration and feedstock security: Firms operating integrated MDA hydrogenation technology and broad isocyanate capacity are better positioned to manage margin volatility. Integration reduces feedstock exposure and supports premium grade development for advanced applications.
-
Compliance and safety: Regulatory pressures on diisocyanates are increasing compliance costs and creating entry barriers for smaller converters. Those that proactively implement robust handling and training systems will gain preferential access to customers prioritizing supply-chain resilience.
Core takeaways for 2026 corporate action
-
Sourcing strategy: Negotiate flexibility into offtake agreements — blends of firm volumes and indexed spot exposure protect against both shortage-driven price spikes and margin compression from new capacity.
-
Product roadmap prioritization: Invest in formulations that exploit hydrogenated MDI’s light stability and low-VOC compatibility. Winning formulations will command premium pricing in segments where performance and aesthetics matter.
-
CapEx and partnership evaluation: For chemical producers, evaluate selective capacity additions in light of forecast demand growth and competitor expansions. For converters, consider strategic alliances or equity partnerships to secure feedstock access.
-
Regulatory readiness: Allocate resources to safety, worker training, and compliance documentation now; delay risks lost contracts and costly retrofits later.
-
Distribution and logistics: Optimize warehousing and transport for specialized grades (low-viscosity, stabilized products) to avoid formulation disruptions and support just-in-time manufacturing for coatings and adhesives customers.
What the full PW Consulting report delivers (practical, executable content)
Our complete Hydrogenated MDI Market study is designed as an operational playbook for 2026 and beyond. It contains:
-
Validated top-line market sizing and a transparent forecast model (2026–2032) benchmarked to historical performance (2020–2025) — all figures presented in USD (Million) with scenario sensitivities for low-, base-, and high-demand pathways.
-
Competitive scorecards that assess production footprints, branded grades, technical service capabilities, and strategic initiatives for the leading suppliers.
-
Commercial templates: negotiation levers for offtake contracts, risk-adjusted pricing models, and inventory optimization frameworks adapted to hydrogenated MDI’s supply characteristics.
-
Regulatory and safety playbooks: compliance cost estimates, certification checklists, and workforce training roadmaps tailored to diisocyanate handling requirements.
-
Go-to-market matrices mapping technical features (e.g., light stability, reactivity profiles) to prioritized end-markets and advisory recommendations for product development sequencing.
-
Investment diligence annexes: capex sizing, break-even analysis, and sensitivity testing for greenfield and brownfield expansions.
Because this preview follows a deliberate “trailer” approach, we have withheld granular subsegment tables and region/application percentage breakdowns from this summary. Those detailed matrices, supplier-by-supplier volumes, and pricing bands are included in the full report to support procurement, R&D prioritization, and M&A diligence.
How to use this analysis in boardroom decisions
-
Frame 2026 budget cycles around three scenarios (conservative, baseline, accelerated) using the report’s forecast outputs and trade-off analytics to justify capital and R&D spend.
-
Use the supplier scorecards to benchmark current partners and identify gaps in feedstock security or technical support; consider dual-sourcing or strategic inventory buffers where exposure is unacceptable.
-
Leverage regulatory playbooks to lower insurance and compliance costs—quantified readiness reduces both near-term operating risk and long-term liability.
Concluding perspective
The hydrogenated MDI market is maturing from a technically niche specialty into a structurally important segment of the polyurethane value chain. With a steady CAGR of roughly 5.22% and clear supply-side moves, 2026 is the year to translate strategic intent into procurement terms, product roadmaps, and capital commitments. PW Consulting’s full study equips decision-makers with the granular data, contract tools, and regulatory blueprints needed to act confidently. For companies that move early — securing feedstock, aligning formulations to low-VOC trends, and hardening compliance systems — the next six years offer both defensible growth and the chance to command a premium in high-value applications.
To access the detailed regional and application breakdowns, supplier volumes, and the actionable annexes referenced above, please visit our report page or contact the PW Consulting research team. The preview establishes the strategic horizon — the full report provides the tactical map.
For detailed analysis of this topic, please visit the official page: Hydrogenated MDI Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: ATBC Market to Reach USD 411.0 Million by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-09
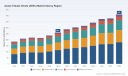
Acetyl Tributyl Citrate (ATBC) Market: Strategic Intelligence for 2026 Decision‑Making
Executive preview
As PW Consulting’s lead industry analyst, this briefing frames why the Acetyl Tributyl Citrate (ATBC) market should be on every chemical, packaging, and medical device executive’s strategic agenda in 2026. We blend an evidence‑based market trajectory with direct operational levers — from raw‑material exposure and regulatory tailwinds to supply‑chain playbooks and competitive posture — to make this report actionable for boardrooms and deal teams. The narrative below demonstrates the analytical depth of our full study while preserving proprietary segment-level cells, price curves and scenario tables that are accessible through our source portal.
Acetyl Tributyl Citrate (ATBC) Market
Market trajectory at a glance (data foundation)
ATBC has moved from a modest specialty plasticizer into a strategic industrial niche with sustained growth momentum. On an aggregate basis the market grew from USD 185.36 Million in 2020 to USD 261.0 Million in the base year 2025. Our forecast coverage extends through 2032, with the market projected to reach USD 411.0 Million by 2032. The modeled compound annual growth rate for the forecast window (2026–2032) is 6.98%.
Acetyl Tributyl Citrate (ATBC) Market
- Historical progression (2020–2025): USD 185.36M (2020) → 209.70M (2021) → 218.49M (2022) → 215.72M (2023) → 235.92M (2024) → 261.00M (2025).
- Near‑term to 2032 forecast: USD 287.62M (2026) → 303.22M (2027) → 316.42M (2028) → 342.68M (2029) → 372.90M (2030) → 377.93M (2031) → 411.00M (2032).
These headline numbers underpin all downstream analysis in the report: demand scenarios, price sensitivities, and capital allocation models. They also serve as the baseline for comparative benchmarking against adjacent plasticizers and bio-based additives.
Acetyl Tributyl Citrate (ATBC) Market
Why 2026 is a strategic inflection point
- Regulatory consolidation and product re‑qualification cycles are peaking in several jurisdictions in 2026 — creating windows for suppliers with compliant documentation and food/pharma grades to capture share.
- Supply‑side adjustments — driven by feedstock volatility and targeted capacity investments — are creating differentiation opportunities for integrated producers versus merchant distributors.
- End‑market demand is bifurcating: higher‑specification food contact and medical applications are growing faster than some industrial volumes, driving premiumization for certified grades.
In short, 2026 is not just another year on the curve; it is the moment when strategic choices on sourcing, certification, and customer segmentation will determine whether a company captures outsized margin expansion or remains in a commoditized path.
Dynamics that will determine winners
- Feedstock economics and margin sensitivity — ATBC production depends primarily on citric acid and n‑butanol. Citric acid is unusually influential on cost structure, representing a dominant share of manufacturing operating expense. The report models cost pass‑through scenarios and margin breakpoints so commercial teams can negotiate smarter offtake and indexation terms.
- Regulatory and product acceptance — ATBC holds registrations under REACH and remains compliant with EU cosmetic and food contact frameworks. The compliance burden favors producers with robust documentation and testing regimes; our due‑diligence templates allow purchasing and regulatory teams to accelerate supplier qualification.
- Quality segmentation — demand for food‑ and pharma‑grade ATBC is expanding, creating routes to premium pricing that hinge on traceability and particulate control. The study outlines the certification investments required and their payback horizons.
- Supply disruptions and regional price spreads — localized citric acid shortages and regional price spikes have material commercial impact. We document recent price moves and model their effect on EBITDA across typical producer archetypes.
Raw materials and operating leverage — practical implications
Two operational facts are critical for 2026 planning. First, citric acid accounts for the majority share of ATBC operating expenses, making producers highly exposed to citric acid spot and contract dynamics. Second, citric acid markets are showing regional dislocation: for example, certain Southeast Asian supply pockets experienced upward price pressure in mid‑2026, while North American contract prices have shown moderation. Our report includes region‑aware cost models and stress tests that quantify P&L sensitivity to these movements so procurement and finance teams can set hedging thresholds and renegotiation triggers.
Competitive landscape — structure and strategic behavior
The ATBC market exhibits moderate concentration: the top three suppliers control a majority share of capacity, and the top five increase that concentration further. This structure creates differentiated battlegrounds — technology and quality, geographic coverage, and integrated feedstock access — where players execute distinct strategies.
- Jungbunzlauer (Basel, Switzerland) — a vertically integrated, bio‑based supplier positioning CITROFOL® BII for high‑spec food contact, PVC and medical uses. Recent moves include a U.S. manufacturing footprint expansion and continued publication of technical dossiers supporting additional applications (sealants, adhesives, and enteric coatings). These steps reduce time‑to‑market in North America and deepen regulatory credibility.
- Vertellus Holdings LLC (Indianapolis, USA) — a specialist in citrate esters with a strong emphasis on food packaging and medical device plasticizers. Their technology and formulation support make them a natural partner for OEMs seeking high reliability and regulatory support.
- Major regional producers and exporters (selected Asia players) — several established Indian and Chinese manufacturers operate at scale with cost advantages for industrial and PVC markets and are increasingly upgrading capabilities for food/pharma specifications. Their competitive playbooks focus on capacity utilization, export networks, and incremental quality upgrades.
- Distributors and specialty suppliers — market access players provide fill‑to‑spec logistics, small‑lot supply and niche grades for R&D and specialty applications. Their value is executional — speed to sample, documentation bundles, and localized inventory buffers.
The full report contains supplier scorecards, capability maps and a five‑layer competitive heat map (technology, compliance, cost, distribution, and innovation) that will help commercial teams prioritize partners and procurement auctions.
Recent developments to watch (illustrative)
- Jungbunzlauer: continued product catalog updates expanding technical use cases; acquisition of U.S. capacity to shorten delivery cycles and support pharmaceutical excipient initiatives.
- Market level: ongoing REACH registration realities and updated cosmetic regulatory references have elevated documentation requirements for European market access.
- Raw material: notable regional citric acid price moves have emerged in 2025–2026, underlining the need for dynamic cost modeling and multi‑sourcing strategies.
What PW Consulting’s full ATBC study delivers (practical, deal‑ready outputs)
- Five demand scenarios (base, bull, bear, technology‑shift, and regulatory shock) with revenue implications through 2032.
- Granular price and margin model — feedstock‑aware, regionally adjusted, and stress‑tested against recent citric acid volatility.
- Supplier scorecards and readiness assessments (food/pharma certification, supply continuity, backward integration, and R&D pipeline).
- Go‑to‑market and commercial playbooks for producers and distributors, including recommended contract templates and indexation clauses for 2026 negotiations.
- Target screening for M&A and contract manufacturing partnerships, with an acquisition prioritization matrix and integration risk checklist.
- Regulatory matrix and dossier checklist mapped to major markets — timed to upcoming re‑qualification windows and compliance audits.
- Interactive dashboards (accessible via our client portal) that allow slicers by application class, grade, and scenario without exposing proprietary sub‑segment cells in this public preview.
How executives should use this intelligence in 2026
- Procurement: institute dynamic indexation and dual‑sourcing clauses keyed to citric acid movements and contract escalation bands identified in our price model.
- Commercial: prioritize food and pharmaceutical customer segments with a tailored certification timeline; deploy premium price architecture where traceability and documented safety deliverable are required.
- Operations & Capex: evaluate brownfield upgrades (filtration, GMP lines) versus greenfield capacity focused on regional supply gaps highlighted in our scenario maps.
- M&A & Strategy: use the supplier heat map and target screening to identify tuck‑ins that deliver regulatory dossiers, regional warehousing, or backward integration into citric acid supply chains.
Closing — the strategic value of this study
For 2026, the ATBC market presents a dual opportunity: those who rapidly align certification, supply security and customer segmentation can capture premium growth; those who delay will face increasing margin pressure from feedstock volatility and regulatory compliance costs. This report converts market conviction into executable decisions — procurement clauses, capex prioritization, M&A targets, and near‑term commercial plays — all built on the published market trajectory and robust scenario analyses.
To access proprietary segment tables (regional, type, application), price curves, supplier scorecards and the interactive dashboards that underpin the recommendations above, please visit our report page or contact PW Consulting’s ATBC research desk. The preview provided here demonstrates our methodological rigor while reserving the granular cells that deliver competitive advantage to subscribers and clients.
For detailed analysis of this topic, please visit the official page: Acetyl Tributyl Citrate (ATBC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rice Husk Ash Market to Reach USD 343.0 Million by 2032 at 5.0% CAGR
By pmarketresearch, 2026-07-09
Rice Husk Ash Market: Strategic Imperatives for 2026 Decision-Making
As businesses plan capital allocation, sourcing strategies, and product roadmaps for 2026, Rice Husk Ash (RHA) is emerging from the margins of industrial by‑products into a strategically important material class. PW Consulting’s latest market study — anchored on a 2025 base year and a seven‑year forecast horizon to 2032 — positions RHA within a predictable growth arc that is both investible and operationally complex. The market expanded from a roughly USD 192 million footprint in 2020 to about USD 244 million in 2025 and is projected to reach approximately USD 343 million by 2032, reflecting a compound annual growth rate of 5.0% over the forecast period. These headline numbers are the entry point; the real value for executives comes from understanding where price, policy, supply chain and product differentiation converge to create windows of opportunity in 2026 and beyond.
Rice Husk Ash Market
Why RHA matters to corporate strategy this year
-
Decarbonization-linked demand: RHA’s role as a supplementary cementitious material (SCM) and as a source of biogenic silica aligns directly with corporate decarbonization strategies and buyer mandates in green construction and metallurgy. Regulatory levers such as EU carbon pricing and emissions trading are intensifying the commercial incentive to substitute clinker and other carbon‑intensive inputs with certified biogenic materials.
Rice Husk Ash Market -
Value capture through processing: Not all RHA is equal. Controlled combustion and post‑combustion beneficiation determine amorphous silica content, particle size distribution, and pozzolanic performance. Producers that invest in quality control and high‑value downstream processing can convert a low‑margin by‑product into specialty silica grades commanding premium placement in refractories, specialty ceramics and high‑performance concrete formulations.
Rice Husk Ash Market -
Supply chain and geopolitical risk: Export controls and tariffs on agricultural waste from key Asian producing nations, combined with rising transport surcharges for certified bulk shipments, are reshaping trade flows and raising landed costs in import‑reliant markets. For multinational off‑takers, this elevates the importance of near‑sourcing, strategic inventory positioning, and contractual protections in feedstock supply agreements.
-
Consolidation and concentration: The market exhibits material concentration among a small set of integrators and specialists. Our competitive concentration metrics indicate meaningful market share controlled by the top three and top five suppliers, creating both negotiating leverage for dominant players and white‑space for challengers with differentiated technical capabilities or captive feedstock.
What the PW Consulting report delivers — operational, boardroom‑ready content
-
Quantified market sizing and forecasting (historical 2020–2025, forecast 2026–2032) including topline scenarios sensitive to feedstock availability, transportation cost curves and regulatory tightening.
-
Supply chain mapping and raw‑material economics: granular models that translate rice husk availability and combustion protocols into usable RHA product buckets and delivered cost ranges (our primary research captures current ex‑works price bands and freight dynamics).
-
Regulatory and sustainability matrix: a decision‑grade assessment of compliance requirements, certification pathways for pozzolanic claims, and emissions incentives across major trading jurisdictions.
-
Competitive benchmarking and supplier scorecards: technical capability, capacity, vertical integration, and go‑to‑market models for incumbent and emerging players, together with an M&A and partnership thesis.
-
Commercial playbooks: tender and contract templates, offtake structures, pricing indexation approaches and procurement negotiation levers designed for buyers and for new‑entrant producers.
-
Standalone financial models and project screeners: plant economics for RHA processing, silica extraction units and modular combustion installations, with sensitivity to energy costs and carbon pricing.
-
Case studies and field verification: examples of successful integration of RHA into cement blends, refractory formulations and silica extraction operations, plus interview excerpts from buyers, mill operators and technology suppliers.
Competitive landscape: profiles and strategic implications
Market dynamics are being shaped by a mix of vertically integrated agricultural groups, specialized chemicals firms, regional mill operators and niche refractory distributors. Several archetypes are visible:
-
Integrated mill operators with captive RHA streams — these players monetize the by‑product through downstream supply into cement, construction and local industrial buyers. Their advantages are feedstock security and logistics optimization that lower delivered cost and supply risk.
-
Specialist processors and materials companies — firms focusing on producing high‑amorphous‑silica RHA or converting ash into dispersible silica capture higher value per tonne but require capital for controlled combustion and post‑processing technologies.
-
Global chemicals entrants and distributors — large chemistry groups and refractory specialists are moving into bio‑circular silica markets through strategic plant launches and partnerships, lifting standards for quality, traceability and global supply chain compliance.
Key industry participants exemplify these archetypes. Some operate integrated milling or biomass combustion platforms, securing captive feedstock and supplying cement and construction markets; others concentrate on producing high‑amorphous silica for refractory and metallurgical uses. Meanwhile, specialist distributors and chemical groups bring scale, technical certification capabilities and access to international buyers. Recent notable developments underscore the shifting landscape:
-
Capacity additions in Southeast Asia, including commissioned rice‑husk biomass plants, are starting to deliver predictable RHA volumes and are expected to form the backbone of regional supply chains.
-
Strategic acquisitions in the biomass assets space are consolidating supply in certain markets, supporting more formalized off‑take arrangements between power plant operators and industrial consumers.
-
Major chemicals firms have initiated commercial production of bio‑derived, highly dispersible silica — an important validation of RHA’s potential as a high‑value feedstock and a signal that premium market segments will professionalize rapidly.
Operational and commercial headwinds to plan for in 2026
-
Feedstock variability and quality: controlled combustion is a non‑trivial technical hurdle. Amorphous silica content and residual carbon levels determine product acceptance in engineering applications. Due diligence must include lab‑validated performance data and on‑site combustion audits.
-
Trade and policy friction: tariffs and export controls on agricultural waste are shifting commercial flows and increasing the premium for local or regionally sourced RHA. Buyers that remain dependent on long‑haul supply should model duty and logistics surcharges explicitly into procurement strategies.
-
Logistics and certification costs: demand for certified pozzolanic material is inflating transport and handling costs for bulk RHA shipments. Contract structures that share certification burdens or that invest in localized beneficiation can mitigate per‑ton volatility.
-
Market concentration: the top tier suppliers hold a substantial combined share of capacity. This creates a two‑edged sword — stability of supply from incumbent names, but also potential pricing power that must be anticipated in scenario modelling.
A concise playbook for executives moving into 2026
-
Secure feedstock through hybrid models — a mix of captive sourcing, long‑term offtake and local spot supply — to balance cost, quality and resiliency.
-
Invest selectively in quality certification and beneficiation capacity: the premium segments reward consistent technical performance and traceability more than low unit price alone.
-
Evaluate partnerships with regional mill operators and biomass plant owners to lock in volumes and co‑invest in processing assets rather than pursuing purely transactional procurement.
-
Model policy scenarios — particularly carbon pricing and trade barriers — in all investment appraisals. A 5.0% CAGR environment amplifies returns for first movers who can also de‑risk feedstock and logistics.
-
Build an M&A screen focusing on technical capabilities (controlled combustion, silica extraction), captive feedstock and distribution reach; these characteristics predictably convert to market power as demand professionalizes.
Where to access the granular intelligence
This briefing is designed as a strategy‑grade preview. The full PW Consulting Rice Husk Ash Market report includes the granular regional and application splits, supplier scorecards, downloadable data tables, contract templates and the detailed financial models you need to translate headline growth into executable investments and procurement decisions. For teams preparing 2026 budgets or evaluating near‑term M&A, the complete dataset and supplier benchmarks are essential to calibrate risk and upside.
Rice husk ash is no longer an incidental residue; it is a material at the intersection of sustainability policy, industrial decarbonization and circular‑economy value creation. For companies that move early to secure quality, logistics and technical differentiation, 2026 offers the chance to convert modest tonnages today into strategically significant product lines for tomorrow.
For detailed analysis of this topic, please visit the official page: Rice Husk Ash Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Manual Cleaning Products Market — Strategic Outlook for 2026 Decision‑Makers
As companies plan investments and portfolio shifts for 2026, the Manual Cleaning Products Market presents a blend of steady expansion, margin pressure, and technology-driven disruption. Our PW Consulting market study (base year 2025, historical window 2020–2025, forecast 2026–2032) models this market at USD 141.7 million in 2025, up from roughly USD 110 million in 2020, and projects growth to roughly USD 197.3 million by 2032 at a compound annual growth rate (CAGR) of 4.9%. This paper distills the report’s strategic value for executives, procurement leads, BD teams, and corporate development groups in 2026 — showing where to act quickly, where to prepare, and where to wait for clearer signals.
Manual Cleaning Products Market
Why this research matters for 2026 decisions
- Investment horizon clarity: A 4.9% CAGR across 2026–2032 signals a market delivering stable top‑line expansion but not runaway growth — optimal for targeted capex and selective M&A rather than broad, high‑beta expansion programs.
- Profitability under pressure: Raw material volatility and rising frontline labor costs compress operating margins in manual cleaning operations, making cost containment, product premiumization, and service/consumables monetization immediate priorities.
- Technology and channel inflection: Hybridization of manual and automated cleaning (robotic integration, modular scrubber attachments) creates opportunities to reposition from one‑time equipment sales to recurring revenue models — particularly relevant for companies considering platform plays or subscription services.
- Regulatory and safety risk management: New and tightening rules (e.g., supplier qualification for raw ingredients, and safety advisories on equipment) require faster product compliance cycles and stronger supplier governance to avoid costly recalls or market access delays.
What the full report delivers — practical, transaction‑ready outputs
- Actionable executive summary with investment thesis and 12‑, 24‑, and 36‑month decision matrices.
- Proprietary market sizing and forecasting model (base 2025; historical 2020–2025; forecast 2026–2032) delivered in editable format, with scenario toggles for demand shocks, raw material price swings, and labor cost scenarios.
- Go‑to‑market playbooks for three strategic pathways: premium product leadership, cost‑efficient commodity supply, and recurring‑revenue services (consumables & maintenance contracts).
- Competitive landscape dossiers and strategic profiles of leading and disruptive players — including product roadmaps, distribution footprints, and partnership strategies.
- Supply chain risk register tied to raw material indices, supplier concentration maps, and mitigation options (dual sourcing, vertical integration levers, hedging strategies).
- Regulatory impact assessment and compliance checklist for European and North American market entry, plus recommended testing protocols for chemical inputs and equipment safety.
- M&A target screening criteria, valuation benchmarks, and synergy realization playbooks specific to manual cleaning product businesses and adjacent robotics/equipment firms.
- Appendices: interview transcripts with industry buyers, trade‑show intelligence harvest (Interclean 2026 observations), and sensitivity analysis supporting price and volume elasticities.
Note: this article is a strategic preview. Detailed sub‑segment tables, regional splits, and line‑item revenue figures are intentionally omitted here and are available in the full report.
Manual Cleaning Products Market
Data‑driven macro insights you can act on now
- Steady base‑market growth enables disciplined reinvestment. The market’s trajectory — from the early‑2020 baseline to the 2025 reference point and on to 2032 — supports disciplined investment into product upgrades, selective automation, and channel expansion while maintaining ROI thresholds that typical private and strategic buyers expect.
- Concentration and competitive tension. Market concentration metrics indicate a mid‑range consolidation state: the top three players do not dominate the market, and the top five capture less than half the market — a structure that favors both innovative niche propositions and bolt‑on acquisitions for growth accelerants.
- Cost and regulatory headwinds are real and actionable. Volatility in plastics and specialty polymers used for packaging and tool components directly pressures COGS, while tightened EU supplier qualification and chemical testing raise time‑to‑market for reformulations and new SKUs. These forces make supplier contracts, material substitution strategies, and compliance investments near‑term priorities.
- Labour economics push automation and service models. Frontline wages and operational overhead in many developed markets are high enough to justify upfront investments in semi‑automated or hybrid cleaning solutions when TCO and uptime benefits exceed hurdle rates.
- Trade shows and product launches are signposts for strategy. The 2026 Interclean cycle highlighted aggressive product rollouts and hybridization: leading robotics firms showcased next‑generation autonomous sweepers and heavy‑duty scrubbers, while several OEMs emphasized compact, battery‑powered manual scrubbers and modular attachments — signals that partners and competitors alike are pivoting toward integrated cleaning ecosystems.
Competitive landscape — strategic positioning of core players
The research includes focused profiles of the market’s most influential and disruptive names. Below is a high‑level synthesis of strategic posture and implications (detailed profiles are in the report):
Manual Cleaning Products Market
- FOAMit (US): Niche commercial entry‑point solutions — an example of vertical specialization around a singular hygiene function. Such focused plays can be attractive acquisition targets for equipment integrators seeking differentiated access points into facilities management contracts.
- Tornado Vacuums (Italy): Strong OEM pedigree in cylindrical scrubbers and compact battery manual scrubbers. Their recent product updates indicate an emphasis on small‑footprint applications and modularity — a defensive response to demand for flexible, low‑capex cleaning options.
- IPC Worldwide (US): Broad professional toolset provider — positioned to bundle manual accessories with larger systems, enabling cross‑sell into long‑standing service contracts.
- KUER & Chancee (China): Aggressive trade‑show presence and product breadth. These manufacturers are amplifying exports and competing on value and rapid development cycles; they are logical partners for strategic rollouts in price‑sensitive markets or OEM white‑label programs.
- Gausium (China): Robotics leader driving hybrid models — their 2026 Interclean launches of advanced autonomous scrubbers show the clear direction toward automating routine manual tasks and monetizing autonomy through software and services.
- Multi‑Clean & Seventh Generation (US): One focuses on commercial chemicals and floor care consumables; the other on biobased, eco formulations for home care. Together they illustrate the bifurcation in demand: institutional buyers seek performance and serviceability, while a growing consumer and retail channel demands sustainability claims validated by testing and supply transparency.
Recent market activity with strategic implications
- Gausium’s high‑profile Interclean 2026 showcase (including a Beetle 2.0 robotic sweeper and heavy‑duty autonomous scrubber) underlines the acceleration of autonomy investment and the need for incumbents to evaluate integration or partnership strategies.
- KUER and Chancee’s trade‑show focus on walk‑behind and high‑performance scrubbers signals intensifying competition from Chinese OEMs for global commercial contracts.
- Tornado’s compact cylindrical scrubber product refresh demonstrates continued market demand for efficient, battery‑powered manual solutions that reduce labor burden while preserving mobility and flexibility.
Priority strategic actions for 2026 (what PW Consulting would recommend)
- Immediate (0–6 months): Run a supplier risk audit tied to plastics and specialty polymers; renegotiate supply buffers and build price‑index‑linked contracts. Fast‑track product safety audits to meet latest equipment safety advisories.
- Near‑term (6–18 months): Pilot hybrid solutions that pair manual equipment with low‑cost automation or telematics to prove TCO improvements; introduce service bundles (maintenance, consumables) to stabilize recurring revenue.
- Medium term (18–36 months): Consider tuck‑ins in robotics or consumables depending on strategic intent: robotics for market leaders seeking margin expansion and defensibility; consumables for players focused on stable, high‑margin repeat business.
- Commercial levers: Move to value‑based pricing in professional channels, expand private‑label partnerships in price‑sensitive markets, and deploy digital channels for direct SMB engagement.
Methodology and confidence indicators
The full study uses a blended methodology: bottom‑up revenue aggregation from equipment, consumable, and service channels; top‑down triangulation against macro indicators; primary interviews with OEMs, distributors, and large end users; and trade‑show intelligence gathered at Interclean 2026 and other industry events. The model includes three scenario tracks (base, upside, downside) and sensitivity tests for key variables: raw material price index, frontline labor cost shifts, and adoption velocity of semi‑automated solutions. Revenue units are expressed in USD Million with 2025 as the base year.
How to use this preview
This executive preview is designed to be a decision‑oriented guide. Use it to align leadership on strategic priorities for 2026, inform procurement negotiations, frame M&A screening criteria, and guide product roadmap debates. For transaction diligence, detailed sub‑segment figures, regional revenue splits, company‑level sales estimates, and our full financial model are provided in the complete PW Consulting report. Those datasets and granular breakouts are intentionally reserved to preserve the actionable advantage for report purchasers.
To obtain the full dataset, scenario models, and company dossiers — including the granular segmentation that underpins the recommendations above — please consult the full Manual Cleaning Products Market report on the PW Consulting portal or contact our industry practice for a briefing and license options.
For detailed analysis of this topic, please visit the official page: Manual Cleaning Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vinpocetine Market Outlook - USD 307.1M in 2025, 3.8% CAGR to 2032
By pmarketresearch, 2026-07-09
Vinpocetine Market 2026 Strategic Preview: What Corporate Leaders Must Know
As PW Consulting’s senior industry analyst, I present a focused strategic preview of the Vinpocetine market to guide 2026 decision-making. This briefing synthesizes the macro trajectory, competitive dynamics, regulatory inflection points, and the practical levers companies can pull to protect or grow value. Consider this a high-fidelity trailer: it demonstrates the report’s analytical depth and decision utility while reserving the full, segment-level intelligence for the comprehensive study available through our source portal.
Vinpocetine Market
Market at a glance (macro picture)
Using 2025 as the base year, our market synthesis shows a mature but steadily expanding global Vinpocetine market—estimated at approximately USD 307 million in 2025—with a compound annual growth rate of about 3.8% across the 2026–2032 forecast window. That trajectory takes the market to a materially larger size by the end of the period under a baseline scenario, reflecting a blend of steady pharmaceutical demand, differentiated regulatory regimes across jurisdictions, and constrained but adaptable supply dynamics.
Vinpocetine Market
Historically, the market moved from the mid‑2020s with stable year-on-year gains through 2025, driven by sustained pharmaceutical applications and continued use in some over‑the‑counter channels. The moderate CAGR we forecast is consistent with a product in the late growth to early maturity phase—one where incremental gains are won through regulatory positioning, quality differentiation, and targeted clinical evidence rather than broad-based demand expansion.
Vinpocetine Market
Why this report matters for 2026 corporate decisions
- Regulatory posture will determine commercial access: Vinpocetine’s regulatory classification varies materially by market. In several major markets it is treated as a pharmaceutical ingredient; in others it remains available in supplement channels but under active scrutiny. That regulatory variability translates into distinct commercial and compliance strategies—and creates winner-take-most outcomes for firms that secure robust dossier support and proactive engagement with regulators.
- Supply concentration creates strategic exposure: The market is concentrated among a handful of high‑quality producers and distributors with established GMP/ICH credentials. Concentration amplifies both pricing stability and supply risk: a single plant disruption, quality event, or export restriction can meaningfully affect global access and near‑term pricing dynamics.
- Clinical evidence is the gating item for long‑term value: Across the portfolio of end uses, a persistent shortfall in large, modern clinical datasets constrains label expansion and premium positioning. Firms that invest in targeted clinical programs or real‑world evidence generation can unlock reclassification opportunities and premium pricing in regulated markets.
- Mature demand favors strategic differentiation over volume plays: Given the market’s moderate growth profile, margin expansion strategies—quality credentials, dossier completeness (DMF/ASMF), and supply security—outperform low‑cost volume strategies except in clear niche geographies where scale is decisive.
Report deliverables that enable action in 2026
Our full study goes beyond descriptive analysis. For executives, business-development teams, and investors preparing 2026 plans, the report includes:
- Scenario‑based forecasts with sensitivity matrices for regulatory shocks, raw‑material constraints, and accelerated clinical outcomes;
- Supplier and distributor scorecards covering manufacturing credentials, dossier coverage, inspection histories, and trade routes;
- Regulatory playbooks for priority markets: required filings, pharmacovigilance expectations, and timelines to market under alternative classifications;
- Go‑to‑market playbooks and commercial models by channel (pharmaceutical, hospital, retail/OTC, and online), with practical checklists for market entry and margin management;
- Risk heatmaps and mitigation guidance covering botanical raw-material exposure, single‑site manufacturing risks, and export/regulatory compliance risks;
- M&A and partnership thesis templates: acquisition filters, valuation sensitivities, and integration checklists for API producers, specialty distributors, and clinical research partners.
Competitive landscape: what to watch
The supplier base mixes long‑established European specialists, large Indian manufacturers with export‑oriented compliance footprints, and Chinese suppliers with broad global distribution. Key industry players we profile in the report include:
- Covex S.A. (Spain) — a veteran manufacturer and supplier with dedicated synthesis facilities and longstanding compliance to ICH/FDA/NCF standards. Their legacy specialization in vinca‑derived APIs positions them as a reference for pharmaceutical‑grade Vinpocetine.
- Alchem International (India) — GMP‑certified, USFDA/EU‑inspected manufacturer and exporter that emphasizes dossier completeness and regulatory support (ASMF/DMF coverage), which is decisive for customers targeting regulated markets.
- Sinoway Industrial (China) — a GMP supplier with deep CoA documentation practices and broad distribution networks, important for buyers balancing cost and speed to market.
- AXXO GmbH (Germany) — a distributor with GMP/GDP and USDMF credentials; plays a crucial role in bridging supply and regulatory support in Europe and other regulated markets.
- Zeon Pharma Industries and Astitva Chemicals (India) — additional GMP producers with export experience; collectively they provide capacity and competitive tension in price and lead‑times.
Collectively, the leading suppliers establish high barriers for entrants that cannot demonstrate consistent GMP compliance, dossier readiness, and reliable logistics. Our competitive benchmarking quantifies these barriers and ranks suppliers on a multidimensional scorecard of quality, regulatory readiness, capacity, and commercial reliability.
Regulatory and raw‑material dynamics: critical decision levers
- Regulatory divergence: Regulators in some jurisdictions classify Vinpocetine strictly as a pharmaceutical active, while others allow its marketing in dietary supplements under varying constraints. The FDA’s ongoing advisories—particularly safety communications relevant to specific populations—raise the risk of reclassification or further label restrictions in the U.S., with downstream effects on demand, labeling, and claims.
- Raw‑material architecture: Vinpocetine is a semi‑synthetic derivative of vincamine, which ties API production to botanical feedstock and specialized synthesis routes. That hybrid upstream model limits rapid capacity expansion and raises the value of dual‑sourcing, backward integration, and validated second‑source suppliers.
- Quality and dossier completeness: Access to high‑value regulated markets is gated by DMFs/ASMFs, inspection history, and traceable CoA chains. Companies lacking dossier or inspection readiness face a multi‑quarter delay to enter regulated channels.
Strategic recommendations for 2026 planning
- Prioritize regulatory hedging: Allocate resources to strengthen dossier libraries, proactive pharmacovigilance, and engagement with regulatory authorities in your top three markets. Prepare submission timelines for DMFs/ASMFs now—delays in 2026 can translate into lost shelf space and deferred revenue.
- Build supply resilience: Implement dual‑sourcing or toll‑manufacturing relationships with suppliers who demonstrate GMP/ICH credentials. Consider limited backward integration or long‑term purchase agreements to secure feedstock and intermediate supply.
- Invest selectively in evidence: Target a focused clinical or real‑world evidence program that addresses the largest regulatory or payer objections in priority markets. Even a small, high‑quality trial or observational program can shift positioning from marginal supplement to accepted therapeutic adjunct in regulated formularies.
- Use M&A and partnerships tactically: Given market concentration among a few high‑quality producers, acquisitions or minority investments in compliant API players can be the most effective way to secure long‑term supply and dossier control.
- Differentiate commercially: For companies competing in mature channels, create differentiated offerings through quality certificates, branded formulations, and bundled regulatory support for downstream customers.
- Scenario‑proof your plan: Embed trigger points in budgets tied to regulatory actions (e.g., restrictive advisories) and to supplier disruptions. That will allow rapid reallocation between defense (safety communications response) and offense (market expansion when regulatory clarity emerges).
Scenario framing: three outcomes to model now
- Baseline (most likely): Continued moderate growth aligned with the 3.8% CAGR as regulated markets absorb current supply while supplement channels stabilize under tighter oversight.
- Downside (regulatory tightening): If major markets accelerate reclassification or tighten claims enforcement, expect demand contraction in OTC channels with a short‑term price shock and rebalancing toward pharmaceutical procurement routes.
- Upside (evidence‑driven expansion): Targeted, credible clinical evidence and coordinated regulatory submissions could expand reimbursed indications and create premium opportunities in several regulated markets—lifting growth above baseline assumptions.
Concluding perspective and next steps
For 2026 planning, Vinpocetine is a classic strategic product: moderate market growth and high commercial variance driven by regulatory outcomes, supply concentration, and the presence (or absence) of modern clinical evidence. Executives who act early—shoring up supply, investing in dossier and evidence, and mapping contingent responses to regulatory moves—can convert a steady market into a source of durable margin and market share.
PW Consulting’s full report provides the granular segmentation, regional and channel breakouts, supplier scorecards, and downloadable scenario models that translate the strategic directions above into executable 90‑ and 180‑day plans. To access the complete intelligence package, including interactive spreadsheets and vendor dossiers, please visit our report page.
For detailed analysis of this topic, please visit the official page: Vinpocetine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Quartz Glass Market to Reach USD 2,216 Million by 2032 at 6.8% CAGR — PW Consulting Insight
By pmarketresearch, 2026-07-09
Quartz Glass Market — 2026 Strategic Primer
Executive snapshot
PW Consulting’s Quartz Glass Market study is designed for executives who must make capital, procurement and M&A decisions in 2026 with limited runway. The global quartz glass market stood at USD 1.42 billion in our 2025 base year and, under our central case, is projected to grow at a 6.8% CAGR through a seven-year forecast window (2026–2032), reaching approximately USD 2.22 billion by 2032. That steady, above-market industrial growth is being driven by a confluence of semiconductor scaling (including EUV and photomask demand), the continued rollout of power electronics for EVs and renewables, and incremental growth in optics, lighting and laboratory segments.
Quartz Glass Market
This primer highlights the report’s strategic value for decisions you must finalize in 2026: where to allocate capex, which suppliers to lock, how to hedge feedstock exposure, when to accelerate vertical integration, and which competitive moves will materially change your position over the next 12–24 months. The full report contains the granular segmentation, supplier scorecards and interactive financial models that underpin the recommendations summarized below; this article purposely illustrates the insights while omitting the detailed segment tables and raw vendor scores to guide you to the full deliverable.
Quartz Glass Market
Why this study matters for 2026 decisions
-
Timing is critical. Mid-decade demand surges for EUV-quality and large-format synthetic substrates have created pockets of lead-time risk for high-purity fused silica and precision components. Capital commitments made in 2026 will determine supply balances for the early 2030s.
Quartz Glass Market -
Complex quality differentiation. Not all quartz is equal: purity, defect density, dimensional tolerances and thermal performance drive customer value in semiconductor and photomask applications. Suppliers that can demonstrate EUV-grade consistency and advanced ovality or flatness tolerances capture premium contracts.
-
Supply-side signal: capacity investments and supplier awards. Recent announcements—in particular large-scale European capacity expansions and supplier recognitions from major OEMs—signal a market reshuffle where capacity and certified OEM relationships will be primary competitive moats.
-
Input-cost dynamics are manageable but shifting. North American feedstock showed mild downward movement in Q1 2026, while broader silicon dioxide indices show a slight upward trajectory into 2026 after inventory-driven declines in 2025. Procurement strategies should balance short-term price relief against an anticipated, gentle recovery.
-
Regulatory continuity lowers near-term trade risk. Quartz glass is listed under HS 70200010 and, as of the latest reviews, has not been subject to specific new import/export controls or environmental surcharges—removing one layer of policy uncertainty for cross-border sourcing and capacity allocation.
What the full report delivers — practical content for direct action
- Top-line market sizing and historical trend analysis (2020–2025) and a transparent forecast engine for 2026–2032 with scenario toggles for low/base/high demand outcomes.
- Demand-driver deep dives covering semiconductor process roadmaps (EUV, advanced nodes), photovoltaic manufacturing cycles, EV power electronics, optics and specialty lamp markets.
- Supply-chain mapping: feedstock sources, synthetic quartz routes, conversion bottlenecks, and a prioritized list of long‑lead, single‑source components.
- Supplier scorecards and vendor risk matrices assessing quality, capacity, geographic footprint, certification status and customer concentration.
- CapEx and margin sensitivity models allowing finance teams to stress-test expansions under differing price and demand curves.
- Scenario playbooks: contract procurement (spot vs. long-term), lean vs. resilience strategies, and M&A and JV frameworks tailored for OEMs, fabs, and component houses.
- Regulatory & raw-material appendix summarizing tariff status, feedstock price indices and environmental compliance considerations.
Note: this primer intentionally omits the granular regional and application splits and the detailed supplier scores contained in the full report. Those tables are often the actionable intelligence buyers and investors need to finalize negotiations and are therefore delivered in the paid research package.
Competitive landscape — strategic read of core players
The quartz glass supplier ecosystem blends legacy materials specialists, regional high-volume producers and precision component fabricators. No single firm dominates the market; leadership is built on a combination of purity capability, OEM certifications, scale of synthetic quartz production and proximity to demand hubs.
-
Tosoh Quartz Corporation (Tokyo) — A heritage materials player pivoting aggressively toward silica glass to capture demand from AI hardware, power electronics and RF systems. Recently recognized by a major OEM, Tosoh’s strategic alignment with chipmakers and broad product portfolio make it a prime partner for long-term supply agreements. Key decision factor: Tosoh’s ability to convert strategic intent into repeatable, certified EUV-grade deliveries.
-
Heraeus Quarzglas (Hanau) — Investing materially in Europe with new flame hydrolysis furnaces and expanded EUV-grade ingot capacity. Heraeus is also deploying AI-enabled quality control for defect detection—an advantage where microscopic defects carry outsized value. Key decision factor: validation timelines for the new capacity and consistency of EUV-grade output.
-
Technical Glass Products & Swift Glass (USA) — These fabricators specialize in finished components, labware and application-specific products with strengths in short-run customization and thermal/mechanical performance. They are natural partners for customers seeking agile supply with technical co-development.
-
Hubei Feilihua (China) — A large-volume manufacturer focused on semiconductor-grade fused quartz with strong cost-positioning. Their scale is a double-edged sword: attractive for volume sourcing but potentially constrained for ultra-high-purity, large-format substrates where specialized processes are required.
-
Specialist precision houses (QSIL, Raesch, Maruwa, MGS, Sintrex) — These firms excel at precision drawing, finishing and custom components. For OEMs requiring bespoke tube, rod, plate or machined parts, these suppliers are often decisive enablers of product differentiation.
Recent industry developments change the competitive calculus: European capacity additions shift some long-term bargaining power; product-line enhancements (improved ovality, tighter flatness tolerances) create new premium tiers; and supplier awards from marquee OEMs accelerate consolidation in the supply chains for high-end, high-purity segments.
Strategic priorities and playbook for 2026
-
Prioritize contract certifications for mission-critical grades. If your product roadmap depends on EUV-grade or large-format photomask substrates, negotiate multi-year supply-and-performance agreements with penalty-and-reward clauses tied to defect rates and delivery windows.
-
Hedge feedstock tactically. Take advantage of short-term relief in certain regions while establishing contingent supply contracts to protect against the modest rebound in silicon dioxide indices forecast for 2026.
-
Invest in upstream assurance. For OEMs and fabs, consider minority equity or joint-venture stakes with high-purity producers to secure allocation without full capex exposure.
-
Target precision fabricators for bolt-on M&A. Small-to-mid market precision component makers can be integrated to shorten lead times and protect IP in specialized optical or thermal components.
-
Implement AI-enabled QC in your incoming-inspection protocols. Suppliers deploying these tools have a demonstrable edge in detecting subsurface defects and improving yield—require transparency on defect-detection methodology as part of supplier selection.
-
Build flexible sourcing geographies. Even though tariffs and controls are not a near-term constraint, geographic diversification reduces concentration risk from single-region outages or capacity bottlenecks.
-
Embed sustainability and recycling clauses into procurement. Recycled quartz and closed-loop programs are emerging as differentiators for capital projects and can reduce long-term feedstock exposure.
Decision triggers and metrics to monitor in 2026
- Feedstock price indices (especially regional silicon dioxide trends).
- Vendor capacity announcements and furnace installations for EUV-grade and large-format ingots.
- Lead times for critical components (ingots, large plates, precision tubes) and trend lines versus booked backlog.
- Defect and yield metrics from pilot runs—especially for EUV-grade and photomask substrates.
- Customer backlog at major buyers in semiconductor and photovoltaic value chains.
How to use the full PW Consulting deliverable
If you are setting procurement budgets, designing a two‑year capex cadence or evaluating strategic acquisitions in 2026, the full Quartz Glass Market report provides the models and scored supplier universe to convert these strategic themes into executable decisions. The paid report includes downloadable scenario models you can plug into your board materials, a procurement negotiation playbook with contract language templates, and a prioritized M&A watchlist aligned to different corporate strategies (volume-scaling, premium-differentiation, or regional resilience).
We have intentionally sketched the strategic landscape and recommendations here while withholding the granular regional and application splits, per-supplier numerical scores and the full financial models. That granularity is the difference between a good negotiation and a market-winning agreement, and it is available in the full report package where you can access the underlying data, sensitivity tables and supplier scorecards.
For guidance tailored to your specific position—buyer, component manufacturer, or investor—contact PW Consulting’s Quartz Glass practice to arrange a workshop where we apply the model to your balance sheet, contract portfolio and technology roadmap.
For detailed analysis of this topic, please visit the official page: Quartz Glass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cyanuric Acid Market to Reach USD 380 Million in 2025 at 5.5% CAGR
By pmarketresearch, 2026-07-09
Cyanuric Acid Market 2026: Strategic Preview for Corporate Decision-Makers
Executive snapshot
As firms prepare their 2026 strategic plans, cyanuric acid is re-emerging as a high-visibility specialty chemical whose market trajectory combines steady demand growth with episodic supply risk. PW Consulting’s upcoming Cyanuric Acid Market study synthesizes a seven-year forecast (2026–2032) anchored to historical performance (2020–2025, base year 2025) and quantifies a compound annual growth rate (CAGR) of 5.5% for the forecast interval. The broader market, valued at approximately USD 380 Million in 2025, continues on a recovery and expansion path, with modelled topline outcomes reaching the mid-hundreds by the end of the forecast window.
Cyanuric Acid Market
Why this matters for 2026 planning
Procurement, manufacturing, commercial and corporate development leaders must treat cyanuric acid as more than a commodity: it sits at the intersection of consumer-driven swimming pool maintenance, municipal and industrial water treatment, and several niche industrial chemistries. The market’s steady CAGR masks finer-grain volatility driven by supply-chain incidents, regulatory enforcement, and shifts in application demand. For 2026, decisions on capacity investment, contract length for offtake agreements, hedging strategies, and M&A prioritization should be informed by three realities that our study explores in depth:
Cyanuric Acid Market
- Structural growth coupled with episodic shocks: baseline demand grows at a mid-single-digit pace, but short-term dislocations can create outsized pricing and availability effects.
- Consolidation pressure: market concentration metrics indicate a modestly concentrated supplier base, which influences negotiation dynamics and strategic options for buyers and potential entrants.
- Regulatory and supply-side complexity: legacy incidents and regulatory actions continue to create tail risks that merit operational contingencies.
Market trajectory: headline figures and what they imply
PW Consulting’s topline model records the market at roughly USD 380 Million in the 2025 base year and applies a 5.5% CAGR across 2026–2032 to map out plausible upper- and lower-bound scenarios. That trajectory signifies durable end-market demand for the chemical, while also providing a quantitative foundation for stress-testing capex and commercial scenarios. In absolute terms, our forecast horizon projects steady expansion with intermittent dips and rebounds aligned to supply events and investment cycles—patterns that are commonplace in specialty chemical segments.
Cyanuric Acid Market
Dynamics and risk drivers
Our Dynamics section dissects the twin drivers of cyanuric acid markets: demand-side evolution (end-use preferences, seasonal consumption patterns, and water-treatment standards) and supply-side constraints (feedstock availability, plant uptime, and concentration of production). Notable inputs include documented supply disruptions: for example, historical force majeure declarations tied to production facilities have repeatedly shown how localized damage can ripple through global availability and commercial terms. Regulatory and trade developments, including post-incident enforcement and trade remediation, are integrated into the scenario suite to quantify contagion effects on price and availability.
Segmentation architecture (high-level)
The market naturally breaks down across product forms, applications and geographies. Our study models demand across granular, powdered and liquid product forms; across primary application clusters such as swimming pools and industrial/water-treatment uses; and across global regional demand centers. As a strategic preview, we deliberately showcase the segmentation framework and its strategic implications, while preserving the report’s proprietary granularity—core split figures and specific regional/application breakdowns are reserved for the full report to support client-level decisioning.
Competitive landscape — what you need to know
The supply side is characterized by a concentrated leading cohort and several mid-tier producers. Market concentration metrics in our analysis indicate that the top three producers account for a substantial portion of total market volume, and the top five capture a material majority—conditions that shape bargaining power, price pass-through and consolidation potential.
- Shandong Wolan Biology Co., Ltd. (Juancheng County, Shandong Province, China) — A producer with direct, commercially-oriented offerings in the cyanuric acid space. Their product portfolio, along with distribution networks, positions them as a decisive regional supplier for Asia-focused buyers and as a competitor for exports into other geographies.
- Hebei Jiheng Chemical Co., Ltd. (Wuyi County, Hengshui City, Hebei Province, China) — Maintains a strong domestic foothold with capabilities tailored to cyanuric acid production. The company is relevant for buyers assessing midstream partnerships or seeking reliable contract manufacturing capacity.
- Shandong Xingda Chemical Co., Ltd. (Yucheng, Dezhou, Shandong Province, China) — A vertically integrated manufacturer with a portfolio that includes cyanuric acid offerings; their integration profile matters for buyers evaluating supply security and cost structure.
- Shandong Mingda Chemical Technology Co., Ltd. (Chiping County, Liaocheng City, Shandong Province, China) — Competes on product availability and cost competitiveness, with a footprint that emphasizes regional logistics and production scale.
Each of these firms is profiled in the full report with operational footprints, go-to-market strategies, capacity posture, and directional intelligence on commercial terms. For buyers and investors, the combination of concentration metrics and supplier profiles creates definable strategic options: secure flexible long-term contracts with incumbent majors, vertically integrate through tolling or JV structures, or target bolt-on acquisitions among well-positioned mid-tier manufacturers.
Practical, actionable content in the PW Consulting report
The full Cyanuric Acid Market study goes beyond market sizing and competitor lists to deliver operationally relevant outputs designed for 2026 decision cycles:
- Dynamic scenario models that let you toggle supply-shock severity, demand elasticity, and price pass-through to quantify NPV and margin outcomes under alternate assumptions.
- Vendor due-diligence templates for procurement teams to standardize RFPs, SLAs and risk clauses specific to cyanuric acid supply.
- An M&A playbook identifying target archetypes, valuation heuristics and integration risks unique to specialty chemical acquisitions in this space.
- Regulatory monitoring maps that translate historical incidents and enforcement actions into forward-looking compliance checklists.
- Commercial intelligence dashboards summarizing price trends, volatility indices and inventory-to-sales staging calibrated for procurement and treasurer use.
Strategic implications and recommended actions for 2026
PW Consulting’s recommendations are targeted at three audiences—producers, buyers (including pool-chemical distributors and municipal/industrial procurement), and private-equity investors—and reflect a balance between growth capture and risk mitigation:
- For producers: Prioritize flexible capacity and dual-sourcing pathways. Consider staged debottlenecking investments and strategic tolling agreements to capture upside without overcommitting capital under near-term uncertainty.
- For buyers: Move from spot-heavy to hybrid contracting (mix of indexed short-term purchases and longer-term capacity bookings). Build inventory buffers sized to modeled disruption scenarios and use our vendor due-diligence templates to harden supply agreements.
- For investors: Target assets with clear feedstock differentiation, proximity to key demand centers, or acquisition targets that can be integrated to create scale in a moderately concentrated market—prioritizing operational resilience over aggressive geographic arbitrage.
Risk management checklist for 2026 execution
Every strategy should be accompanied by a practical risk checklist. Key items we recommend embedding into 2026 plans include:
- Supply contingency playbooks that specify alternate feedstocks, tolling partners and logistics routes.
- Regulatory surveillance routines to detect changes in water-treatment regulation and trade policy that can affect imports/exports.
- Working-capital scenarios that align payment terms with volatility regimes and contractual protections against force majeure events.
- Product-mix optimization to shift flows between product forms (granular, powdered, liquid) according to seasonality and margin dynamics.
What we intentionally withhold — and why
Consistent with PW Consulting’s “trailer” approach, this preview demonstrates our methodological depth and delivers the strategic implications decision-makers need to evaluate. To preserve the commercial integrity of the analysis and to provide maximum value to subscribers, specific sub-segment figures, detailed regional/application splits, and client-ready proprietary tables are exclusive to the full report and its accompanying data workbook. Those assets enable precise negotiations, transaction modeling and operational changes—making them essential for teams executing in 2026.
Next steps
For leaders preparing budgets, negotiating supplier terms, evaluating acquisitions, or stress-testing operations for 2026, our Cyanuric Acid Market study provides the quantitative backbone and the practical tooling required for confident action. Access to the full dataset, supplier profiles with validated URLs, scenario models and execution templates is available through PW Consulting’s report portal. Engage with our team to commission customized variants of the model scoped to your supply chain, geographies, or transaction thesis.
PW Consulting is ready to support decision-makers in turning market insight into executable advantage for 2026 and beyond. Visit the report page to review sample outputs and to arrange a tailored briefing.
For detailed analysis of this topic, please visit the official page: Cyanuric Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Insight: Polymer-Based TIM Market at USD 793.9M in 2025
By pmarketresearch, 2026-07-09
Polymer-Based Thermal Interface Materials (TIM) Market — Strategic Outlook for 2026 Decision‑Makers
Executive summary
As thermal management requirements tighten across electronics, automotive electrification and heavy infrastructure, polymer-based thermal interface materials (TIMs) are at the intersection of materials science, supply‑chain risk and regulatory change. Our PW Consulting study — grounded in audited historicals (2020–2025) and forward-looking scenarios (2026–2032) — shows a market that expanded from USD 688.15 Million in 2020 to USD 793.9 Million in 2025 and is forecast to grow at a modest compound annual growth rate (CAGR) of 2.27% through the 2026–2032 window, reaching roughly USD 932.8 Million by 2032. This measured growth masks considerable complexity: concentrated supplier positions, raw‑material volatility, accelerating regulation on recyclability and emissions, and shifting end‑market dynamics that will define winners and losers in 2026 and beyond.
Polymer Based Thermal Interface Materials (TIM) Market
Why this report matters for 2026 strategic choices
-
Investment and capacity planning: A low-to-moderate aggregate growth rate forces a choice between pursuing share through differentiation or competing on cost. Capex and capacity decisions must be informed by granular demand scenarios rather than headline growth alone.
Polymer Based Thermal Interface Materials (TIM) Market -
Margin protection vs. market share: Stable revenue growth conceals episodic cost shocks (notably in silicone feedstocks). Procurement and product-pricing strategies designed for volatility will be discriminating advantages.
Polymer Based Thermal Interface Materials (TIM) Market -
Regulatory timetables will re‑shape product roadmaps. New EU rules on recyclability and restrictions accelerating adoption of halogen‑free and low‑VOC formulations create both compliance risk and first‑mover opportunities for suppliers who can reformulate quickly.
-
Competitive consolidation and partner plays: The market structure is concentrated — the top three suppliers account for roughly 62.4% of industry revenues and the top five about 74.2% — creating a landscape where strategic partnerships, co‑development agreements and selective M&A can materially change competitive trajectories.
Report contents — practical intelligence we provide
-
Validated market sizing and multi‑scenario forecasts (2026–2032) with demand drivers and downside/upside sensitivity analyses calibrated to component lead times and end‑market cycles.
-
End‑to‑end supply‑chain mapping and cost‑to‑serve models that translate raw‑material price moves into impact on gross margin by product family and customer segment.
-
Regulatory impact matrix and compliance roadmaps for EU and major markets, including product reformulation windows and estimated compliance cost ranges.
-
Competitive benchmarking: capability heatmaps, technology positioning, commercial footprints and an M&A playbook prioritizing targets by strategic fit and integration risk.
-
Commercial playbooks and procurement negotiation templates, designed for OEMs, contract manufacturers and TIM suppliers to optimize contract length, price escalators and pass‑through clauses under volatile raw‑material regimes.
-
Technology and product roadmaps that align performance (thermal resistance, compressibility, outgassing, lifetime) with regulatory constraints and manufacturing cost levers.
Market dynamics shaping 2026 decisions
-
Raw‑material volatility: Early 2026 saw a sharp uptick in silicone prices (approximately +28%) and a roughly +15% increase in silicon metal feedstock costs (Semitech Insights, March 2026). These spikes materially alter cost curves for silicone‑based TIMs and compress legacy margins for producers that lack hedging strategies or flexible formulations.
-
Regulatory acceleration: New EU requirements on recyclability and tighter restrictions on halogen content and VOC emissions are not distant possibilities — they are active drivers forcing reformulation timelines and supply‑chain audits (IDTechEx TIM Report, 2026). Suppliers who front‑load compliance testing will avoid retrofit costs and access preference in automotive and hyperscale data center procurement.
-
Customer expectations: OEMs increasingly bundle thermal management specifications with sustainability KPIs and lifecycle cost models. The purchasing decision is shifting from unit price to validated TCO and circularity credentials.
-
Concentration and bargaining power: High concentration amplifies the commercial leverage of tier‑one suppliers but also increases procurement vulnerability for customers that lack alternative validated sources or reformulation capability.
Competitive landscape — strategic profiles
-
Henkel AG & Co. KGaA (Düsseldorf, Germany — https://www.henkel.com) : With established brands and an integrated portfolio spanning gap fillers, phase‑change materials and elastomeric pads, Henkel’s strength is breadth and customer co‑development. Strategic moves to watch: accelerated automotive validation programs and deeper OEM partnerships emphasizing recyclability.
-
3M Company (St. Paul, MN — https://www.3m.com) : A major presence on thermally conductive pads and tapes, 3M leverages scale, adhesive technology and global distribution. Competitive edge lies in application engineering and rapid prototyping for consumer electronics. Vulnerability: cost exposure to polymer feedstocks if hedging is insufficient.
-
Dow Inc. (Midland, MI — https://www.dow.com) : Supplier of advanced silicone‑based TIMs targeting high‑performance electronics, EVs and data centers. Dow’s strengths are materials innovation and vertical integration potential; expect initiatives around silicone performance enhancement and sustainability claims.
-
Parker Hannifin / Chomerics (Cleveland, OH — https://www.parker.com) : Focused on elastomeric pads and gap fillers for aerospace, defense and industrial segments. Parker’s domain expertise in ruggedized applications and qualification cycles is an entry barrier for new suppliers eyeing specialized markets.
-
Shin‑Etsu Chemical (Tokyo — https://www.shinetsu.co.jp) : High‑purity silicone and polymer compound supplier with strengths in semiconductor and electronics applications. Shin‑Etsu’s capabilities support customers requiring tight material specifications and long lifecycle stability.
-
Momentive Performance Materials (Niskayuna, NY — https://www.momentive.com) : Advanced polymer composites and silicone TIMs, competitive in industrial and electronics thermal management; watch for co‑development with OEMs on data‑center thermal solutions.
-
Wacker Chemie AG (Munich — https://www.wacker.com) : Specialist in silicone polymer chemistries, positioned to capitalize on demand for low‑VOC and high‑performance formulations. Strategic focus likely on automotive EV validations.
-
Elkem ASA (Oslo — https://www.elkem.com) : Supplies silicone and polymer TIMs for electronics and industrial apps; strategic advantages include feedstock integration and European supply footprints.
-
Polymer Science, Inc. (Monticello, IN — https://polymerscience.com) : Niche and custom‑focused, serving medical and specialized electronics markets. Their agility for custom formulations can attract clients seeking rapid validation and small‑batch innovation.
Strategic implications and recommended actions for 2026
-
Immediate procurement playbook: Negotiate flexible contracts with price collars and longer‑term volume commitments where appropriate; use our cost‑to‑serve models to determine acceptability thresholds for passing through raw material surcharges.
-
Formulation and R&D priorities: Fast‑track low‑VOC and halogen‑free reformulations targeted at automotive and data centers; invest in recyclability testing to claim early compliance and secure OEM qualification windows.
-
Supply‑chain resilience: Diversify critical feedstock sources, evaluate regional manufacturing to reduce lead times and consider strategic inventory buffers for key silicone intermediates during peak volatility.
-
Commercial differentiation: Build validated sustainability narratives (verified recyclability, lower lifecycle emissions) into product value propositions — customers are increasingly awarding preference to verified circular solutions.
-
M&A and partnerships: Prioritize targets that close capability gaps (e.g., low‑VOC chemistries, validation labs, regional manufacturing) and offer rapid route‑to‑market in regulated segments.
-
Scenario planning: Use the report’s sensitivity modules to stress‑test P&L under alternate raw‑material, regulatory and demand curves; incorporate these outputs into 2026 budgeting and capital allocation decisions.
How to use the study
-
For strategy teams: Translate scenario outputs into a 24‑month roadmap for product, regulatory and capacity investment.
-
For procurement: Leverage supplier benchmarking and cost models to re‑shape sourcing strategies and renegotiate contracts.
-
For R&D and product management: Use the technology roadmaps and test‑matrix templates to sequence reformulation and validation activities aligned to regulatory deadlines.
-
For corporate development: Apply the M&A playbook and target screen to prioritize inorganic growth that accelerates compliance and performance differentiation.
Next steps (teaser)
PW Consulting’s full report contains the granular datasets, validated segmentations by region, type and application, supplier scorecards and downloadable financial models necessary to operationalize the actions above. This briefing has highlighted the strategic signals and recommended plays for 2026 without disclosing proprietary segment‑level figures — for access to the detailed tables, scenario files and supplier heatmaps, consult the full report on our source webpage or contact our advisory team to schedule a bespoke briefing and model walkthrough.
For detailed analysis of this topic, please visit the official page: Polymer Based Thermal Interface Materials (TIM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com