

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Vinpocetine Market Outlook - USD 307.1M in 2025, 3.8% CAGR to 2032

Vinpocetine Market 2026 Strategic Preview: What Corporate Leaders Must Know
As PW Consulting’s senior industry analyst, I present a focused strategic preview of the Vinpocetine market to guide 2026 decision-making. This briefing synthesizes the macro trajectory, competitive dynamics, regulatory inflection points, and the practical levers companies can pull to protect or grow value. Consider this a high-fidelity trailer: it demonstrates the report’s analytical depth and decision utility while reserving the full, segment-level intelligence for the comprehensive study available through our source portal.
Vinpocetine Market
Market at a glance (macro picture)
Using 2025 as the base year, our market synthesis shows a mature but steadily expanding global Vinpocetine market—estimated at approximately USD 307 million in 2025—with a compound annual growth rate of about 3.8% across the 2026–2032 forecast window. That trajectory takes the market to a materially larger size by the end of the period under a baseline scenario, reflecting a blend of steady pharmaceutical demand, differentiated regulatory regimes across jurisdictions, and constrained but adaptable supply dynamics.
Vinpocetine Market
Historically, the market moved from the mid‑2020s with stable year-on-year gains through 2025, driven by sustained pharmaceutical applications and continued use in some over‑the‑counter channels. The moderate CAGR we forecast is consistent with a product in the late growth to early maturity phase—one where incremental gains are won through regulatory positioning, quality differentiation, and targeted clinical evidence rather than broad-based demand expansion.
Vinpocetine Market
Why this report matters for 2026 corporate decisions
- Regulatory posture will determine commercial access: Vinpocetine’s regulatory classification varies materially by market. In several major markets it is treated as a pharmaceutical ingredient; in others it remains available in supplement channels but under active scrutiny. That regulatory variability translates into distinct commercial and compliance strategies—and creates winner-take-most outcomes for firms that secure robust dossier support and proactive engagement with regulators.
- Supply concentration creates strategic exposure: The market is concentrated among a handful of high‑quality producers and distributors with established GMP/ICH credentials. Concentration amplifies both pricing stability and supply risk: a single plant disruption, quality event, or export restriction can meaningfully affect global access and near‑term pricing dynamics.
- Clinical evidence is the gating item for long‑term value: Across the portfolio of end uses, a persistent shortfall in large, modern clinical datasets constrains label expansion and premium positioning. Firms that invest in targeted clinical programs or real‑world evidence generation can unlock reclassification opportunities and premium pricing in regulated markets.
- Mature demand favors strategic differentiation over volume plays: Given the market’s moderate growth profile, margin expansion strategies—quality credentials, dossier completeness (DMF/ASMF), and supply security—outperform low‑cost volume strategies except in clear niche geographies where scale is decisive.
Report deliverables that enable action in 2026
Our full study goes beyond descriptive analysis. For executives, business-development teams, and investors preparing 2026 plans, the report includes:
- Scenario‑based forecasts with sensitivity matrices for regulatory shocks, raw‑material constraints, and accelerated clinical outcomes;
- Supplier and distributor scorecards covering manufacturing credentials, dossier coverage, inspection histories, and trade routes;
- Regulatory playbooks for priority markets: required filings, pharmacovigilance expectations, and timelines to market under alternative classifications;
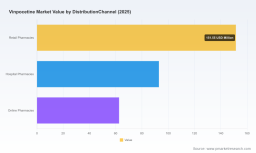
- Go‑to‑market playbooks and commercial models by channel (pharmaceutical, hospital, retail/OTC, and online), with practical checklists for market entry and margin management;
- Risk heatmaps and mitigation guidance covering botanical raw-material exposure, single‑site manufacturing risks, and export/regulatory compliance risks;
- M&A and partnership thesis templates: acquisition filters, valuation sensitivities, and integration checklists for API producers, specialty distributors, and clinical research partners.
Competitive landscape: what to watch
The supplier base mixes long‑established European specialists, large Indian manufacturers with export‑oriented compliance footprints, and Chinese suppliers with broad global distribution. Key industry players we profile in the report include:
- Covex S.A. (Spain) — a veteran manufacturer and supplier with dedicated synthesis facilities and longstanding compliance to ICH/FDA/NCF standards. Their legacy specialization in vinca‑derived APIs positions them as a reference for pharmaceutical‑grade Vinpocetine.
- Alchem International (India) — GMP‑certified, USFDA/EU‑inspected manufacturer and exporter that emphasizes dossier completeness and regulatory support (ASMF/DMF coverage), which is decisive for customers targeting regulated markets.
- Sinoway Industrial (China) — a GMP supplier with deep CoA documentation practices and broad distribution networks, important for buyers balancing cost and speed to market.
- AXXO GmbH (Germany) — a distributor with GMP/GDP and USDMF credentials; plays a crucial role in bridging supply and regulatory support in Europe and other regulated markets.
- Zeon Pharma Industries and Astitva Chemicals (India) — additional GMP producers with export experience; collectively they provide capacity and competitive tension in price and lead‑times.
Collectively, the leading suppliers establish high barriers for entrants that cannot demonstrate consistent GMP compliance, dossier readiness, and reliable logistics. Our competitive benchmarking quantifies these barriers and ranks suppliers on a multidimensional scorecard of quality, regulatory readiness, capacity, and commercial reliability.
Regulatory and raw‑material dynamics: critical decision levers
- Regulatory divergence: Regulators in some jurisdictions classify Vinpocetine strictly as a pharmaceutical active, while others allow its marketing in dietary supplements under varying constraints. The FDA’s ongoing advisories—particularly safety communications relevant to specific populations—raise the risk of reclassification or further label restrictions in the U.S., with downstream effects on demand, labeling, and claims.
- Raw‑material architecture: Vinpocetine is a semi‑synthetic derivative of vincamine, which ties API production to botanical feedstock and specialized synthesis routes. That hybrid upstream model limits rapid capacity expansion and raises the value of dual‑sourcing, backward integration, and validated second‑source suppliers.
- Quality and dossier completeness: Access to high‑value regulated markets is gated by DMFs/ASMFs, inspection history, and traceable CoA chains. Companies lacking dossier or inspection readiness face a multi‑quarter delay to enter regulated channels.
Strategic recommendations for 2026 planning
- Prioritize regulatory hedging: Allocate resources to strengthen dossier libraries, proactive pharmacovigilance, and engagement with regulatory authorities in your top three markets. Prepare submission timelines for DMFs/ASMFs now—delays in 2026 can translate into lost shelf space and deferred revenue.
- Build supply resilience: Implement dual‑sourcing or toll‑manufacturing relationships with suppliers who demonstrate GMP/ICH credentials. Consider limited backward integration or long‑term purchase agreements to secure feedstock and intermediate supply.
- Invest selectively in evidence: Target a focused clinical or real‑world evidence program that addresses the largest regulatory or payer objections in priority markets. Even a small, high‑quality trial or observational program can shift positioning from marginal supplement to accepted therapeutic adjunct in regulated formularies.
- Use M&A and partnerships tactically: Given market concentration among a few high‑quality producers, acquisitions or minority investments in compliant API players can be the most effective way to secure long‑term supply and dossier control.
- Differentiate commercially: For companies competing in mature channels, create differentiated offerings through quality certificates, branded formulations, and bundled regulatory support for downstream customers.
- Scenario‑proof your plan: Embed trigger points in budgets tied to regulatory actions (e.g., restrictive advisories) and to supplier disruptions. That will allow rapid reallocation between defense (safety communications response) and offense (market expansion when regulatory clarity emerges).
Scenario framing: three outcomes to model now
- Baseline (most likely): Continued moderate growth aligned with the 3.8% CAGR as regulated markets absorb current supply while supplement channels stabilize under tighter oversight.
- Downside (regulatory tightening): If major markets accelerate reclassification or tighten claims enforcement, expect demand contraction in OTC channels with a short‑term price shock and rebalancing toward pharmaceutical procurement routes.
- Upside (evidence‑driven expansion): Targeted, credible clinical evidence and coordinated regulatory submissions could expand reimbursed indications and create premium opportunities in several regulated markets—lifting growth above baseline assumptions.
Concluding perspective and next steps
For 2026 planning, Vinpocetine is a classic strategic product: moderate market growth and high commercial variance driven by regulatory outcomes, supply concentration, and the presence (or absence) of modern clinical evidence. Executives who act early—shoring up supply, investing in dossier and evidence, and mapping contingent responses to regulatory moves—can convert a steady market into a source of durable margin and market share.
PW Consulting’s full report provides the granular segmentation, regional and channel breakouts, supplier scorecards, and downloadable scenario models that translate the strategic directions above into executable 90‑ and 180‑day plans. To access the complete intelligence package, including interactive spreadsheets and vendor dossiers, please visit our report page.
For detailed analysis of this topic, please visit the official page: Vinpocetine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com