

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Manual Cleaning Products Market: 4.9% CAGR to USD 197.3M by 2032

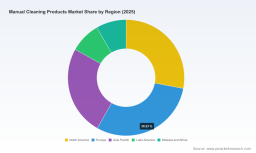
Manual Cleaning Products Market — Strategic Outlook for 2026 Decision‑Makers
As companies plan investments and portfolio shifts for 2026, the Manual Cleaning Products Market presents a blend of steady expansion, margin pressure, and technology-driven disruption. Our PW Consulting market study (base year 2025, historical window 2020–2025, forecast 2026–2032) models this market at USD 141.7 million in 2025, up from roughly USD 110 million in 2020, and projects growth to roughly USD 197.3 million by 2032 at a compound annual growth rate (CAGR) of 4.9%. This paper distills the report’s strategic value for executives, procurement leads, BD teams, and corporate development groups in 2026 — showing where to act quickly, where to prepare, and where to wait for clearer signals.
Manual Cleaning Products Market
Why this research matters for 2026 decisions
- Investment horizon clarity: A 4.9% CAGR across 2026–2032 signals a market delivering stable top‑line expansion but not runaway growth — optimal for targeted capex and selective M&A rather than broad, high‑beta expansion programs.
- Profitability under pressure: Raw material volatility and rising frontline labor costs compress operating margins in manual cleaning operations, making cost containment, product premiumization, and service/consumables monetization immediate priorities.
- Technology and channel inflection: Hybridization of manual and automated cleaning (robotic integration, modular scrubber attachments) creates opportunities to reposition from one‑time equipment sales to recurring revenue models — particularly relevant for companies considering platform plays or subscription services.
- Regulatory and safety risk management: New and tightening rules (e.g., supplier qualification for raw ingredients, and safety advisories on equipment) require faster product compliance cycles and stronger supplier governance to avoid costly recalls or market access delays.
What the full report delivers — practical, transaction‑ready outputs
- Actionable executive summary with investment thesis and 12‑, 24‑, and 36‑month decision matrices.
- Proprietary market sizing and forecasting model (base 2025; historical 2020–2025; forecast 2026–2032) delivered in editable format, with scenario toggles for demand shocks, raw material price swings, and labor cost scenarios.
- Go‑to‑market playbooks for three strategic pathways: premium product leadership, cost‑efficient commodity supply, and recurring‑revenue services (consumables & maintenance contracts).
- Competitive landscape dossiers and strategic profiles of leading and disruptive players — including product roadmaps, distribution footprints, and partnership strategies.
- Supply chain risk register tied to raw material indices, supplier concentration maps, and mitigation options (dual sourcing, vertical integration levers, hedging strategies).
- Regulatory impact assessment and compliance checklist for European and North American market entry, plus recommended testing protocols for chemical inputs and equipment safety.
- M&A target screening criteria, valuation benchmarks, and synergy realization playbooks specific to manual cleaning product businesses and adjacent robotics/equipment firms.
- Appendices: interview transcripts with industry buyers, trade‑show intelligence harvest (Interclean 2026 observations), and sensitivity analysis supporting price and volume elasticities.
Note: this article is a strategic preview. Detailed sub‑segment tables, regional splits, and line‑item revenue figures are intentionally omitted here and are available in the full report.
Manual Cleaning Products Market
Data‑driven macro insights you can act on now
- Steady base‑market growth enables disciplined reinvestment. The market’s trajectory — from the early‑2020 baseline to the 2025 reference point and on to 2032 — supports disciplined investment into product upgrades, selective automation, and channel expansion while maintaining ROI thresholds that typical private and strategic buyers expect.
- Concentration and competitive tension. Market concentration metrics indicate a mid‑range consolidation state: the top three players do not dominate the market, and the top five capture less than half the market — a structure that favors both innovative niche propositions and bolt‑on acquisitions for growth accelerants.
- Cost and regulatory headwinds are real and actionable. Volatility in plastics and specialty polymers used for packaging and tool components directly pressures COGS, while tightened EU supplier qualification and chemical testing raise time‑to‑market for reformulations and new SKUs. These forces make supplier contracts, material substitution strategies, and compliance investments near‑term priorities.
- Labour economics push automation and service models. Frontline wages and operational overhead in many developed markets are high enough to justify upfront investments in semi‑automated or hybrid cleaning solutions when TCO and uptime benefits exceed hurdle rates.
- Trade shows and product launches are signposts for strategy. The 2026 Interclean cycle highlighted aggressive product rollouts and hybridization: leading robotics firms showcased next‑generation autonomous sweepers and heavy‑duty scrubbers, while several OEMs emphasized compact, battery‑powered manual scrubbers and modular attachments — signals that partners and competitors alike are pivoting toward integrated cleaning ecosystems.
Competitive landscape — strategic positioning of core players
The research includes focused profiles of the market’s most influential and disruptive names. Below is a high‑level synthesis of strategic posture and implications (detailed profiles are in the report):
Manual Cleaning Products Market
- FOAMit (US): Niche commercial entry‑point solutions — an example of vertical specialization around a singular hygiene function. Such focused plays can be attractive acquisition targets for equipment integrators seeking differentiated access points into facilities management contracts.
- Tornado Vacuums (Italy): Strong OEM pedigree in cylindrical scrubbers and compact battery manual scrubbers. Their recent product updates indicate an emphasis on small‑footprint applications and modularity — a defensive response to demand for flexible, low‑capex cleaning options.
- IPC Worldwide (US): Broad professional toolset provider — positioned to bundle manual accessories with larger systems, enabling cross‑sell into long‑standing service contracts.
- KUER & Chancee (China): Aggressive trade‑show presence and product breadth. These manufacturers are amplifying exports and competing on value and rapid development cycles; they are logical partners for strategic rollouts in price‑sensitive markets or OEM white‑label programs.
- Gausium (China): Robotics leader driving hybrid models — their 2026 Interclean launches of advanced autonomous scrubbers show the clear direction toward automating routine manual tasks and monetizing autonomy through software and services.
- Multi‑Clean & Seventh Generation (US): One focuses on commercial chemicals and floor care consumables; the other on biobased, eco formulations for home care. Together they illustrate the bifurcation in demand: institutional buyers seek performance and serviceability, while a growing consumer and retail channel demands sustainability claims validated by testing and supply transparency.
Recent market activity with strategic implications
- Gausium’s high‑profile Interclean 2026 showcase (including a Beetle 2.0 robotic sweeper and heavy‑duty autonomous scrubber) underlines the acceleration of autonomy investment and the need for incumbents to evaluate integration or partnership strategies.
- KUER and Chancee’s trade‑show focus on walk‑behind and high‑performance scrubbers signals intensifying competition from Chinese OEMs for global commercial contracts.
- Tornado’s compact cylindrical scrubber product refresh demonstrates continued market demand for efficient, battery‑powered manual solutions that reduce labor burden while preserving mobility and flexibility.
Priority strategic actions for 2026 (what PW Consulting would recommend)
- Immediate (0–6 months): Run a supplier risk audit tied to plastics and specialty polymers; renegotiate supply buffers and build price‑index‑linked contracts. Fast‑track product safety audits to meet latest equipment safety advisories.
- Near‑term (6–18 months): Pilot hybrid solutions that pair manual equipment with low‑cost automation or telematics to prove TCO improvements; introduce service bundles (maintenance, consumables) to stabilize recurring revenue.
- Medium term (18–36 months): Consider tuck‑ins in robotics or consumables depending on strategic intent: robotics for market leaders seeking margin expansion and defensibility; consumables for players focused on stable, high‑margin repeat business.
- Commercial levers: Move to value‑based pricing in professional channels, expand private‑label partnerships in price‑sensitive markets, and deploy digital channels for direct SMB engagement.
Methodology and confidence indicators
The full study uses a blended methodology: bottom‑up revenue aggregation from equipment, consumable, and service channels; top‑down triangulation against macro indicators; primary interviews with OEMs, distributors, and large end users; and trade‑show intelligence gathered at Interclean 2026 and other industry events. The model includes three scenario tracks (base, upside, downside) and sensitivity tests for key variables: raw material price index, frontline labor cost shifts, and adoption velocity of semi‑automated solutions. Revenue units are expressed in USD Million with 2025 as the base year.
How to use this preview
This executive preview is designed to be a decision‑oriented guide. Use it to align leadership on strategic priorities for 2026, inform procurement negotiations, frame M&A screening criteria, and guide product roadmap debates. For transaction diligence, detailed sub‑segment figures, regional revenue splits, company‑level sales estimates, and our full financial model are provided in the complete PW Consulting report. Those datasets and granular breakouts are intentionally reserved to preserve the actionable advantage for report purchasers.
To obtain the full dataset, scenario models, and company dossiers — including the granular segmentation that underpins the recommendations above — please consult the full Manual Cleaning Products Market report on the PW Consulting portal or contact our industry practice for a briefing and license options.
For detailed analysis of this topic, please visit the official page: Manual Cleaning Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com