

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Quartz Glass Market to Reach USD 2,216 Million by 2032 at 6.8% CAGR — PW Consulting Insight

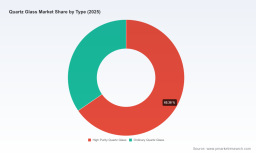
Quartz Glass Market — 2026 Strategic Primer
Executive snapshot
PW Consulting’s Quartz Glass Market study is designed for executives who must make capital, procurement and M&A decisions in 2026 with limited runway. The global quartz glass market stood at USD 1.42 billion in our 2025 base year and, under our central case, is projected to grow at a 6.8% CAGR through a seven-year forecast window (2026–2032), reaching approximately USD 2.22 billion by 2032. That steady, above-market industrial growth is being driven by a confluence of semiconductor scaling (including EUV and photomask demand), the continued rollout of power electronics for EVs and renewables, and incremental growth in optics, lighting and laboratory segments.
Quartz Glass Market
This primer highlights the report’s strategic value for decisions you must finalize in 2026: where to allocate capex, which suppliers to lock, how to hedge feedstock exposure, when to accelerate vertical integration, and which competitive moves will materially change your position over the next 12–24 months. The full report contains the granular segmentation, supplier scorecards and interactive financial models that underpin the recommendations summarized below; this article purposely illustrates the insights while omitting the detailed segment tables and raw vendor scores to guide you to the full deliverable.
Quartz Glass Market
Why this study matters for 2026 decisions
-
Timing is critical. Mid-decade demand surges for EUV-quality and large-format synthetic substrates have created pockets of lead-time risk for high-purity fused silica and precision components. Capital commitments made in 2026 will determine supply balances for the early 2030s.
Quartz Glass Market -
Complex quality differentiation. Not all quartz is equal: purity, defect density, dimensional tolerances and thermal performance drive customer value in semiconductor and photomask applications. Suppliers that can demonstrate EUV-grade consistency and advanced ovality or flatness tolerances capture premium contracts.
-
Supply-side signal: capacity investments and supplier awards. Recent announcements—in particular large-scale European capacity expansions and supplier recognitions from major OEMs—signal a market reshuffle where capacity and certified OEM relationships will be primary competitive moats.
-
Input-cost dynamics are manageable but shifting. North American feedstock showed mild downward movement in Q1 2026, while broader silicon dioxide indices show a slight upward trajectory into 2026 after inventory-driven declines in 2025. Procurement strategies should balance short-term price relief against an anticipated, gentle recovery.
-
Regulatory continuity lowers near-term trade risk. Quartz glass is listed under HS 70200010 and, as of the latest reviews, has not been subject to specific new import/export controls or environmental surcharges—removing one layer of policy uncertainty for cross-border sourcing and capacity allocation.
What the full report delivers — practical content for direct action
- Top-line market sizing and historical trend analysis (2020–2025) and a transparent forecast engine for 2026–2032 with scenario toggles for low/base/high demand outcomes.
- Demand-driver deep dives covering semiconductor process roadmaps (EUV, advanced nodes), photovoltaic manufacturing cycles, EV power electronics, optics and specialty lamp markets.
- Supply-chain mapping: feedstock sources, synthetic quartz routes, conversion bottlenecks, and a prioritized list of long‑lead, single‑source components.
- Supplier scorecards and vendor risk matrices assessing quality, capacity, geographic footprint, certification status and customer concentration.
- CapEx and margin sensitivity models allowing finance teams to stress-test expansions under differing price and demand curves.
- Scenario playbooks: contract procurement (spot vs. long-term), lean vs. resilience strategies, and M&A and JV frameworks tailored for OEMs, fabs, and component houses.
- Regulatory & raw-material appendix summarizing tariff status, feedstock price indices and environmental compliance considerations.
Note: this primer intentionally omits the granular regional and application splits and the detailed supplier scores contained in the full report. Those tables are often the actionable intelligence buyers and investors need to finalize negotiations and are therefore delivered in the paid research package.
Competitive landscape — strategic read of core players
The quartz glass supplier ecosystem blends legacy materials specialists, regional high-volume producers and precision component fabricators. No single firm dominates the market; leadership is built on a combination of purity capability, OEM certifications, scale of synthetic quartz production and proximity to demand hubs.
-
Tosoh Quartz Corporation (Tokyo) — A heritage materials player pivoting aggressively toward silica glass to capture demand from AI hardware, power electronics and RF systems. Recently recognized by a major OEM, Tosoh’s strategic alignment with chipmakers and broad product portfolio make it a prime partner for long-term supply agreements. Key decision factor: Tosoh’s ability to convert strategic intent into repeatable, certified EUV-grade deliveries.
-
Heraeus Quarzglas (Hanau) — Investing materially in Europe with new flame hydrolysis furnaces and expanded EUV-grade ingot capacity. Heraeus is also deploying AI-enabled quality control for defect detection—an advantage where microscopic defects carry outsized value. Key decision factor: validation timelines for the new capacity and consistency of EUV-grade output.
-
Technical Glass Products & Swift Glass (USA) — These fabricators specialize in finished components, labware and application-specific products with strengths in short-run customization and thermal/mechanical performance. They are natural partners for customers seeking agile supply with technical co-development.
-
Hubei Feilihua (China) — A large-volume manufacturer focused on semiconductor-grade fused quartz with strong cost-positioning. Their scale is a double-edged sword: attractive for volume sourcing but potentially constrained for ultra-high-purity, large-format substrates where specialized processes are required.
-
Specialist precision houses (QSIL, Raesch, Maruwa, MGS, Sintrex) — These firms excel at precision drawing, finishing and custom components. For OEMs requiring bespoke tube, rod, plate or machined parts, these suppliers are often decisive enablers of product differentiation.
Recent industry developments change the competitive calculus: European capacity additions shift some long-term bargaining power; product-line enhancements (improved ovality, tighter flatness tolerances) create new premium tiers; and supplier awards from marquee OEMs accelerate consolidation in the supply chains for high-end, high-purity segments.
Strategic priorities and playbook for 2026
-
Prioritize contract certifications for mission-critical grades. If your product roadmap depends on EUV-grade or large-format photomask substrates, negotiate multi-year supply-and-performance agreements with penalty-and-reward clauses tied to defect rates and delivery windows.
-
Hedge feedstock tactically. Take advantage of short-term relief in certain regions while establishing contingent supply contracts to protect against the modest rebound in silicon dioxide indices forecast for 2026.
-
Invest in upstream assurance. For OEMs and fabs, consider minority equity or joint-venture stakes with high-purity producers to secure allocation without full capex exposure.
-
Target precision fabricators for bolt-on M&A. Small-to-mid market precision component makers can be integrated to shorten lead times and protect IP in specialized optical or thermal components.
-
Implement AI-enabled QC in your incoming-inspection protocols. Suppliers deploying these tools have a demonstrable edge in detecting subsurface defects and improving yield—require transparency on defect-detection methodology as part of supplier selection.
-
Build flexible sourcing geographies. Even though tariffs and controls are not a near-term constraint, geographic diversification reduces concentration risk from single-region outages or capacity bottlenecks.
-
Embed sustainability and recycling clauses into procurement. Recycled quartz and closed-loop programs are emerging as differentiators for capital projects and can reduce long-term feedstock exposure.
Decision triggers and metrics to monitor in 2026
- Feedstock price indices (especially regional silicon dioxide trends).
- Vendor capacity announcements and furnace installations for EUV-grade and large-format ingots.
- Lead times for critical components (ingots, large plates, precision tubes) and trend lines versus booked backlog.
- Defect and yield metrics from pilot runs—especially for EUV-grade and photomask substrates.
- Customer backlog at major buyers in semiconductor and photovoltaic value chains.
How to use the full PW Consulting deliverable
If you are setting procurement budgets, designing a two‑year capex cadence or evaluating strategic acquisitions in 2026, the full Quartz Glass Market report provides the models and scored supplier universe to convert these strategic themes into executable decisions. The paid report includes downloadable scenario models you can plug into your board materials, a procurement negotiation playbook with contract language templates, and a prioritized M&A watchlist aligned to different corporate strategies (volume-scaling, premium-differentiation, or regional resilience).
We have intentionally sketched the strategic landscape and recommendations here while withholding the granular regional and application splits, per-supplier numerical scores and the full financial models. That granularity is the difference between a good negotiation and a market-winning agreement, and it is available in the full report package where you can access the underlying data, sensitivity tables and supplier scorecards.
For guidance tailored to your specific position—buyer, component manufacturer, or investor—contact PW Consulting’s Quartz Glass practice to arrange a workshop where we apply the model to your balance sheet, contract portfolio and technology roadmap.
For detailed analysis of this topic, please visit the official page: Quartz Glass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com