

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Bagged Salt Market to Reach USD 148.2 Million by 2032

Bagged Salt Market — 2026 Strategic Primer
Executive summary
As companies finalize budgets and strategic plans for 2026, a calibrated understanding of the bagged salt market is essential. PW Consulting’s latest market intelligence positions the industry on a steady-growth trajectory: using 2025 as the base year, the global bagged salt market reached a multi‑million USD scale and exhibits a baseline compound annual growth rate (CAGR) of roughly 4.0% over the 2026–2032 forecast horizon. Our historical view (2020–2025) shows a resilient recovery from cyclical pressures with demand drivers that differ materially by end‑use and channel.
Bagged Salt Market
This briefing is designed as a high‑signal trailer: it synthesizes the implications of the full study — markets, players, regulatory dynamics, and actionable playbooks — while intentionally withholding the report’s granular segment numbers so you will consult the source for detailed breakdowns and downloadable models.
Bagged Salt Market
Market trajectory and key inflection points to watch in 2026
-
Continuing growth with structural nuance — The market is expected to expand from its 2025 base into the forecast period, reflecting steady demand across de‑icing, industrial feedstock, and specialty commercial uses. Aggregate growth is moderate (CAGR ~4.0%), but the underlying drivers vary by seasonality, geography and application.
Bagged Salt Market -
Seasonal volatility remains a strategic factor — Weather variability and winter severity drive short‑term procurement cycles and working capital swings for manufacturers and resellers. Inventory management and flexible logistics are high‑return levers.
-
Input and price signals — Broad industry reporting shows salt production and distribution remain substantial in scale, with stable average unit values for bulk and packaged products in recent public data. Expect pricing sensitivity in tight winter seasons and in regions with concentrated supply points.
-
Regulatory and ESG inflection — Environmental requirements for salt handling, runoff, and packaging are intensifying. Compliance and demonstrable mitigation measures will shift procurement preferences toward suppliers that can document lower environmental impact and reliable end‑to‑end stewardship.
Why this matters for 2026 decision‑makers
-
Procurement and supply‑chain resilience: With the market's moderate growth profile, incremental supply‑side shocks (plant maintenance, logistic constraints, labor issues) can create outsized price and availability impacts during peak demand windows. Short‑term tactical steps — longer lead contracts for key seasons, inventory hedging strategies, and multi‑supplier sourcing — must be balanced against working capital objectives.
-
Portfolio and channel strategy: Companies with exposure to multiple end‑uses should reassess portfolio mix given differing margins and growth outlooks. Specialty products and value‑added blends are increasingly important to capture premium channels (commercial snow‑management, specialty industrial customers), and investment here can outpace growth in commoditized segments.
-
Capital allocation and M&A: The industry’s structure favors players with scale in production, packaging and distribution. For 2026, inorganic growth remains a pragmatic pathway to secure geographic fill‑ins, gain packaging capacity, or acquire specialty formulations. Firms should prioritize targets that offer immediate synergies in distribution or seasonal storage.
-
Pricing architecture and customer contracts: Dynamic pricing clauses tied to seasonal indices, index floors for critical raw inputs, and capacity reservation fees are effective: they preserve margin during peak demand while keeping customers committed. Revisit contracting language to reflect volatility observed in recent seasons and to de‑risk both suppliers and buyers.
-
ESG and stakeholder value: Visibility into sourcing footprints, handling of brine and runoff, and packaging recyclability are no longer table stakes — they are commercial differentiators. Buyers increasingly incorporate supplier ESG performance into vendor selection; producers must operationalize traceability and compliance to protect market access.
Competitive landscape — strategic profiles and implications
The bagged salt market is characterized by a small set of well‑established producers and regional specialists that together determine supply flexibility and price dynamics. Below we profile core players and pragmatic strategic implications for competitors, procurement teams and potential investors.
-
American Rock Salt Company (Mt. Morris, NY) — Strength: high underground‑mine throughput and established logistics for de‑icing. Strategic implication: its capacity and operational scale make it a natural partner for large municipal and highway contracts. For buyers, lock‑in options or multi‑year agreements can secure access during peak seasons. For competitors, incremental efficiency improvements in packaging or last‑mile logistics are required to counter its scale advantage.
-
Compass Minerals (Overland Park, KS) — Strength: diversified feedstock (rock and evaporated salts) and integrated distribution networks from major mines. Strategic implication: Compass’s recent fiscal disclosures underscore disciplined capacity utilization. Firms evaluating partnership or supplier rationalization should consider the benefits of stable year‑round supply versus localized cost advantages from smaller suppliers.
-
Morton Salt (Chicago, IL) — Strength: brand strength across consumer and industrial channels, broad product slate including specialty and food‑grade salts. Strategic implication: Morton's channel reach offers premium pricing opportunities in retail and specialty segments. Competitors should consider channel specialization or private‑label strategies to protect margin erosion in retail corridors.
-
Gunther Salt (St. Louis, MO) — Strength: regional distribution and product variety serving commercial, institutional and municipal customers. Strategic implication: regional players retain renewal advantages through local relationships and rapid replenishment capabilities; national players should evaluate bolt‑on acquisitions to close regional service gaps.
-
K+S Aktiengesellschaft (Hannover, Germany) — Strength: global portfolio and cross‑border supply capabilities to serve industrial and food markets. Strategic implication: multinational firms and industrial buyers value K+S for supply security and compliance pedigree; domestic players should pursue operational differentiation or niche product lines to defend against imports in regions with cross‑border exposure.
Recent public developments reinforce these strategic imperatives: American Rock Salt’s 2026 operational communications emphasize strong production continuity, and Compass Minerals’ latest fiscal update highlights capacity utilization trends that are shaping supply availability for the 2026 planning cycle.
Risks, regulation and industry “noise” to monitor
-
Regulatory environment: Recent industry data confirm the chemical sector captures a large share of salt demand and that production and usage volumes remain significant nationally. Regulators are sharpening focus on brine management, stormwater controls and road salt impacts on freshwater — anticipate stricter local ordinances and procurement specifications in the near term.
-
Supply concentration and geographic exposure: A limited number of mines and plants supply substantial portions of the market. This concentration creates vulnerability to regional outages and maintenance cycles; scenario planning should quantify the impacts of short‑term production disruptions on procurement costs and service levels.
-
Market noise vs. signal: Not every weather event or short‑term price spike signals a structural shift; our scenario suite differentiates transient shocks from persistent trend changes. Use those scenarios to stress‑test contract language and inventory strategies.
-
Stable unit values reporting: Publicly available industry analyses indicate relative stability in average unit values across bulk and packaged salt in recent reporting — a useful baseline when modeling price exposure.
What PW Consulting’s full report delivers — practical contents
The full PW Consulting Bagged Salt Market study is designed for immediate operational use by procurement teams, commercial leaders, strategic planners and M&A professionals. Highlights include:
- Proprietary forecast model (2026–2032) with scenario toggles and downloadable datasets (USD, Million).
- Demand driver decomposition by end‑use and channel (methodology and elasticities included).
- Supply‑side mapping and a risk heatmap of production nodes, logistics corridors and seasonal bottlenecks (interactive GIS layer included in the report package).
- Supplier scorecards and playbooks for procurement (performance, capacity, ESG readiness — anonymized benchmarking included).
- Commercial strategy toolkits: pricing clauses templates, channel segmentation playbooks, and packaging/brand premiuming strategies.
- M&A and investment screening framework: target prioritization and quick‑win integration checklists tailored to bagged salt economics.
- Regulatory compliance checklist and mitigation playbook for brine/runoff, storage and transport.
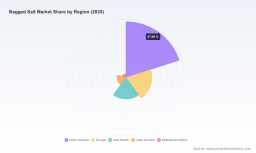
Note: to preserve the strategic value of the report and align with client confidentiality, this primer omits the granular regional and application splits and the full numeric segmentation tables included in the paid study. Those details, along with the interactive model, are available on the report page.
Immediate actions for Q1 2026
- Update 2026 procurement strategy using a 4.0% CAGR baseline and run upside/downside scenarios for winter severity.
- Negotiate capacity reservation or indexed pricing for peak seasons; include force majeure and allocation clauses informed by our scenario outputs.
- Inventory optimization: blend safety stock with seasonal forward buys to balance cash and availability risks.
- ESG and compliance: initiate supplier audits for runoff and storage controls; prioritize partners with demonstrable mitigation programs.
- Shortlist M&A or partnering targets using our supplier scorecard to close geographic or channel gaps.
Conclusion & next step
The bagged salt market for 2026 is not a single homogeneous opportunity — it is a portfolio of interrelated plays across seasonality, geography and end‑use. PW Consulting’s full report equips leaders with data, scenarios and executable playbooks to convert the market’s moderate growth and stability into predictable commercial advantage. For access to the complete dataset, interactive forecast model, and the detailed segment intelligence omitted here, please visit the full report page or contact PW Consulting for a briefing and model walkthrough.
For detailed analysis of this topic, please visit the official page: Bagged Salt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com