

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Rice Husk Ash Market to Reach USD 343.0 Million by 2032 at 5.0% CAGR

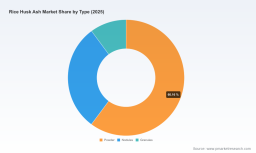
Rice Husk Ash Market: Strategic Imperatives for 2026 Decision-Making
As businesses plan capital allocation, sourcing strategies, and product roadmaps for 2026, Rice Husk Ash (RHA) is emerging from the margins of industrial by‑products into a strategically important material class. PW Consulting’s latest market study — anchored on a 2025 base year and a seven‑year forecast horizon to 2032 — positions RHA within a predictable growth arc that is both investible and operationally complex. The market expanded from a roughly USD 192 million footprint in 2020 to about USD 244 million in 2025 and is projected to reach approximately USD 343 million by 2032, reflecting a compound annual growth rate of 5.0% over the forecast period. These headline numbers are the entry point; the real value for executives comes from understanding where price, policy, supply chain and product differentiation converge to create windows of opportunity in 2026 and beyond.
Rice Husk Ash Market
Why RHA matters to corporate strategy this year
-
Decarbonization-linked demand: RHA’s role as a supplementary cementitious material (SCM) and as a source of biogenic silica aligns directly with corporate decarbonization strategies and buyer mandates in green construction and metallurgy. Regulatory levers such as EU carbon pricing and emissions trading are intensifying the commercial incentive to substitute clinker and other carbon‑intensive inputs with certified biogenic materials.
Rice Husk Ash Market -
Value capture through processing: Not all RHA is equal. Controlled combustion and post‑combustion beneficiation determine amorphous silica content, particle size distribution, and pozzolanic performance. Producers that invest in quality control and high‑value downstream processing can convert a low‑margin by‑product into specialty silica grades commanding premium placement in refractories, specialty ceramics and high‑performance concrete formulations.
Rice Husk Ash Market -
Supply chain and geopolitical risk: Export controls and tariffs on agricultural waste from key Asian producing nations, combined with rising transport surcharges for certified bulk shipments, are reshaping trade flows and raising landed costs in import‑reliant markets. For multinational off‑takers, this elevates the importance of near‑sourcing, strategic inventory positioning, and contractual protections in feedstock supply agreements.
-
Consolidation and concentration: The market exhibits material concentration among a small set of integrators and specialists. Our competitive concentration metrics indicate meaningful market share controlled by the top three and top five suppliers, creating both negotiating leverage for dominant players and white‑space for challengers with differentiated technical capabilities or captive feedstock.
What the PW Consulting report delivers — operational, boardroom‑ready content
-
Quantified market sizing and forecasting (historical 2020–2025, forecast 2026–2032) including topline scenarios sensitive to feedstock availability, transportation cost curves and regulatory tightening.
-
Supply chain mapping and raw‑material economics: granular models that translate rice husk availability and combustion protocols into usable RHA product buckets and delivered cost ranges (our primary research captures current ex‑works price bands and freight dynamics).
-
Regulatory and sustainability matrix: a decision‑grade assessment of compliance requirements, certification pathways for pozzolanic claims, and emissions incentives across major trading jurisdictions.
-
Competitive benchmarking and supplier scorecards: technical capability, capacity, vertical integration, and go‑to‑market models for incumbent and emerging players, together with an M&A and partnership thesis.
-
Commercial playbooks: tender and contract templates, offtake structures, pricing indexation approaches and procurement negotiation levers designed for buyers and for new‑entrant producers.
-
Standalone financial models and project screeners: plant economics for RHA processing, silica extraction units and modular combustion installations, with sensitivity to energy costs and carbon pricing.
-
Case studies and field verification: examples of successful integration of RHA into cement blends, refractory formulations and silica extraction operations, plus interview excerpts from buyers, mill operators and technology suppliers.
Competitive landscape: profiles and strategic implications
Market dynamics are being shaped by a mix of vertically integrated agricultural groups, specialized chemicals firms, regional mill operators and niche refractory distributors. Several archetypes are visible:
-
Integrated mill operators with captive RHA streams — these players monetize the by‑product through downstream supply into cement, construction and local industrial buyers. Their advantages are feedstock security and logistics optimization that lower delivered cost and supply risk.
-
Specialist processors and materials companies — firms focusing on producing high‑amorphous‑silica RHA or converting ash into dispersible silica capture higher value per tonne but require capital for controlled combustion and post‑processing technologies.
-
Global chemicals entrants and distributors — large chemistry groups and refractory specialists are moving into bio‑circular silica markets through strategic plant launches and partnerships, lifting standards for quality, traceability and global supply chain compliance.
Key industry participants exemplify these archetypes. Some operate integrated milling or biomass combustion platforms, securing captive feedstock and supplying cement and construction markets; others concentrate on producing high‑amorphous silica for refractory and metallurgical uses. Meanwhile, specialist distributors and chemical groups bring scale, technical certification capabilities and access to international buyers. Recent notable developments underscore the shifting landscape:
-
Capacity additions in Southeast Asia, including commissioned rice‑husk biomass plants, are starting to deliver predictable RHA volumes and are expected to form the backbone of regional supply chains.
-
Strategic acquisitions in the biomass assets space are consolidating supply in certain markets, supporting more formalized off‑take arrangements between power plant operators and industrial consumers.
-
Major chemicals firms have initiated commercial production of bio‑derived, highly dispersible silica — an important validation of RHA’s potential as a high‑value feedstock and a signal that premium market segments will professionalize rapidly.
Operational and commercial headwinds to plan for in 2026
-
Feedstock variability and quality: controlled combustion is a non‑trivial technical hurdle. Amorphous silica content and residual carbon levels determine product acceptance in engineering applications. Due diligence must include lab‑validated performance data and on‑site combustion audits.
-
Trade and policy friction: tariffs and export controls on agricultural waste are shifting commercial flows and increasing the premium for local or regionally sourced RHA. Buyers that remain dependent on long‑haul supply should model duty and logistics surcharges explicitly into procurement strategies.
-
Logistics and certification costs: demand for certified pozzolanic material is inflating transport and handling costs for bulk RHA shipments. Contract structures that share certification burdens or that invest in localized beneficiation can mitigate per‑ton volatility.
-
Market concentration: the top tier suppliers hold a substantial combined share of capacity. This creates a two‑edged sword — stability of supply from incumbent names, but also potential pricing power that must be anticipated in scenario modelling.
A concise playbook for executives moving into 2026
-
Secure feedstock through hybrid models — a mix of captive sourcing, long‑term offtake and local spot supply — to balance cost, quality and resiliency.
-
Invest selectively in quality certification and beneficiation capacity: the premium segments reward consistent technical performance and traceability more than low unit price alone.
-
Evaluate partnerships with regional mill operators and biomass plant owners to lock in volumes and co‑invest in processing assets rather than pursuing purely transactional procurement.
-
Model policy scenarios — particularly carbon pricing and trade barriers — in all investment appraisals. A 5.0% CAGR environment amplifies returns for first movers who can also de‑risk feedstock and logistics.
-
Build an M&A screen focusing on technical capabilities (controlled combustion, silica extraction), captive feedstock and distribution reach; these characteristics predictably convert to market power as demand professionalizes.
Where to access the granular intelligence
This briefing is designed as a strategy‑grade preview. The full PW Consulting Rice Husk Ash Market report includes the granular regional and application splits, supplier scorecards, downloadable data tables, contract templates and the detailed financial models you need to translate headline growth into executable investments and procurement decisions. For teams preparing 2026 budgets or evaluating near‑term M&A, the complete dataset and supplier benchmarks are essential to calibrate risk and upside.
Rice husk ash is no longer an incidental residue; it is a material at the intersection of sustainability policy, industrial decarbonization and circular‑economy value creation. For companies that move early to secure quality, logistics and technical differentiation, 2026 offers the chance to convert modest tonnages today into strategically significant product lines for tomorrow.
For detailed analysis of this topic, please visit the official page: Rice Husk Ash Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com