

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Hydrogenated MDI Market Poised for 5.22% CAGR Through 2032

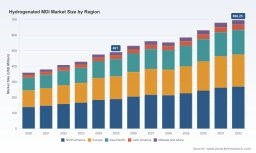
Hydrogenated MDI (H12MDI/HMDI) Market — Strategic Prelude for 2026 Decision-Makers
Executive snapshot
As PW Consulting’s Chief Industry Analyst, I present a concise strategic preview of our comprehensive Hydrogenated MDI Market study (base year: 2025; historical: 2020–2025; forecast: 2026–2032). The market’s steady expansion — underpinned by a compound annual growth rate (CAGR) of approximately 5.22% — is reshaping supplier strategies, downstream formulations, and capital allocation choices across polyurethane value chains. Measured in USD (Million), the market has grown from roughly USD 359 million in 2020 to about USD 491 million in 2025 and is projected to approach roughly USD 696 million by 2032. This trajectory signals meaningful, sustained opportunity for suppliers, converters, and end-users who can navigate supply, regulatory, and technology inflection points.
Hydrogenated MDI Market
Why this preview matters for 2026 planning
-
Investment timing: With mid-decade capacity additions and targeted product roadmaps by key producers, 2026 is a pivotal year to decide whether to secure long-term offtake, invest in backward/forward integration, or prioritize alternative chemistries.
Hydrogenated MDI Market -
Commercial positioning: The market’s structure — notably its high top-tier concentration — rewards scale, integrated feedstock strategies, and differentiated technical support. Our report quantifies concentration metrics and maps how these translate into pricing leverage, logistics resilience, and customer lock-in.
Hydrogenated MDI Market -
Regulatory and safety governance: Diisocyanate classification continues to tighten global handling standards; companies that preemptively invest in compliant processes and training will reduce operational risk and gain access to premium industrial and coatings segments.
Market dynamics: what is actually driving growth
The demand profile for hydrogenated MDI stems from a convergence of technical performance requirements and sustainability pressures. H12MDI/HMDI’s cycloaliphatic character offers improved light stability, lower yellowing, and enhanced mechanical performance relative to many aromatic alternatives — making it the material of choice for durable coatings, premium foams, elastomers, and specialty adhesives. Simultaneously, downstream trends — waterborne systems, low-VOC regulations, and electrification-driven automotive interiors — are expanding use cases for hydrogenated diisocyanates.
-
End-market pull: Automotive, architectural and industrial coatings, and high-performance polyurethane systems are key demand engines. Shifts to waterborne and low-VOC formulations increase the technical premium commanded by hydrogenated variants.
-
Supply-side adjustments: Recent capacity initiatives and producer-led vertical integration are reducing structural supply risk in some regions while concentrating market power. These moves will influence contract terms, spot availability, and grade diversity through 2032.
-
Regulatory overlay: Global diisocyanate regulations (notably in Europe and reflected in industry associations’ guidance) create elevated compliance costs and handling requirements. Firms with advanced safety systems and training protocols can convert regulatory compliance into commercial advantage.
Competitive landscape — players and strategic posture
The hydrogenated MDI market exhibits significant concentration at the top, and strategic intent among incumbents is clear. Leading manufacturers combine product portfolios, branded grades, and technical services to defend premium segments and extend applications into coatings, dispersions, and specialty foams.
-
Covestro AG (Leverkusen, Germany) — a recognized provider of hydrogenated MDI grades (Desmodur W family). Covestro competes on grade breadth and application know-how, targeting polyurethane elastomers, adhesives, and coating systems where weathering and aesthetic longevity are mission-critical.
-
Evonik Industries AG (Essen, Germany) — markets high-performance crosslinkers (e.g., VESTANAT H12MDI) and emphasizes light-stable, dispersion-friendly chemistries for premium coatings and advanced polyurethane systems. Evonik’s strength lies in coupling specialty chemistries with formulation science.
-
Wanhua Chemical Group Co., Ltd. (Yantai, China) — notable for operational scale and integration. Wanhua is an industrial-scale HMDI producer with strategic capacity in China and an active program to expand hydrogenated isocyanate output. Recent public filings and presentations demonstrate a concerted move to capture growing demand in coatings and automotive applications.
These incumbents are not merely competing on tonnage; they are optimizing feedstock integration, grade differentiation (viscosity, functionality, and impurity profiles), and downstream partnerships. The result is a market where the top three players control a majority share, and the top five capture a substantial supermajority — a configuration that shapes contract terms and innovation pathways.
Recent developments and their strategic implications
-
Capacity expansions: Announcements around increasing hydrogenated MDI output are material. Expansions on the order of tens of thousands of tonnes annually — when executed — change regional supply balances and open opportunities for new formulations that had previously been constrained by availability.
-
Technical outreach: Industry presentations highlighting hydrogenated MDI as an enabler for waterborne dispersions and low-VOC coatings suggest a proactive commercial pivot toward environmentally driven formulations. This is an early signal that producers view coatings and dispersions as growth vectors, not just niche specialties.
-
Integration and feedstock security: Firms operating integrated MDA hydrogenation technology and broad isocyanate capacity are better positioned to manage margin volatility. Integration reduces feedstock exposure and supports premium grade development for advanced applications.
-
Compliance and safety: Regulatory pressures on diisocyanates are increasing compliance costs and creating entry barriers for smaller converters. Those that proactively implement robust handling and training systems will gain preferential access to customers prioritizing supply-chain resilience.
Core takeaways for 2026 corporate action
-
Sourcing strategy: Negotiate flexibility into offtake agreements — blends of firm volumes and indexed spot exposure protect against both shortage-driven price spikes and margin compression from new capacity.
-
Product roadmap prioritization: Invest in formulations that exploit hydrogenated MDI’s light stability and low-VOC compatibility. Winning formulations will command premium pricing in segments where performance and aesthetics matter.
-
CapEx and partnership evaluation: For chemical producers, evaluate selective capacity additions in light of forecast demand growth and competitor expansions. For converters, consider strategic alliances or equity partnerships to secure feedstock access.
-
Regulatory readiness: Allocate resources to safety, worker training, and compliance documentation now; delay risks lost contracts and costly retrofits later.
-
Distribution and logistics: Optimize warehousing and transport for specialized grades (low-viscosity, stabilized products) to avoid formulation disruptions and support just-in-time manufacturing for coatings and adhesives customers.
What the full PW Consulting report delivers (practical, executable content)
Our complete Hydrogenated MDI Market study is designed as an operational playbook for 2026 and beyond. It contains:
-
Validated top-line market sizing and a transparent forecast model (2026–2032) benchmarked to historical performance (2020–2025) — all figures presented in USD (Million) with scenario sensitivities for low-, base-, and high-demand pathways.
-
Competitive scorecards that assess production footprints, branded grades, technical service capabilities, and strategic initiatives for the leading suppliers.
-
Commercial templates: negotiation levers for offtake contracts, risk-adjusted pricing models, and inventory optimization frameworks adapted to hydrogenated MDI’s supply characteristics.
-
Regulatory and safety playbooks: compliance cost estimates, certification checklists, and workforce training roadmaps tailored to diisocyanate handling requirements.
-
Go-to-market matrices mapping technical features (e.g., light stability, reactivity profiles) to prioritized end-markets and advisory recommendations for product development sequencing.
-
Investment diligence annexes: capex sizing, break-even analysis, and sensitivity testing for greenfield and brownfield expansions.
Because this preview follows a deliberate “trailer” approach, we have withheld granular subsegment tables and region/application percentage breakdowns from this summary. Those detailed matrices, supplier-by-supplier volumes, and pricing bands are included in the full report to support procurement, R&D prioritization, and M&A diligence.
How to use this analysis in boardroom decisions
-
Frame 2026 budget cycles around three scenarios (conservative, baseline, accelerated) using the report’s forecast outputs and trade-off analytics to justify capital and R&D spend.
-
Use the supplier scorecards to benchmark current partners and identify gaps in feedstock security or technical support; consider dual-sourcing or strategic inventory buffers where exposure is unacceptable.
-
Leverage regulatory playbooks to lower insurance and compliance costs—quantified readiness reduces both near-term operating risk and long-term liability.
Concluding perspective
The hydrogenated MDI market is maturing from a technically niche specialty into a structurally important segment of the polyurethane value chain. With a steady CAGR of roughly 5.22% and clear supply-side moves, 2026 is the year to translate strategic intent into procurement terms, product roadmaps, and capital commitments. PW Consulting’s full study equips decision-makers with the granular data, contract tools, and regulatory blueprints needed to act confidently. For companies that move early — securing feedstock, aligning formulations to low-VOC trends, and hardening compliance systems — the next six years offer both defensible growth and the chance to command a premium in high-value applications.
To access the detailed regional and application breakdowns, supplier volumes, and the actionable annexes referenced above, please visit our report page or contact the PW Consulting research team. The preview establishes the strategic horizon — the full report provides the tactical map.
For detailed analysis of this topic, please visit the official page: Hydrogenated MDI Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com