

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Chemical & Materials
PW Consulting: Hydrotalcite Market to Reach $273.72M by 2032 at 5.8% CAGR
By pmarketresearch, 2026-07-13
Hydrotalcite (CAS 11097-59-9): Strategic Outlook for 2026 Decision-Makers
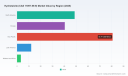
As global chemical buyers, specialty compounders, and strategic investors plan capital and commercial moves for 2026, hydrotalcite (CAS 11097-59-9) is emerging as a quietly pivotal input across plastics, pharmaceuticals, and advanced materials. PW Consulting’s new market study—anchored to 2025 as the base year and projecting through 2032—maps a market that has expanded steadily over the first half of the decade and is forecast to continue growing at a mid-single-digit compound annual growth rate. Between 2020 and 2025 the market demonstrated resilient expansion; our baseline projections point to sustained growth through 2032 under current demand drivers and regulatory trends.
Hydrotalcite (CAS 11097-59-9) Market
Why this study matters to 2026 strategy
-
Timing for capacity and product investments: Manufacturers and compounders face a choice in 2026—scale commodity-grade capacity to secure volume-led margins, or deploy capital toward high-purity and surface-modified grades that command price premia but require tighter raw-material control and regulatory certification. Our forecast trajectory provides the demand visibility needed to validate either path and to phase capex with confidence.
Hydrotalcite (CAS 11097-59-9) Market -
Regulatory compliance as a market filter: Regulatory tightening in major markets is transforming hydrotalcite from a simple heat stabilizer to a certified excipient and specialty additive. Companies that align R&D and quality systems to evolving REACH and FDA excipient guidance will unlock higher-margin channels in pharmaceuticals and food-contact applications.
Hydrotalcite (CAS 11097-59-9) Market -
Supply-chain resilience and feedstock security: The synthesis route for high-quality hydrotalcite is dependent on purified magnesium and controlled co-precipitation processes. Procurement executives will need scenario-based sourcing strategies to mitigate volatility in feedstock purification costs and to assure pharmaceutical-grade traceability.
Market health at a glance (high-level)
Our study documents year-by-year market size from 2020 through 2032 in USD (Million). The market expanded from the early-2020s into 2025 and is forecast to continue its upward trajectory through 2032 at an approximate CAGR of 5.8% under the base-case assumptions used in this research. This growth reflects the combined effect of persistent demand in polymer stabilization, renewed uptake in pharmaceutical and food-grade applications, and incremental adoption in advanced material and flame-retardant applications tied to electrification and cable insulation trends.
Note: This introduction deliberately presents high-level market trends and the headline growth assumptions to inform executive decision-making. Core segmentation data, price curves, and addressable-market breakdowns are reserved for the full report to preserve the competitive intelligence value of the dataset.
Demand-side dynamics
-
Polymer and PVC stabilization remain the dominant demand pillars. The combination of performance (heat stability, halogen scavenging) and an accelerating regulatory preference for heavy-metal-free stabilizers has kept hydrotalcite central to formulation strategies across flexible and rigid PVC and an increasing share of polyolefin formulations.
-
Pharmaceutical and food-grade applications are a fast-follow opportunity: enhanced purity grades, validated excipient status, and tailored particle morphologies enable entry into antacid and excipient markets, but require significant investment into GMP-style production controls and certification programs.
-
Electrification and flame retardancy: Electric vehicle wiring, cable insulation, and flame-retardant masterbatches are driving demand for engineered hydrotalcite grades. These grades often have surface treatments or tailored compositions to improve dispersion and performance in filled systems.
Supply-side and manufacturing considerations
-
Raw-material purification is non-trivial. Industrial magnesium feedstocks require stringent cleanup to meet high-purity and pharmaceutical specifications; this adds technical and cost layers that favor incumbents or vertically integrated players who can secure feedstock quality.
-
Specialty grades increase technical complexity. Nano-sized and surface-treated materials deliver performance benefits but introduce higher production costs and narrower commercial windows in price-sensitive markets. Adoption will be stepwise and concentrated in applications with clear value capture.
-
Geographic deployment of capacity matters. Recent capacity additions in Europe and new lines targeting European compounders demonstrate suppliers’ strategic focus on proximity to automotive, cable, and pharmaceutical hubs. Companies planning investments should align plant footprints with regulatory, logistics, and customer concentration maps.
Competitive landscape — what to watch
The hydrotalcite market exhibits a moderate degree of concentration: top-tier manufacturers command meaningful scale and technical advantage, while a broader tier of regional suppliers competes on cost and service. Our research maps incumbent strengths and strategic moves by companies that set the tone for 2026:
-
Kyowa Chemical Industry (Japan) — an early industrial pioneer with product families oriented to PVC stabilization and medical antacids. Their recent investments to expand European supply capacity reflect a play to serve both polymer and pharma customers with high-purity grades.
-
Sakai Chemical Industry (Japan) — specialist grades targeting thermal performance and color retention in plastics. Expansion activity aimed at EV wire insulation underlines the company’s tactical pivot to flame-retardant markets.
-
Clariant AG (Switzerland) — a major specialty player focusing on heavy-metal-free formulations and recently expanding European capacity while licensing new high-purity grades for pharmaceutical use. Clariant’s moves illustrate how broad chemical platforms can accelerate grade development and regional market access.
-
SINWON Chemical, GCH Technology, Doobon, Sasol, and Heubach — these regional and multinational players provide diversified supply, technical service, and localized product variants. Their combined presence sustains competition on price, grade breadth, and proximity to downstream manufacturers.
Recent publicly announced capacity and product initiatives during 2025 illustrate a clear pattern: supply-side incumbents are securing footprint and introducing pharmaceutical- and specialty-oriented grades to capture value beyond commodity PVC markets. For buyers and investors, this signals a tightening of the premium-grade supply curve during the mid-decade planning horizon.
Regulatory and sustainability context
-
Regulatory tightening is a differentiator. REACH in Europe and evolving FDA excipient expectations in the U.S. raise the bar for documented purity, impurity profiles, and manufacturing controls. Certifications and validated supply chains will be prerequisites for pharmaceutical and food-contact adoption.
-
Environmental preferences are reshaping formulations. A significant portion of industrial adoption reflects a shift toward eco-friendlier stabilizers, where hydrotalcite’s profile can be advantageous versus legacy heavy-metal chemistries.
Strategic implications and recommended actions for 2026
-
For producers: adopt a tiered-capability strategy. Separate investments into (a) cost-competitive commodity capacity to protect volume channels and (b) certified, high-purity lines with traceability and quality systems to serve pharmaceuticals, food, and high-value polymer applications. Align capex phasing with our forecast horizon to avoid overcapacity risk.
-
For compounders and OEMs: specify material provenance and performance thresholds now. Locking supply agreements with certified suppliers and qualifying alternative grades will lower disruption risk and protect product claims in regulated markets.
-
For investors and M&A strategists: target bolt-on acquisitions that provide regulatory-qualified manufacturing or feedstock purification capabilities. Add-on plays that compress time-to-market for pharmaceutical grades are likely to offer asymmetric returns.
-
For procurement and risk teams: stress-test supplier base against scenarios of feedstock constraint and regulatory change. Diversify across technologies (e.g., sol-gel vs co-precipitation routes) and negotiate quality escrow arrangements for excipient-grade supply.
What the full report delivers
PW Consulting’s full market research expands the strategic threads above into actionable deliverables: a granular addressable-market model, price and margin curves by grade, supply-demand balance by scenario, supplier scorecards, regulatory roadmaps, supply-chain stress tests, go-to-market playbooks for specialty-grade launches, and a prioritized M&A watchlist. The report also includes primary-sourced interviews with compounders and manufacturers, and an annotated timeline of regional capacity moves and product innovations.
To preserve the competitive integrity of our analysis—and to provide readers with a clear incentive to engage—this introduction presents the headline forecasts and strategic implications while reserving detailed segmentation and operator-specific share data for the full study.
Next steps for executives
-
Use the headline growth profile and the regulatory trends summarized above to validate 2026 capital and sourcing decisions.
-
Commission a focused supplier qualification audit if your product roadmap includes pharmaceutical or food-contact claims; the ramp from polymer-grade to excipient-grade is operationally intensive.
-
Engage with PW Consulting for a tailored briefing that maps our full dataset to your company’s product lines, procurement footprint, and regulatory exposure.
Hydrotalcite is no longer a niche filler; it is a strategic lever across multiple value chains. In 2026, the companies that convert regulated-quality capability into scalable supply while maintaining cost discipline will capture the most attractive economics. For the complete segmentation, price schedules, supplier scorecards, and scenario-modeled forecasts that support these decisions, consult the PW Consulting full Hydrotalcite (CAS 11097-59-9) Market report.
For detailed analysis of this topic, please visit the official page: Hydrotalcite (CAS 11097-59-9) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Lightweight Conveyor Belts Market: USD 215M in 2025, rising to USD 390.5M by 2032 at 8.9% CAGR
By pmarketresearch, 2026-07-13
Lightweight Conveyor Belts Market — Strategic Imperatives for 2026 Decision-Making
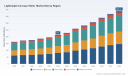
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a distillation of the strategic intelligence embedded in our new Lightweight Conveyor Belts Market study. Anchored on a 2025 base year and a projected compound annual growth rate (CAGR) of 8.9% over the 2026–2032 forecast window, the market demonstrates robust expansion: from roughly USD 163 million in 2020 to an estimated USD 215 million in 2025, and approaching USD 391 million by 2032. For executives planning capital allocation, product roadmaps, or M&A moves in 2026, the right combination of timing and precision will determine winners and also-rans. This introductory briefing highlights the report’s strategic value while intentionally withholding core segment-level datapoints to guide you to the full study for the detailed models and proprietary spreadsheets.
Lightweight Conveyor Belts Market
Why this research matters in 2026
-
Actionable forecasting: The study converts a multi-year growth trajectory and volatility drivers into scenario-ready forecasts. CFOs and strategy teams can translate these into CAPEX phasing and working-capital models for 2026–2028.
Lightweight Conveyor Belts Market -
Competitive signaling: Our analysis exposes where leading vendors are placing bets—capacity expansion, product extensions, and hygiene-led innovation—enabling timely countermeasures or partnership plays.
Lightweight Conveyor Belts Market -
Risk-to-reward clarity: The report isolates raw-material sensitivity, regulatory risk, and aftermarket service opportunities so procurement and commercial functions can prioritize hedges and premium pricing where feasible.
-
Execution playbooks: For product managers and business development teams, the study translates macro trends into prioritized initiatives (e.g., material selection, modularization, service models) with measurable ROI frameworks.
Market dynamics shaping 2026 decisions
-
Structural demand drivers: Continued automation in food processing, e-commerce-driven logistics, and tighter hygiene regimes are core growth levers. Lightweight belts reduce conveyor energy demand and machine wear, accelerating replacement and retrofit cycles across automation projects.
-
Material & cost pressure: Polyurethane and other engineered thermoplastics remain attractive for hygiene and durability, but producers face cost pressures from feedstock volatility. In 2026 we observed material price upticks in key Asia supply hubs that compress margins for PU-heavy portfolios, prompting manufacturers to reassess pricing and sourcing strategies.
-
Regulatory & standards convergence: Food contact regulations across major markets (FDA, EU) and machine-safety standards such as ISO 22100-4 are tightening spec requirements. Compliance is now a commercial differentiator—buyers increasingly treat certifications and documented hygienic performance as non-negotiable selection criteria.
-
Environmental and process innovation: Water-based polyurethane and other lower-VOC formulations are moving from niche to mainstream as OEMs and end-users seek both hygiene and reduced environmental footprint. This shift is reflected in recent capacity and product investments by major suppliers.
-
Channel & aftermarket economics: Serviceable, retrofit-friendly belt designs and digital condition monitoring are unlocking recurring revenue streams—an important margin lever as product commoditization accelerates.
Competitive landscape — what the incumbents’ moves signal
The market exhibits moderate concentration: the top three players account for a meaningful but not dominant share of global revenues, and the top five consolidate a clear majority of industry scale. This structure creates an environment where global leaders set technology and compliance benchmarks, while focused specialists capture niche premium segments.
-
Habasit (Switzerland) — Strengths: fabric-based hygienic belts and deep food-sector relationships. Strategic relevance: leadership in tailored solutions for hygienic processing lines; watch for moves into integrated service contracts and digital installation aids.
-
Ammeraal Beltech (Netherlands) — Strengths: broad synthetic and modular portfolio plus fabrication capabilities. Strategic relevance: recent investments include a new plant dedicated to water-based polyurethane production—an explicit bet on sustainable, food-grade chemistries and a signal to competitors to de-risk legacy solvent-based supply chains.
-
Chiorino (Italy) — Strengths: precision in process-belt engineering for industrial automation. Strategic relevance: vertical focus on automation OEMs gives it a route to embed belts within machine-package sales, increasing switching costs for end-users.
-
Forbo Siegling (Germany) — Strengths: Transilon fabric-based belts and modular plastics. Strategic relevance: positions itself across fabric and plastic lines—an advantage in mixed-application accounts requiring both solutions.
-
Intralox (United States) — Strengths: modular plastic solutions optimized for food hygiene. Strategic relevance: aggressive product cadence in 2026 (notable belting and installation tool launches) shows a dual track of product performance improvement and installer productivity — a classic penetration strategy.
-
Volta Belting (Netherlands) — Strengths: homogeneous thermoplastic belts focused on hygiene and durability. Strategic relevance: recent introduction of a high-strength hygienic material underscores premiumization and the value of material science differentiation at trade shows and sector events.
-
Derco & Esbelt (Netherlands/Spain) — Strengths: pragmatic portfolios across PVC, PU, and plastic modular belts. Strategic relevance: these players often serve regional channels and act as important partners for OEMs seeking localized supply and fabrication services.
Taken together, these moves show an industry where incumbents deploy a mix of product innovation, capacity expansion, and installation/service tooling to protect margins and capture long-term service revenues. For potential entrants or capital allocators, the message is clear: compete on demonstrable hygiene performance, installer ergonomics, and supply-chain resilience—not just price.
What the full report delivers (actionable scope)
-
Robust market sizing and forecast models (2020–2032) including base-year reconciliation and scenario overlays tuned to material-price shocks and regulatory shifts.
-
Segment-level maps across types, applications and regions with buyer persona profiles that translate technical specifications into procurement decision criteria.
-
Profit-pool analysis identifying where manufacturing scale, customization, and aftermarket service create highest margin opportunities.
-
Supply-chain sensitivity matrix quantifying impact of raw-material swings and regional sourcing constraints on gross margins, with suggested procurement hedge structures.
-
Competitive benchmarking including product-technology matrices, capability heatmaps and a tactical watchlist of near-term strategic moves by key vendors.
-
Regulatory and standards playbook mapping compliance checkpoints by region and application—critical for commercialization timelines in food and pharma segments.
-
Decision-ready playbooks for go-to-market, pricing, channel design and M&A screening (including deal rationale templates and integration checklists).
-
Downloadable excel models and sensitivity dashboards for CFOs to stress-test CAPEX alternatives and investment returns under multiple scenarios.
How to use these insights in your 2026 playbook
-
Prioritize investments where regulatory and hygiene tailwinds create premium pricing power. If you serve food processors or pharma, emphasize certified materials and documented cleaning protocols.
-
Stress-test procurement: run material-price stress scenarios and build alternative sourcing and substitution strategies for polymer feedstocks—particularly polyurethane inputs where feedstock volatility can quickly erode margins.
-
Design product roadmaps that combine material innovation with installer ergonomics and serviceability. Tool launches that improve installation consistency (tensioning tools, clamp sets) amplify product propositions and reduce system downtime — a clear route to aftermarket revenues.
-
Consider targeted capacity moves or partnerships: the market’s concentrated but fragmented nature means strategic joint ventures or bolt-on acquisitions can rapidly scale capabilities in hygiene-certified manufacturing or localized fabrication.
-
Embed service and digital monitoring as part of pricing strategies. Recurring revenue models mitigate cyclical exposure and raise lifetime value per account.
Top-level recommendations
-
Make hygiene- and compliance-led product differentiation a priority rather than an afterthought.
-
Hedge feedstock exposure through diversified procurement and consider investing in water-based chemistries or alternative polymers.
-
Invest in installer productivity and condition-monitoring tools to unlock aftermarket margins.
-
Pursue targeted M&A or partnerships to achieve regional scale quickly where you lack fabrication or service presence.
-
Use scenario modeling to phase CAPEX aligned to 2026 demand inflection points—avoid all-or-nothing expansion bets.
PW Consulting’s full Lightweight Conveyor Belts Market report contains the granular segment models, regional breakdowns and proprietary market-share datasets that underpin these strategic takeaways. This introduction is designed as a tactical “preview”: it maps the terrain and flags where real competitive advantage will be earned in 2026, while preserving the detailed segment outputs and decision tools for the full report. For organizations preparing board-level investment memoranda, supplier negotiations, or acquisition screens this year, the full dataset and executable playbooks provide the difference between informed risk and speculative bets.
Contact the PW Consulting publications desk to access the complete study, the downloadable financial models, and the executive briefing package tailored for your strategic planning cycle.
For detailed analysis of this topic, please visit the official page: Lightweight Conveyor Belts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Polycarboxylate Superplasticizers Market: PW Consulting Forecast Shows 5.98% CAGR (2026–2032)
By pmarketresearch, 2026-07-13
Polycarboxylate Superplasticizers Market — Strategic Preview for 2026 Decision-Makers
At PW Consulting, our practice advises boards, corporate strategy teams, and private equity sponsors on where to allocate capital and how to de-risk market-entry and scale-up plans. This market intelligence preview summarizes the high-conviction findings from our full Polycarboxylate Superplasticizers (PCE) Market study (base year 2025; historical 2020–2025; forecast 2026–2032), and explains why executives with 2026 decision horizons should prioritize this dossier.
Polycarboxylate Superplasticizers Market
Market snapshot — what the headline numbers mean for strategy
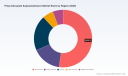
Our analysis quantifies a PCE market that expanded steadily through the 2020–2025 period and is projected to grow at a compound annual growth rate (CAGR) of approximately 5.98% over the 2026–2032 forecast window. In plain terms, demand and revenue trajectories that were measured in the low‑to‑mid billions of USD in the early 2020s pass into a materially larger market by the early 2030s. This pace of expansion is significant for capital allocation: it supports greenfield investments, targeted capacity expansions, and bolt‑on M&A programs, but it also requires disciplined supply‑chain and risk management to protect margins.
Polycarboxylate Superplasticizers Market
Importantly, the headline growth masks heterogeneity across customer segments, value chain positions, and geographies. The full report preserves that segmentation granularity for subscribers, but in this preview we intentionally withhold detailed split tables and point readers to the source page for the full data set. What follows is actionable perspective rather than raw sub‑segment disclosure.
Polycarboxylate Superplasticizers Market
Why the 2026 planning cycle is pivotal
- CapEx timing and lead times: Chemical plant expansions, polymerization lines, and third‑party tolling agreements have multi‑year lead times. Decisions taken in 2026 determine utilization and competitive positioning into the 2030–2032 window when market demand is significantly higher.
- Input cost volatility: Key monomers and co‑polymers that feed PCE synthesis experienced disruptive price swings in recent years. Supply disruptions and geopolitical events in 2025 fed through into raw material inflation, tightening spot availability at critical points in the value chain — a pattern we expect to continue in scenarios where feedstock markets remain tight.
- Product evolution and differentiation: Third‑generation PCE chemistries (monomer innovations, tailored side chains, powder vs liquid formulations) are moving from R&D into commercial rollouts. License, JV, or acquisition strategies executed in 2026 will determine who captures the premium for higher‑margin, high‑performance admixtures.
- Regulatory tightening: Compliance costs are rising (our modeling shows environmental and safety regulation headwinds can increase marginal production costs noticeably), and standards such as REACH require more granular substance submissions and residual monitoring. Firms that retro‑fit compliance into late‑stage expansion programs will underperform those that design for compliance from the outset.
Key demand and supply drivers
- Infrastructure and urbanization: Continued infrastructure replacement and urban construction activity underpin steady base demand, while pockets of accelerated activity (high‑rise, precast, high‑performance concrete projects) drive premium product uptake.
- Performance requirements: Concrete mix optimization for higher strength, lower water/cement ratio, and faster cycle times incentivizes adoption of advanced PCE formulations.
- Raw material dynamics: TPEG/HPEG feedstock and acrylic monomers remain the single largest source of margin volatility for producers. Recent market signals show spot prices moving sharply in response to petrochemical plant outages and extended feedstock chain disruptions; procurement strategies (vertical integration, long‑term supply agreements, hedging) materially change profitability profiles.
- Environmental, social and governance (ESG) pressures: Buyers increasingly demand suppliers who can demonstrate lower embodied carbon and robust chemical safety management. PCE producers who can quantify life‑cycle benefits and reduce manufacturing emissions gain advantaged access to institutional buyers.
Risks and scenario sensitivities
- Geopolitical shocks: Middle‑East supply chain tensions in 2025 already contributed to raw material cost spikes; similar shocks can rapidly compress margins for unconsolidated producers.
- Regulatory compliance cost inflation: Stringent chemical registration and monitoring requirements lift operating expense; our scenario testing shows that non‑compliant or late‑compliant players face both cost penalties and market access restrictions.
- Technology substitution risk: Incremental improvements in alternative admixtures or mix designs could erode the premium for certain PCE grades; sustained R&D investment is required to protect value.
- Concentration and pricing pressure: While top incumbents retain strong customer relationships and technical service capabilities, the market is not immune to price competition from lower‑cost regional suppliers or factory‑direct producers. Competitive dynamics vary by channel and application.
What the full report contains — practical, deal‑ready analysis
Our full market study is designed for immediate boardroom use. Key deliverables include:
- Transparent market sizing and revenue modeling (base year 2025; historical 2020–2025; forecast 2026–2032) with sensitivity ranges and scenario outputs suitable for valuation models.
- Demand segmentation by application and region with addressable market maps, adoption curves, and value capture pathways (note: detailed segment tables are gated to preserve subscriber value).
- Supply‑chain mapping, raw‑material exposure matrices, and procurement playbooks highlighting where to lock margins through feedstock strategies.
- Regulatory impact assessment (REACH and regional chemical compliance), compliance cost estimates, and a roadmap to design-for-compliance in new plants.
- Competitive benchmarking with each major player profiled on product portfolio, channel strategy, technical service capability, and partnership history.
- Transaction guidance: a short‑list of acquisition targets and low‑hanging collaboration opportunities, valuation triangulation, and integration risk checklists.
- Commercial playbooks for go‑to‑market (pricing, distribution, specification management) and product development (formulations, powder vs liquid commercialization tradeoffs).
Competitive landscape — who to watch
The market features a mix of global chemical majors, specialized admixture producers, and vertically integrated regional players. Below are the principal companies we profile in depth (headquarters and web references included as a convenience):
- Sika AG (Baar, Switzerland) — https://www.sika.com — notable for its ViscoCrete® PCE portfolio targeting high‑performance concrete.
- BASF SE (Ludwigshafen, Germany) — https://www.basf.com — a major innovator; recently introduced a new iPEG monomer platform designed for third‑generation PCEs.
- GCP Applied Technologies (Alpharetta, GA, USA) — https://gcp.com — producer of ADVA® products focused on admixture performance.
- Chryso (Courbevoie, France) — https://www.chryso.com — supplier to ready‑mix and paving segments with a broad admixture range.
- Fosroc International (London, UK) — https://www.fosroc.com — offers high‑range water reducers for performance‑critical mixes.
- Arkema (Colombes, France) — https://www.arkema.com — a provider with integrated construction chemicals capabilities.
- Mapei S.p.A. (Milan, Italy) — https://www.mapei.com — notable for construction chemicals and PCE formulations.
- Kao Corporation (Tokyo, Japan) — https://www.kao.com — supplier of admixtures focused on regional markets.
- Selected Chinese producers (examples include Sobute, MUHU, Jiahua, Kima, WOTAIchem) — factory‑direct suppliers that compete aggressively on price and local service.
- Altus Material and CEMEX Admixtures (U.S.) — https://altusmaterial.com, https://www.cemex.com — examples of localized innovation and integration with concrete producers.
Recent industry moves underscore the strategic dynamics we describe: in 2025 a major chemical company launched a new isoprenol‑PEG monomer specifically targeted at third‑generation PCEs; another announced capacity expansion in Europe to capture rising demand. These actions validate our view that both product innovation and scale remain decisive competitive levers.
Executive imperatives for 2026
- Stress‑test your portfolio against feedstock scenarios: model PCE margin sensitivity to TPEG/HPEG and acrylic price shocks; shift procurement from spot to diversified long‑term contracts where feasible.
- Prioritize regulatory‑first design: build environmental and chemical‑compliance costs into new capacity models and product development roadmaps to avoid retrofit penalties.
- Choose commercialization pathways deliberately: decide whether to compete on premium technical service and differentiated chemistries, or to pursue cost leadership through local, factory‑direct models — both are viable, but require different operating models.
- Assess M&A targets with integration playbooks: target regional producers with complementary channels or specific formulation IP; a short due‑diligence checklist in our report speeds appraisal.
- Invest in customer co‑development: technical support and lab‑to‑site trials remain the fastest route to specification wins in concrete contractors and precast manufacturers.
How to use this preview
This preview is intentionally focused on strategic implications and topline metrics. The full PW Consulting PCE Market study contains the fortified datasets, regional and application-level breakouts, supplier share matrices, and downloadable financial models that boards and deal teams need to execute decisively in 2026. We have withheld specific segmentation tables and sensitive competitive concentration metrics from this summary to protect the commercial integrity of the fieldwork and to ensure subscribers receive exclusive access to the full intelligence package.
Contact PW Consulting to request the full report, the underlying datasets, or a tailored executive briefing. In markets where lead time, feedstock volatility, and regulatory pressure converge, the difference between a reactive plan and a proactive strategy is measured in months — not years. For executives planning capital and commercial moves in 2026, the time to act is now.
For detailed analysis of this topic, please visit the official page: Polycarboxylate Superplasticizers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Phenolic Resins Market Set to Grow at a 4.8% CAGR through 2032
By pmarketresearch, 2026-07-13
Phenolic Resins Market 2026: Strategic Imperatives for Decision-Makers
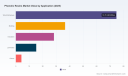
As companies recalibrate product portfolios and capital plans for the 2026 planning cycle, phenolic resins sit at a strategic crossroads. PW Consulting’s latest market study synthesizes seven years of historical performance (2020–2025) and provides a granular forecast through 2032, equipping executives with the evidence base required to make high‑stakes commercial, supply‑chain, and R&D decisions. The market is on a steady growth trajectory—our base‑case forecast uses a 4.8% CAGR across the 2026–2032 horizon—underscoring both continuity and pockets of rapid change that demand differentiated responses.
Phenolic Resins Market
Why this study matters for 2026 decisions
-
Timing: Boardrooms must decide now whether to accelerate investments (capacity, low‑emission chemistry, circular technologies) or to prioritize contract and margin protection. Our research translates long‑range projections into immediate decision nodes for 2026 planning cycles.
Phenolic Resins Market -
Calibrated risk: Macro signals—raw material volatility, emerging regulation, and shifting end‑market demand—are already compressing margins for unprepared players. The study quantifies these pressures and presents tactical mitigations that can be executed within the next 12 months.
Phenolic Resins Market -
Competitive clarity: With market concentration remaining moderate (the top three and top five players together do not dominate the space), strategic moves—alliances, targeted M&A, and niche product investment—can materially shift competitive positions. The report provides framework-level analyses that translate to acquisition screening and partnership roadmaps.
Market trajectory — data-driven context without the clutter
Our modelling shows the phenolic resins sector growing consistently from the 2025 base year through 2032 under a central scenario that assumes ongoing industrial demand and partial upstream cost pass‑through. The 4.8% CAGR embeds plausible scenarios for feedstock swings, regulatory tightening, and adoption of low‑emission or biomass‑derived chemistries. While we intentionally omit detailed subsegment tables here, the full study presents end‑market and regional forecasts, elasticity matrices, and revenue-attribution models that enable targeted revenue and margin forecasts for specific business lines.
Critical dynamics shaping near‑term strategy
-
Feedstock and pricing pressure: In late 2025, Asian market prices reached multi‑regional highs driven by firm phenol and formaldehyde costs (industry benchmarks peaked around the mid‑single dollars per kilogram in Asia and remained elevated in North America). These moves were accompanied by double‑digit quarter‑over‑quarter shifts in some locales—an operational shock that forced manufacturers to rethink short‑term procurement and hedging approaches.
-
Regulatory squeeze: Following regulatory designations that highlighted the risks associated with formaldehyde, U.S. resin manufacturers reported a material increase in compliance costs (an industry‑level uplift in the tens of percent). Concurrently, European postponements of certain approvals have delayed capacity expansions and accelerated demand for low‑emission formulations. Together, these developments make regulatory‑adjusted cost modelling an essential input for 2026 capital allocation decisions.
-
Sustainability and circularity as value levers: Advances in biomass‑modified and mechanically recyclable phenolic chemistries—already commercial in pilot and early commercialization stages—are shifting product value propositions from cost‑based to solution‑based. Early movers gain pricing premium access in sensitive end markets such as automotive friction materials and formaldehyde‑sensitive wood products.
Competitive landscape — positioning and implications
The competitive map is a mix of multinational chemical groups, specialized resin houses, and regional producers. Global leaders have pursued capacity optimization and product diversification; for example, large integrated chemical companies have announced site expansions aimed at adhesives, molding compounds, and insulation markets. Specialist players are competing on formulation depth—novolac, resol, and biomass‑modified grades—and on targeted end‑market penetration such as brakes/friction, engineered wood, and advanced composites.
-
Strategic plays by majors: Multinational incumbents leverage scale to invest in compliance, low‑emission grades, and geographic footprint resilience. These companies can afford elongation of payback on green investments to secure long‑term offtake across multiple end markets.
-
Specialist differentiation: Companies with deep expertise in novolac/resol formulations or in lignin‑modified chemistries are positioned to capture margin uplift from premium segments. Recent product launches targeting ultra‑low monomer titers and biomass‑derived grades illustrate the tactical R&D routes available.
-
Consolidation and partnership activity: Transactions and portfolio reshuffles—acquisitions of regional resin businesses, joint ventures for localized production, and licensing of recycling technologies—are pragmatic responses to regional feedstock variability and regulatory fragmentation.
Recent industry movements that change the tactical playbook
-
Product innovation: New launches focused on ultra‑low monomer water‑soluble resins and biomass‑derived novolac types demonstrate a dual pathway to de‑risk regulatory exposure and capture sustainability premiums.
-
Recycling initiatives: Mechanical recycling pilots announced by leading resin manufacturers signal that circularity is moving from lab to line‑trial—creating opportunities for closed‑loop supply agreements with downstream OEMs.
-
Upstream cost shocks and pricing transmission: Regional price spikes in 2025 forced rapid renegotiation of forward contracts and disclosures of compliance cost impacts—lessons that must inform contract design and pass‑through clauses in 2026.
What the PW Consulting report delivers — operationally useful content
We structured the study to be immediately actionable for commercial, R&D and corporate development teams. Key deliverables include:
-
Scenario-based revenue and margin models: Customizable spreadsheets that allow users to stress test up to three demand and two feedstock price paths across the forecast horizon.
-
Regulatory impact calculator: Quantifies incremental compliance costs and time‑to‑market delay for product variants across principal jurisdictions.
-
Supply‑chain heatmaps and concentration analysis: Visuals that identify single‑point vulnerabilities in feedstock supply and logistic chokepoints, with recommended mitigation playbooks.
-
Competitive benchmarking and capability matrix: A layered view of incumbent strengths—capacity, product breadth, sustainability initiatives—and the strategic options to neutralize or exploit them.
-
M&A and partnership screening toolkit: A pragmatic rubric for target prioritization based on strategic fit, regulatory exposure, and integration complexity.
-
Commercial playbooks: Go‑to‑market and pricing strategies for new low‑emission products and recycled‑content grades, including sample contract language to preserve margin under volatile feedstock conditions.
Strategic recommendations for 2026 planning
-
Prioritize modular CapEx and flexible operating models: Given up‑and‑down feedstock cycles and regulatory uncertainty, favor investments that can be staged and repurposed across product families.
-
Fast‑track low‑emission and biomass pathways where customer willingness to pay is demonstrable: Segments sensitive to formaldehyde exposure and sustainability credentials will pay premiums for de‑risked chemistries; early certification and customer‑co‑development accelerate adoption.
-
Lock in feedstock through blended procurement and local partnerships: Combine market hedges with regional sourcing agreements to reduce exposure to single‑region price shocks demonstrated in late‑2025.
-
Adopt an M&A first filter focused on technology or regional capacity gaps: Targeted acquisitions can deliver step changes in market access and regulatory compliance capabilities faster than organic programs.
-
Embed regulatory scenario planning into product roadmaps: Use the regulatory impact calculator to translate compliance shifts into P&L outcomes and adjust launch sequencing accordingly.
-
Design commercial contracts with dynamic pass‑throughs: Incorporate clear mechanisms for pricing adjustments tied to validated feedstock indices and regulatory cost bands.
Closing — the value proposition for executives
For 2026 corporate plans, the choice is between reactive cost management and proactive strategic capture. PW Consulting’s Phenolic Resins Market study brings together forecasted market trajectories, regulatory and feedstock stress testing, and commercially actionable tools that enable both. We show where to defend today and where to invest for asymmetric returns tomorrow.
To maintain the report’s role as an actionable decision‑support asset, we have intentionally withheld detailed subsegment tables within this summary (regional and application‑level granularity, and precise revenue splits are available only in the full report). Accessing the full dataset and modelling assets will let your team run tailored scenarios—unlocking the precise answers needed for board presentations, CapEx approval, and commercial contract redesign in 2026.
For detailed analysis of this topic, please visit the official page: Phenolic Resins Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Gray Iron Castings Market to Grow at 4.2% CAGR (2026–2032)
By pmarketresearch, 2026-07-13
Gray Iron Castings Market — Strategic Preview for 2026 Decision-Makers
As global manufacturers and buyers reassess supply chains, material choices, and capital allocation for the coming investment cycle, the gray iron castings market is quietly reasserting its relevance. PW Consulting’s forthcoming Gray Iron Castings Market study (base year 2025) synthesizes five years of historical performance and a seven-year forecast horizon to provide the actionable intelligence executives need to make confident decisions in 2026. This preview outlines why the report matters, what the macro trajectory implies for strategy, and how leading firms are already positioning themselves — while intentionally holding back granular segment tables to encourage exploration of the full study.
Gray Iron Castings Market
Why 2026 Is a Strategic Inflection Point
-
Post-pandemic normalization combined with policy-driven reshoring and sustainability mandates is creating differential demand across industries that rely on iron castings. Executives who move from reactive cost management to proactive portfolio reshaping in 2026 will capture superior margin recovery and secure long-term OEM partnerships.
Gray Iron Castings Market -
Capital cycles for foundry modernization have accelerated. Significant investments in automation, emissions controls, and digital shop floor capabilities are changing the cost structure and competitiveness of established foundries versus newer entrants.
Gray Iron Castings Market -
Material substitution debates (lightweighting vs. lifecycle emissions) are maturing. Gray iron is increasingly evaluated on total-cost-of-ownership and cradle-to-gate emissions, not just per-part weight — forcing procurement and engineering teams to rethink specification strategies.
Market Trajectory — High-Level View
PW Consulting’s analysis places the global gray iron castings market on a steady recovery and expansion path. Using 2025 as the base year, the market is projected under our central scenario to grow at a compound annual growth rate (CAGR) of 4.2% across the 2026–2032 forecast window. This trajectory reflects a mix of steady end-market demand, measured capacity additions, and improving utilization in key foundries.
To give executives a sense of scale without disclosing detailed line-item splits: the market has expanded consistently through the 2020–2025 historical period and is expected to continue its upward momentum into 2032 under the baseline assumptions used in our modeling. The study includes alternative scenarios showing the sensitivity of market size to cyclical demand shocks, raw-material volatility, and regulatory tightening — tools that are essential for stress-testing investment cases.
Dynamics Shaping Supply and Demand
-
Raw material and scrap availability: The short-term moderation of ferrous scrap prices and increased scrap flows have reduced some input-cost pressure in 2025. However, our scenario work shows that localized scrap shortages or logistics bottlenecks can rapidly reverse cost trends — a core risk for high-volume, low-margin foundries.
-
Environmental regulation and decarbonization: Ongoing regulatory tightening on foundry emissions is increasing the capital intensity of operations. The need for advanced pollution control equipment and compliance monitoring is elevating the minimum viable scale for foundry investments in certain jurisdictions.
-
Trade and policy shifts: Recent policy moves favoring domestic manufacturing and selectively higher tariffs on certain imports are shifting sourcing decisions. These policy signals are accelerating conversations around reshoring and nearshoring, and are materially influencing the make-or-buy calculus for manufacturers that previously relied heavily on low-cost imports.
-
Technology and process innovation: Automation in molding, improved simulation for metallurgical properties, and higher degrees of factory connectivity are delivering quality and throughput benefits that are increasingly decisive in customer selection. Foundries that combine metallurgical expertise with digital capabilities are gaining share in precision and safety-critical applications.
Competitive Landscape — What the Major Players Signal
The industry displays moderate concentration: the top three and top five players control a meaningful share of the market, reflecting both scale advantages and regional reach. Within this context, several corporate moves and capital programs are particularly illustrative for strategists:
-
Waupaca Foundry (Waupaca, Wisconsin) is completing a multi-year modernization program and has restructured its sales organization to better serve diverse customer groups. Their investments underscore a thesis that scale combined with targeted value-added services remains a defensible model.
-
Grede Holdings and other tier-one suppliers continue to emphasize precision and heavy-duty components for automotive and off-highway applications, reinforcing their role as partners to large OEMs that demand rigorous quality consistency.
-
Family-owned and regional specialists such as Lemfco and Great Lakes Castings demonstrate the enduring market for nimble, small-to-medium run capabilities — a reminder that not all customers trade exclusively on price; responsiveness and engineering support carry premium value.
-
International players, notably major Chinese integrated foundries, continue to compete on capacity and cost, but face growing headwinds from sustainability requirements and changing trade patterns — dynamics that will reallocate competitiveness over the medium term.
-
M&A and consolidation are active themes. Recent corporate developments, including strategic acquisitions and publicized capital programs, indicate that buyers are consolidating capabilities to offer broader product portfolios and geographic coverage.
Practical Contents of the Full Study — What You Can Use Immediately
The full PW Consulting report goes beyond high-level forecasting to provide operationally relevant tools for 2026 planning cycles. Key deliverables include:
-
Decision frameworks for sourcing (make, buy, or partner) that quantify the trade-offs between landed cost, lead time, and environmental compliance risk.
-
Scenario-based financial models that allow users to input their own assumptions on material prices, utilization rates, and capital expenditure to see bottom-line impact across 2026–2032.
-
Supplier due-diligence templates focused on metallurgical capability, process controls, and traceability — designed for both procurement and engineering teams.
-
Playbooks for foundry modernization, covering expected yield improvements, emissions-control options, and digital roadmaps, with payback benchmarks tailored to small, medium, and large operations.
-
Regulatory heat maps and policy scenario analyses to support geographic expansion or reshoring decisions.
How Executives Should Use This Intelligence in 2026
-
Procurement: Shift from unit-price negotiation to total-cost-of-supply conversations. Use the study’s scenario models to quantify the impact of supply disruptions and environmental compliance costs on all major suppliers.
-
Product Development and Engineering: Re-evaluate material specifications with lifecycle and manufacturability criteria. The report’s comparative frameworks help identify application areas where gray iron remains the superior choice versus competing materials.
-
Foundry Operators: Prioritize investments that enhance both product quality and compliance. The study’s modernization playbook sets out the operational levers that deliver the quickest and most durable ROI.
-
Corporate Strategy and M&A Teams: Use the competitive analysis and concentration insights to identify attractive targets — whether that is scale to access higher-margin OEM contracts or niche specialists to broaden service offerings.
-
Investors and Lenders: The report provides risk-adjusted cash flow scenarios and stress tests to inform capital allocation, covenant structure, and valuation models in a sector where capital intensity and environmental risk intersect.
Risk Factors and Blind Spots to Watch
-
Input-price volatility driven by scrap metal flows or sudden logistic constraints remains a primary margin risk.
-
Regulatory divergence across markets can create stranded-cost issues if capital investments are not aligned with the most demanding standards.
-
Technological disruption in competing materials or manufacturing methods could compress demand in specific subsegments faster than broad market signals suggest.
Conclusion — The Strategic Value of This Study
For 2026 planning, the gray iron castings market is neither a commodity story nor a static legacy sector; it is an industry in transition. PW Consulting’s report equips decision-makers with both a clear baseline — including a robust forecast aligned with a 4.2% CAGR over the 2026–2032 period — and the operational tools to act on that baseline. We present actionable playbooks, scenario-tested financials, and a nuanced competitor map that highlights where scale, technical capability, and compliance intersect to create value.
This preview deliberately showcases the report’s analytical depth while reserving granular segment-level tables and proprietary modeling outputs for the full study. To access the complete dataset, detailed regional and application segmentation, and customizable models for board-level and commercial teams, please visit our report page and download the full Gray Iron Castings Market study.
For detailed analysis of this topic, please visit the official page: Gray Iron Castings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Illite Market 2026 Strategic Brief: Navigating Growth, Supply Risk, and High‑Value Applications
Executive snapshot
As companies prepare strategic decisions for 2026, the illite market is entering a phase characterized by steady expansion, selective premiumization and evolving supply‑chain risk. Our PW Consulting Illite Market study — built on a 2020–2025 historical base and a 2026–2032 forecast horizon — projects clear, actionable inflection points for procurement leaders, product strategists, and corporate development teams. The global market has expanded consistently during the historical window and, under our baseline projection, continues on a multiyear growth path driven by higher‑value industrial applications and disciplined downstream adoption. Over the forecast period, the market trajectory corresponds to a compound annual growth rate of 6.98% — a pace that supports prioritized investment but that also exposes firms to concentration and regulatory vectors that will shape winners and laggards.
Illite Market
Why 2026 is a decisive year
-
Base‑year calibration: 2025 serves as the analytical base year in our study, reflecting the most recent structural shifts in supply, demand and policy.
Illite Market -
Transition to premium applications: Illite’s role is evolving beyond commodity filler uses toward higher‑margin segments where surface treatment, particle engineering and trace impurity control materially impact value capture.
Illite Market -
Policy and trade inflection points: Multiple regulatory drivers — from tariff regimes to evolving waste shipment rules and export controls — are reshaping the economics and resilience requirements of global procurement strategies.
Market trajectory — a concise data view
Under the baseline forecast, the global illite market grows from a mid‑hundreds USD million scale in 2025 and reaches several hundreds of millions by the end of the 2026–2032 horizon. The forecast incorporates macro demand catalysts in electronics, specialty coatings and advanced manufacturing, and assumes continued industrial recovery across key end markets. The 6.98% CAGR we report for the forecast period signals a market that is attractive for targeted capacity expansion and premium product development, while remaining sensitive to shifts in upstream supply composition and trade policy.
What the PW Consulting report contains (practical, actionable deliverables)
-
High‑resolution forecasting: Granular, scenario‑based projections across our forecast horizon with bottoms‑up demand drivers, sensitivity ranges and clear assumptions — designed to be plugged directly into investment and procurement models.
-
Commercial playbooks: Go‑to market and pricing frameworks for manufacturers and distributors that map product attributes (purity, micronization, surface treatment) to achievable margin tiers and channel strategies.
-
Supply‑chain mapping: A proprietary supplier map and tiering model that identifies sourcing risk nodes, near‑term capacity constraints, and logistical choke points — coupled with tactical levers for resilience (dual sourcing, geographic hedging, and strategic inventory).
-
Regulatory impact matrix: Practical assessments of tariffs, waste shipment rules and export controls, with scenario playbooks that translate regulatory moves into procurement, compliance and contract strategies.
-
M&A and partnership guidance: Screening criteria for target selection, valuation sensitivity to feedstock quality and processing prowess, and integration checklists for bolt‑on and capability acquisitions.
-
Technical appendix: Evaluation protocols for product qualification in sensitive end uses (e.g., electronics and cosmetics), including recommended test methods and acceptance thresholds to accelerate qualification cycles.
Competitive landscape — who to watch
The illite sector remains fragmented at the producer level with a modest level of concentration among larger suppliers. Our competitive analysis focuses on a mix of vertically integrated miners, regional specialists and value‑added processors. Notable players covered in the study include:
-
Chengde Rehe Mining (Chengde, Hebei Province, China) — Primary producer and processor offering natural illite ore and powder products across industrial, cosmetic and feed applications. Website: http://blcitu.com.cn
-
Yonggung Illite (Yonggung, South Korea) — Specialist producer focused on high‑purity grades tailored for coatings, rubber and plastics.
-
Sunwoo Illite (South Korea) — Manufacturer and distributor supplying mineral products across multiple industrial sectors with regional distribution strength.
-
Guangzhou Teamgo (Guangzhou, Guangdong Province, China) — Supplier of illite powders and related mineral products under the Teamgo brand. Website: http://www.teamgo.com.cn/
-
Lingshou County Antai Mining (Lingshou County, Hebei Province, China) — Producer of mica powders and illite‑based products offering full‑service capabilities. Website: http://www.antaiky.com
-
Chifeng Hengyuan Mineral (Chifeng, Inner Mongolia, China) — Active supplier of mineral products for industrial applications.
-
Hebei Jing Hang Mineral (Shijiazhuang, Hebei Province, China) — Producer of mineral powders including illite. Website: http://jinghangkc.cn
-
Micron Solutions (United States) — Supplier of micronized mineral products, including illite, for specialty applications. Website: www.micronsolutions.com
Market concentration metrics in our analysis show a low to moderate aggregation at the top (CR3 and CR5 measures are included in the report), indicating ample room for consolidation and premium differentiation — but also signaling potential supply consolidation risks for buyers focused on narrow specifications.
Recent market moves and why they matter
-
Product innovation: Several companies have launched surface‑modified or eco‑engineered illite variants that enable new performance claims in coatings and UV resistance — accelerating upstream requirements for suppliers to offer treated powders rather than raw ore.
- M&A and capacity shifts: Acquisition activity and capacity expansions targeted at premium, high‑purity powders are reshaping the supply map for pharmaceutical and cosmetic customers; such moves materially shorten qualification timelines for vertically integrated buyers.
- Regional production strategies: Mining expansions in Southeast Asia and new proprietary synthetic processes in Europe are diversifying the sources available to sensitive end users and changing freight and inventory calculus for global buyers.
Strategic implications for 2026 decision‑makers
-
Procurement: Move from spot sourcing to a tiered contracting model. Secure continuity with framework agreements that include quality gates and escalation mechanisms tied to surface‑treatment capabilities. Incorporate lead‑time premiums and clause templates for regulatory shocks.
-
Product development: Prioritize qualification of surface‑modified and micronized variants for higher‑margin applications. Small chemistry and formulation teams can unlock disproportionate value by co‑designing illite grades with suppliers.
-
Investment and M&A: Target assets that combine feedstock access with downstream processing (micronization, surface modification). Our financial models show that control over the value‑added processing step materially compresses time‑to‑market for premium product lines.
-
Regulatory posture: Build an early warning and contractual compliance playbook for tariff and export‑control scenarios. The EU waste shipment rules and evolving export regimes require preemptive reengineering of logistics and vendor qualification workflows.
-
Risk management: Quantify single‑point failures at the supplier and logistics level. Scenario exercises in the report translate supply disruption probabilities into inventory buffer and multi‑sourcing thresholds commensurate with application criticality.
Risk scenarios — what we model and how to use it
Our scenario suite models three pathways: base (steady growth at the reported CAGR), conservative (downside shocks from trade measures and demand softening) and accelerated premiumization (stronger adoption in electronics and cosmetics). For each scenario we provide procurement actions, capex triggers, and KPI dashboards that executives can adopt within 30–60 days to align budgets and contracts with likely outcomes.
How to use the full report
-
For procurement leaders: deploy the supplier map and resilience playbook to renegotiate tiered contracts and set certification milestones.
-
For product teams: use the technical appendix and qualification checklists to cut pilot cycles and reduce time‑to‑revenue for new formulations.
-
For strategy and M&A teams: the valuation sensitivity annex and target screening matrices support rapid target prioritization and fast‑track due diligence.
Final note — the trailer principle
This brief surfaces the analytical backbone and strategic recommendations from PW Consulting’s Illite Market study while intentionally withholding specific segment splits and proprietary tables from this preview. The full report contains the detailed regional and application breakdowns, supplier scorecards, transaction comparables, and downloadable forecast models that will allow your team to operationalize the insights above. If you are preparing sourcing, product or investment decisions for 2026, the full analysis will supply the exact figures, supplier rankings and contractual templates needed to move from strategy to execution.
To access the complete study, models and interactive supplier map, visit PW Consulting’s Illite Market page or contact our industry desk for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Illite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Camera Module Adhesives Market to Reach USD 523.27 Million in 2025
By pmarketresearch, 2026-07-13
Camera Module Adhesives Market — Strategic Preview for 2026 Decision-Makers
As companies calibrate strategies for 2026, the camera module adhesives market presents a distinct mix of steady growth, regulatory pressure and technology-driven product differentiation. PW Consulting’s forthcoming in-depth study (base year 2025; historical window 2020–2025; forecast 2026–2032) synthesizes primary research, cost and formulation analytics, and competitive intelligence to give procurement, R&D and corporate development leaders an operational roadmap for near-term and medium-term choices.
Camera Module Adhesives Market
Why this market matters in 2026
-
Durable, low-defect optical assemblies remain a gating factor for smartphone cameras, advanced ADAS/automotive cameras, and a widening set of industrial and medical imaging modules.
Camera Module Adhesives Market -
After five years of steady expansion, the overall market shows a clear upward trajectory — reflecting both higher per-module adhesive performance requirements and incremental unit demand from new end-markets. PW Consulting’s topline model pegs the global market at USD 523.3 Million in 2025, with a compound annual growth rate of 6.9% through the 2026–2032 forecast horizon.
Camera Module Adhesives Market -
The combination of material innovation (low-shrink, dual-cure chemistries), process acceleration (active alignment workflows), and regulatory reformulation (VOC limits, REACH/RoHS compliance) creates simultaneous risk and opportunity for material suppliers and OEMs.
What the 2026 strategist needs to know — high-level takeaways
-
Growth is predictable but selective: the market trajectory is upward and resilient to short-term end-market shocks, yet value accrues unevenly — premium formulations that enable higher throughput and reduced rework capture disproportionate margin.
-
Competitive positioning hinges on technical depth: suppliers that combine formulation expertise (UV/dual-cure, low-temperature systems) with application engineering for active alignment win design wins and lock in longer-term volume contracts.
-
Regulatory and trade dynamics are non-negotiable inputs: compliance and supply-chain locality will influence cost curves and customer selection criteria in 2026 more strongly than in prior cycles.
-
Market concentration is meaningful but not monopolistic: top suppliers account for a material share of global revenues, leaving room for differentiated entrants leveraging niche chemistries or service-led commercialization models.
How PW Consulting’s study helps executives make decisions in 2026
-
Prioritize capital allocation: our scenario-driven market sizing (base year 2025) and 6.9% CAGR projection enable CFOs to stress-test investment cases for capacity expansion, pilot R&D, or M&A.
-
Design procurement strategy: we map supply risk against tariff exposures and raw-material sourcing constraints, letting sourcing teams weigh localization versus global sourcing and identify near-term hedging priorities.
-
Inform product roadmap choices: R&D leaders receive a taxonomy of adhesive attributes with quantified performance trade-offs (cure speed vs. shrinkage vs. thermal stability) and suggested go/no-go thresholds for automotive-grade qualification.
-
Shape commercial tactics: the report translates technical differentials into commercial levers — value-based pricing, bundling of application engineering services, and warranty structures aligned to customers’ yield improvement targets.
What’s inside the report — actionable, practice-oriented content
-
Market model and scenarios: a base-case and two alternative scenarios through 2032, with sensitivity testing on unit mix, ASP trends, and regulatory cost pass-through assumptions.
-
Cost and formulation deep dives: bill-of-materials templates, margin waterfall analyses, and estimated incremental cost of compliance for reformulation to VOC/REACH/RoHS standards.
-
Supplier scorecards and heatmaps: qualitative and quantitative assessments across technical capability, scale, geographic footprint, regulatory readiness and partnering posture.
-
Competitive playbooks: battle-tested commercial strategies for suppliers and OEMs — from rapid qualification pilots to locked-in supply contracts with tiered pricing tied to yield metrics.
-
Regulatory risk matrix and compliance roadmap: actionable steps to adapt formulations, documentation and supply-chain traceability to meet EU General Safety Regulation, REACH, RoHS and other regional requirements.
-
Go-to-market templates for new chemistries: recommended pilot designs, qualification milestones, and OEE improvement KPIs to accelerate adoption in both consumer and automotive channels.
Competitive landscape — what to watch in 2026
-
Supplier differentiation is rooted in both chemistry and service. Market leaders maintain portfolios that span light-curable epoxies, dual-cure systems and low-temperature UV formulations — enabling them to support active alignment workflows and heat-sensitive assemblies.
-
Representative players earning strategic mentions in our analysis include established names with distinct advantages: a US-based innovator with strength in light-curable optical epoxies and recent product introductions focused on low-shrink active alignment; Japanese specialists with depth in insulating and camera-module adhesives tailored to fixed- and autofocus modules; German firms advancing dual-cure and UV systems for first-lens bonding in demanding environments; and legacy formulators offering low-temperature, UV-cure chemistries for sensitive assemblies.
-
Recent corporate actions signal tactical plays to watch: a lease renewal underscored a US supplier’s commitment to local operations (July 2025); a German adhesive manufacturer launched new dual-cure and UV products optimized for first-lens bonding (January 2026); and another US innovator announced a next-generation low-shrink active-alignment epoxy (May 2026). These moves illustrate a two-track dynamic — supply-side investments in both innovation and operational stability.
Regulatory, tariff and supply-chain factors shaping 2026 strategy
-
Regulatory tightening: the EU’s General Safety Regulation (effective July 2024) and ongoing REACH/RoHS enforcement accelerate reformulation and documentation requirements. Firms that front-load compliance see shorter qualification cycles with conservative automotive customers.
-
Tariff-driven cost recalibration: elevated duties on imported specialty resins and curing agents introduced in 2025 (notably in the US) are reshaping vendor selection and prompting some buyers to pursue near-shoring, dual sourcing, or qualified domestic alternatives.
-
Labor and compliance expense pressure: transforming solvent-based products into compliant low-VOC formulations increases both direct reformulation costs and indirect labor/compliance overhead — an input we explicitly model in supplier margin scenarios.
Strategic playbook — recommended actions for 2026
-
For OEMs and integrators: lock in design-win roadmaps tied to adhesive performance payoffs (throughput, yield, reliability). Negotiate performance-based supply agreements that share upside from yield improvements and protect against raw-material cost spikes.
-
For suppliers: prioritize modular go-to-market offers — combine differentiated chemistries with application engineering and qualification accelerators. Invest selectively in capacity where regulatory-favored geographies and customer clusters justify capital spend.
-
For investors and M&A teams: target assets that bring either scarce chemistries (e.g., fast-curing, low-shrink epoxies) or embedded application engineering relationships with OEMs; use PW Consulting’s supplier scorecards and concentration metrics to refine target lists and valuation assumptions.
-
Cross-cutting: build a regulatory-control tower to track REACH/RoHS/General Safety updates and to operationalize rapid reformulation pathways — this reduces time-to-market for compliant variants and limits revenue exposure from sudden regulatory enforcement.
Why PW Consulting’s intelligence is different
-
Integrated engineering-commercial lens: we marry lab-validated performance trade-off curves with commercial pricing and warranty constructs so teams can translate chemical improvements into wallet-share gains.
-
Actionable templates: rather than only high-level forecasting, the study includes supplier scorecards, cost build-up models and qualification playbooks ready to be adapted by procurement, R&D and BD teams.
-
Proven scenario methodology: our base case (anchored to 2025 data) and 6.9% CAGR forecast extends to 2032 and includes tailored downside/upside paths that reflect tariff shocks, rapid re-platforming to new module architectures, or sudden regulatory tightening.
Next step — where to find the missing details
This preview sketches the strategic contours that will determine winners and laggards through 2026. For confidentiality and clarity, this article intentionally omits granular regional and application split details that are included in the full study — data that executives rely on to justify capital projects, contract negotiations and M&A bids. Access to the complete PW Consulting Camera Module Adhesives Market report provides the full quantitative breakdowns, supplier-level scorecards, and downloadable scenario models that operational teams use to execute decisions with confidence.
Contact PW Consulting to obtain the complete report, request bespoke modeling for your product portfolio, or schedule a strategic briefing tailored to your role (procurement, R&D, corporate development). In a market growing from a mid-single-digit base into the early 2030s with a 6.9% CAGR, the difference between leading and lagging strategies will be set by how teams translate material science into predictable manufacturing and commercial advantage.
For detailed analysis of this topic, please visit the official page: Camera Module Adhesives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vapor Chamber Market to Reach USD 5,790 Million by 2032 at 10.5% CAGR
By pmarketresearch, 2026-07-13
Vapor Chamber Market: Strategic Briefing for 2026 — Why This Study Will Shape Your Next Move
Executive snapshot
By 2025 the global vapor chamber market reached roughly USD 2,990 Million (base year: 2025). Our model projects a sustained compound annual growth rate (CAGR) of approximately 10.5% through the forecast window, positioning the market north of USD 5.7 Billion by 2032. For corporate leaders making capital allocation, product and supply-chain choices in 2026, this study is designed to translate that headline expansion into actionable priorities — without burying you in raw tables. Consider this article a trailer: it demonstrates the depth and practical orientation of the full PW Consulting analysis while preserving critical, high-value segmentation and unit-level intelligence for the full report access.
Vapor Chamber Market
Why 2026 is a strategic inflection point
- Demand geometry: Multiple end-markets (consumer electronics, data centers, automotive, aerospace, healthcare and industrial) are converging on higher thermal-performance requirements. This is no longer a niche heat-spreading technology: vapor chambers are moving from optional performance uplift to required enablers in designs constrained by power density and form factor.
- Supply-side transformation: Capacity investments and new product families introduced in late 2025–mid 2026 are materially reshaping manufacturing economics. Some suppliers have already announced multi-fold capacity expansions targeted at AI/ASIC and server cooling segments, tilting supplier bargaining power and time-to-market dynamics.
- Input-cost volatility and policy risk: The commodity cycle and trade policy interventions in 2025–2026 have amplified input-cost and sourcing risk for copper-heavy assemblies, requiring procurement playbooks that marry hedging, alternate material strategies, and nearshoring considerations.
What the PW Consulting study delivers (practical, transaction-ready intelligence)
This research goes beyond market-sizing and trend narration. It is a practitioner’s dossier for executives and deal teams preparing to compete or invest in vapor chamber value chains in 2026:
Vapor Chamber Market
- Investment-grade TAM and demand scenarios: base, upside and stress cases that reconcile end-market unit trajectories with thermal design adoption curves.
- Driver-based cost model: factory-level cost build-ups, sensitivity to copper and PCM inputs, labor and automation levers — stated as templates you can apply to your own BOMs (modeling worksheets included in the full deliverable).
- Supplier scorecards and capacity maps: production footprints, lead-time risk hot spots, and a dynamic supplier risk index calibrated for 2026 supply shocks.
- Product and IP segmentation playbook: how to prioritize standard, ultra-thin and embedded vapor chamber portfolios against OEM qualification cycles and regulatory constraints.
- Regulatory and qualification navigator: checklists and timelines for AEC-Q100, IATF 16949, ISO 13485 and other customer/OEM certification gates that commonly extend project timelines by 12–36 months.
- M&A and partnership playbook: valuation heuristics, bolt-on targets, JV structures and earn-out frameworks for consolidators and strategic buyers.
- Go-to-market tactical templates: OEM engagement sequences, design-win timelines, and pricing strategies for high-power vs. form-factor-sensitive segments.
Market dynamics that matter in 2026
The market’s macro trajectory is robust: with a mid-teens-ish expansion in absolute dollars expected over the forecast period, firms that move early to secure design wins and scale will capture asymmetric value. Key dynamics we explore in the report include:
Vapor Chamber Market
- Thermal performance ceilings: advances in vapor chamber geometry, wicking and ultra-thin manufacturing mean thermal solutions are being specified for power densities previously reserved for active liquid cooling. This drives differentiated product tiers and margin dispersion.
- Qualification and time-to-revenue friction: OEM qualification standards in automotive and medical markets (AEC-Q100, IATF 16949, ISO 13485) impose long lead-times and high test burdens; our analysis quantifies the typical investment and calendar impact per market.
- Commodity and trade-policy shock scenarios: 2025–2026 saw record copper price pressure and tariff actions that materially increased producers’ cost-of-goods and reshuffled cost-competitive geographies. The full report models several mitigations — from alloy substitution and plating strategies to procurement hedging and supplier diversification.
- Concentration and competitive structure: the vapor chamber market displays a low-to-moderate concentration structure; major incumbents collectively control a minority share, leaving room for niche specialists and high-volume OEM suppliers to expand through both organic and inorganic routes.
Competitive landscape — what you need to know now
Our competitive analysis synthesizes corporate positioning, product breadth, capability gaps and near-term strategic moves across the vendor ecosystem. Highlights include:
- Strategic capacity builders: Several Taiwanese and regional manufacturers have accelerated capacity additions aimed at AI-server, GPU and high-power compute segments. These moves materially change lead-time and scale economics for large OEM contracts.
- Product breadth and specialization: Market players differentiate on thickness (standard vs. ultra-thin), embedded designs, and integrated thermal-module solutions for specific end-markets (e.g., AI servers, foldable consumer devices, automotive power modules). Companies that bundle vapor chambers with thermal modules and system-level engineering services extract higher margin capture and longer-term customer stickiness.
- North-south technology transfer and cost arbitrage: Chinese manufacturers are increasingly competitive on 3D and thin-form vapor chambers, while US and Taiwanese firms emphasize integrated engineering services, IP protection and quality systems favored by tier-1 OEMs.
- Notable corporate developments: Recent public disclosures in early-to-mid 2026 show capacity buildouts, new high-spec product introductions and design guidance updates that together accelerate adoption for high-power applications. These are tracked in a dedicated timeline within the full report.
Regulatory, procurement and raw-material risk — practical implications
Regulatory compliance is not just a certification checkbox: it materially affects time-to-revenue and cost. Automotive- and medical-grade vapor chambers require rigorous qualification and test matrices, which our fieldwork shows commonly extend project schedules and necessitate capitalized testing budgets.
On the procurement side, record-level copper dynamics and tariff moves in mid-2025–2026 elevated raw-material cost exposure. Effective procurement strategies we model include dual-sourcing, long-term offtakes with indexation clauses, and selective pass-through pricing in OEM contracts. The report includes scenario outputs showing the P&L sensitivity of these strategies under different commodity and tariff shocks.
High-conviction plays for 2026
- Secure early design wins in high-growth, high-ASP segments (AI, data-center accelerators) where cycle-times compress margins less than consumer product channels.
- Invest in thin/embedded process IP or partner with a specialist — thin-form factor wins are conversion barriers that justify price premiums in handheld and mobile applications.
- Rebalance the supply chain: diversify sourcing of critical copper inputs and qualify geographically distinct contract manufacturers to mitigate tariff and logistics risk.
- Structure OEM contracts to share upstream commodity exposure and align incentives for scale: include step-up pricing bands and volume rebates tied to validated design wins.
- Prepare regulatory roadmaps early for automotive and medical programs to avoid late-stage rework that erodes margin and time-to-market.
Why PW Consulting’s vapor chamber study is different
We combine primary vendor interviews, factory tours, BOM-level cost models and OEM qualification-path mappings to produce an actionable blueprint. Instead of generic slices of demand by region and application, we translate market momentum into decision-support tools: scenario P&Ls, supplier risk indices, investment timelines and M&A targets prioritized by strategic fit and time-to-value.
How to use this briefing in 2026 strategic planning
- Board-level budgeting: use our downside and upside scenarios to stress capital plans and to set guardrails for capacity additions.
- Corporate development teams: prioritize M&A targets using our valuation premia that reflect IP ownership, design-win stickiness, and supplier footprint.
- Product and engineering leaders: adopt the report’s technology roadmap to align product launches with the OEM qualification cadence.
- Procurement and operations: implement the tactical sourcing and hedging templates to reduce COGS volatility and ensure continuity of supply during peak ramp periods.
Next steps — where to get the full playbook
This article intentionally omits proprietary segmentation matrices and unit-level forecasts that form the highest-value outputs in our research — these are available in the full PW Consulting Vapor Chamber Market report. The full deliverable contains detailed regional and application splits, supplier-by-supplier competitive scorecards, factory economics, and downloadable financial models designed for integration with your own planning systems.
For leadership teams prioritizing decisive action in 2026, this report is both a radar and a road-map: it identifies where the next design-wins and scale economies will appear, and it prescribes the commercial, operational and financial playbooks to capture them.
For detailed analysis of this topic, please visit the official page: Vapor Chamber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Interior Stain Market to Reach USD 1,304.48M by 2032 at 5.5% CAGR
By pmarketresearch, 2026-07-13
Interior Stain Market 2026: Strategic Imperatives from PW Consulting
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present an executive preview of our latest Interior Stain Market study — a practical, decision-grade briefing designed to shape corporate strategy in 2026. This “trailer” surfaces the research framework, strategic conclusions, and the tactical levers leaders must consider, while preserving the granular subsegment tables and scenario-by-scenario datasets for the full report. Our objective here is to demonstrate the study’s immediate value for boardrooms and commercial teams preparing budgets, R&D roadmaps, and M&A priorities for the coming planning cycle.
Interior Stain Market
Why this study matters for 2026 decision-makers
The interior stain market reached approximately USD 897 million (base year 2025) and, under the baseline scenario modeled in this research, grows at a compound annual growth rate (CAGR) of 5.5% through our forecasting horizon. That trajectory reflects a market moving from a traditional commodity posture toward differentiated finishes driven by sustainability compliance, formulation innovation, and changing channel economics. For executives building 2026 plans, these macro parameters mean two things: aggregate demand is healthy and predictable enough to justify targeted investment, but value capture will increasingly depend on strategic positioning — not simply volume growth.
Interior Stain Market
High-level dynamics shaping strategy
- Regulatory and formulation shifts: Indoor air-quality rules and voluntary certification programs are accelerating adoption of low-VOC and PFAS-free formulations. Early movers that align product portfolios with 250-VOC-equivalency performance and transparent chemical disclosures are capturing premium placement in both pro and retail channels.
- Raw material volatility: Resin, solvent and pigment inputs remain the dominant cost escape hatch. Price swings materially affect margins and require active hedging, dynamic pricing, and supplier diversification strategies to preserve profitability.
- Channel bifurcation: Professional contractors continue to demand high-performance, fast-dry systems and specification support; consumer demand leans toward DIY-friendly, color-rich assortments and digital visualization tools. Companies that serve both audiences with tailored go-to-market models gain share faster than single-channel players.
- Concentration and competitive positioning: The market exhibits a moderate level of concentration (CR3 and CR5 indicators in the study confirm clear national leaders while leaving room for regional specialists and challenger brands). This structure enables both scale-driven cost advantages and targeted disruption by agile niche players.
What the full PW Consulting report delivers (operationally focused)
Our full study is built for immediate translation into operating plans. Key deliverables include:
Interior Stain Market
- Robust market-sizing and a transparent forecasting model (2026–2032) with adjustable scenario knobs for input-cost shocks, regulatory tightening, and channel share shifts.
- Segment-level demand drivers and a prioritized list of white-space opportunities for product extensions and color assortments (granular tables and elasticities are reserved for the full report).
- Actionable competitor scorecards with capabilities maps, distribution footprints, and strategic playbooks you can adapt for acquisition diligence or partnership evaluation.
- Price-to-margin sensitivity matrix and a raw-material pass-through tool to simulate P&L impacts under volatile input scenarios.
- Regulatory risk assessment and compliance playbook mapping formulation changes to specific commercial actions (labeling, certification, and claims management).
- Retail assortment and pro-channel shelf-space optimization guides plus digital-sell-through experiment results to accelerate omnichannel conversion.
- M&A and partnership screening framework that identifies targets by capability gaps, geographic fit, and potential synergies.
Because we recognize commercial teams need executable steps, each analytical module concludes with a recommended 90/180/365 day plan tailored to growth, margin-defense, or acquisition-led strategies.
Competitive landscape—strategic takeaways
Our market mapping highlights a mix of national brand leaders and focused specialists, each building distinct defenses and growth engines:
- Minwax (Brewster, NY) remains a prominent household and pro brand, leveraging an extensive color portfolio and strong retail distribution. Recent maneuvers — including a 2026 Color of the Year announcement and a targeted product launch in late 2025 — demonstrate the power of color marketing to influence assortment resets and seasonal purchase cycles.
- Behr (Santa Ana, CA) continues to emphasize hybrid performance lines (fast-dry and poly-in-one formulations) that appeal across pro and DIY segments, anchoring premium shelf positions in major home improvement chains.
- General Finishes (Minnesota) showcases a sustainability-oriented playbook, pushing low-VOC and PFAS-free water-based stains aimed at specification buyers and eco-conscious consumers — a posture that supports margin premiums where certification matters.
- ZAR , Varathane , Cabot and other established names maintain broad product portfolios and deep channel relationships; their competitive advantages are built on distribution scale, brand recognition, and technical support networks.
- Specialists such as Perma-Chink Systems and Sansin demonstrate how focused product fit (e.g., log-home finishes, nano-tint technologies) creates defensible niches with high loyalty and lower price elasticity.
Collectively, competitors are investing in three strategic vectors: formulation modernization (low-VOC, PFAS elimination), sensory and visual differentiation (expanded color libraries and tint systems), and route-to-market sophistication (digital tools, pro-services, and omnichannel merchandising). These are the axes on which 2026 battles will be fought.
Tactical actions executives should prioritize in 2026
- Run a rapid portfolio audit: rationalize slow-moving SKUs, prioritize low-VOC water-based reformulations for high-visibility segments, and reallocate marketing spend to color and finish storytelling.
- Implement an input-cost hedging policy and a dynamic pricing cadence to protect margin while maintaining competitive shelf prices.
- Accelerate partnerships with retailers on exclusive color launches and co-marketing for in-store sampling and digital visualization tools to increase conversion rates.
- Invest in certification and transparent ingredient disclosures to capture premium placement with architects, interior designers, and environmentally conscious consumers.
- Build a modular M&A playbook focused on acquiring formulation IP, tinting technology, or regional distribution that can be rapidly integrated into existing channels.
Risk monitoring and leading indicators
Effective planning depends on an early-warning dashboard. Key indicators we recommend monitoring weekly to quarterly include:
- Feedstock price indices for key resin, solvent and pigment families.
- Regulatory activity in major markets (VOC thresholds, PFAS restrictions, indoor air-quality standards).
- Retail sell-through and inventory days on key SKUs post-color-launch events.
- Professional contractor procurement trends and specification shifts toward water-based systems.
- Online search and social media signals for color trends and DIY interest spikes.
Closing—how this preview converts to competitive advantage
In markets transitioning from volume to value, the combination of rigorous forecasting, competitively aware product strategy, and operational resilience wins. Our Interior Stain Market study packages those capabilities into a single reproducible framework: validated forecasts, executable go-to-market plays, and the diagnostic tools needed to manage downside scenarios. For leadership teams constructing 2026 budgets, the study not only quantifies opportunity but prescribes where to invest for differentiated returns.
The granular segment splits, SKU-level elasticities, and transaction-level channel data that underpin our recommendations are excluded from this preview but included in the full PW Consulting deliverable. For access to the complete dataset, interactive models, and a tailored strategic workshop, please consult the full report and our advisory team.
For detailed analysis of this topic, please visit the official page: Interior Stain Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fire-Resistant Hydraulic Fluids Market to Reach USD 200.62M by 2032 at 3.9% CAGR
By pmarketresearch, 2026-07-13
Fire Resistant Hydraulic Fluids Market 2026: Strategic Briefing for Executive Decision‑Makers
As companies set strategy for 2026 in heavy industry, steel mills, aerospace, and capital‑intensive process plants, the choice of hydraulic fluids — and the suppliers who provide them — has shifted from an operational detail to a source of competitive risk and opportunity. PW Consulting’s latest market study, based on a 2025 base year and a 2026–2032 forecast horizon, synthesizes technical, regulatory and commercial signals firms must act on now. The global market has expanded from roughly USD 130 million in 2020 to USD 155 million in 2025 and is projected to reach about USD 200.6 million by 2032, growing at a 3.9% CAGR. This steady, structurally driven growth underscores that incremental improvements in fluid selection, procurement strategy and supplier collaboration can yield outsized benefits for uptime, safety and total cost of ownership.
Fire Resistant Hydraulic Fluids Market
What this briefing delivers for decisions in 2026
- Sensitivity to regulatory shifts: New and updated standards (notably ISO 12922 and approvals referenced by major OEMs) are raising minimum performance baselines for oxidation stability, water content control and fire performance. Manufacturers must align product roadmaps and procurement specifications to avoid retrofit costs.
- Supply‑chain resilience planning: Raw material volatility (recent oxo‑chemical price jumps and regional feedstock disruptions) is creating short‑term margin pressure. Our study maps exposure across chemistries and recommends hedging and supplier concentration strategies.
- M&A and portfolio alignment: Market concentration is meaningful — leading suppliers hold a large share of demand — which makes inorganic moves and bolt‑on acquisitions an accelerating way to secure channel access and technology. We profile recent strategic transactions and their operational implications.
- Performance versus cost tradeoffs: Comparative lifecycle analyses in the report quantify when higher‑cost phosphate‑ester or synthetic‑ester products deliver better plant‑level economics through reduced fire risk, longer oil life and fewer maintenance interventions.
Report composition — actionable modules
- Market sizing and trend decomposition (2020–2025 historical, 2026–2032 forecast) with scenario pathways reflecting regulatory tightening and raw‑material shocks.
- Supply‑side intelligence: supplier scorecards, approval portfolios (FM, OEMs), technical performance matrices and fit‑for‑application routing by pressure, temperature and contamination risk.
- Cost modelling: feedstock price pass‑through, lubricant lifecycle costing, and maintenance cost linkages under different degradation and contamination regimes.
- Go‑to‑market playbooks for suppliers and industrial buyers, including contracting templates, inventory strategies and testing protocols to align operations with ISO and OEM requirements.
- Deal pipeline and strategic options: M&A targets, joint‑development partners and licensing routes to accelerate entry into higher‑value aviation and steel applications.
Competitive landscape — what the leading suppliers mean for your strategy
The market demonstrates a balance of scale and technical differentiation. The top three competitors control a substantial portion of market demand and the top five an even larger share, creating a dynamic where scale, approvals and distribution reach matter. At the same time, certification and product performance continue to open windows for regional and specialist entrants.
Fire Resistant Hydraulic Fluids Market
- Quaker Houghton — Known for its QUINTOLUBRIC polyol ester HFD‑U range and water‑glycol offerings, Quaker Houghton combines deep application engineering for steel and metalworking with broad service capabilities. For buyers, this positions them as a pragmatic partner for large‑scale, site‑level conversions and long‑term lubricant management agreements.
- Shell — Shell’s industrial lubricants group emphasizes formulations that limit flame propagation and ignition hazards. Their global logistics and OEM relationships make them a logical play for multinational operators seeking harmonized specifications across locations.
- CITGO Petroleum Corporation — With product lines tailored to high‑pressure steel mill and die‑casting systems, CITGO illustrates how regional scale combined with application focus can win specialized tenders where service and inventory responsiveness matter.
- Q8Oils — Q8’s ester‑based HFDU products with recognized approvals appeal to operators prioritizing high flash points and specific plant safety standards. Their positioning is an example of using technical credentialing to gain share in heavy industrial accounts.
- FUCHS — Active expansion by acquisition has broadened FUCHS’ product portfolio in the fire‑resistant segment. Their strategy underscores the role of M&A in building capability quickly — a relevant consideration for private‑equity‑backed entrants and strategic buyers alike.
- Houghton International — Houghton’s recent technical literature and application‑specific formulations signal a push to reinforce customer engineering support, making them a compelling partner for conversion projects and technical trials.
Recent strategic moves and market signals
- Acquisitions and capital moves: Consolidation activity, including portfolio add‑ons by established lubricant houses and private capital interest in major brands, shows acquirers are betting on the adjacent industrial‑fluids economics and the premium nature of fire‑resistant products.
- Certification and OEM acceptance: National airworthiness approvals and OEM lists are reshaping competition for aerospace and aviation applications — winning an airworthiness or OEM stamp of approval can drive rapid adoption in high‑value segments.
- Material and capacity trends: Price spikes in oxo‑intermediates and announced capacity expansions for phosphate‑ester intermediates create both risk and opportunity: short‑term cost pressure versus longer‑term supply security for vertically integrated players.
- Standards and procurement: ISO 12922 updates, and their adoption by environmental and procurement frameworks, mean buyers will increasingly specify measurable oxidation and water‑content metrics at tender stage — turning lab performance into a commercial requirement.
Dynamics that will drive supplier selection in 2026
Three dynamics will dominate procurement and product strategy this year:
Fire Resistant Hydraulic Fluids Market
- Regulatory and OEM alignment: Conformance to updated testing and measurement methods is non‑negotiable for access to major accounts and green procurement frameworks.
- Cost and availability of intermediates: Feedstock price volatility mandates flexible contracting, inventory buffers and multiple qualified suppliers to limit production interruptions.
- Supplier engineering capability: The ability to deliver application‑specific formulations, supported by field trials and documented lifecycle performance, is becoming as important as price in long‑term contracts.
Strategic implications and recommended actions for 2026
- For end‑users (steel, foundry, mining, aerospace): Prioritize qualification of two to three technical suppliers that collectively cover your OEM approval needs and feedstock risk exposure. Implement controlled pilot conversions with joint metrics for fire‑resistance, fluid life and maintenance intervals.
- For lubricant manufacturers: Accelerate certification efforts (national and OEM) where your formulations already meet performance thresholds; consider targeted acquisitions or licensing to fill gaps quickly in key geographies and application verticals.
- For investors and M&A teams: Evaluate targets that combine technical approvals, niche application penetration and downstream service contracts — these asset types de‑risk revenue and create recurring income streams.
- For procurement and supply‑chain leaders: Build feedstock exposure dashboards and include contractual clauses for price pass‑through and allocation priorities during feedstock shortages. Consider dual‑sourcing strategies for ester and water‑glycol chemistries where operational continuity is critical.
Why PW Consulting’s report is strategically valuable in 2026
The study translates market projections (3.9% CAGR through 2032 to roughly USD 200.6 million) into decision‑ready insights: supplier scorecards, approval matrices, cost pass‑through models and scenario playbooks calibrated to both regulatory tightening and raw‑material shocks. It bridges technical performance data with commercial levers — enabling executives to quantify the ROI of conversion projects, the payback for securing OEM approvals, and the tradeoffs of different sourcing strategies.
Importantly, our work follows a “trailer” approach: this briefing demonstrates the analytical depth and commercial relevance of the study while reserving granular segmentation, supplier benchmarking tables and downloadable financial models for the full report. Those core datasets — including detailed type, regional and application breakdowns and supplier‑level pricing curves — are central to bespoke purchasing or investment decisions and are available with the full research package.
Next steps
- Book a 60‑minute briefing with our industry desk to walk through scenario sensitivities and to map the implications for your 2026 procurement and product plans.
- Commission a tailored supplier due‑diligence or conversion pilot, leveraging our technical checklists and lifecycle costing templates from the report.
- Request the full report and Excel models to access the detailed segmentation, supplier scorecards and approval matrices that support executable contracts and investment theses.
In a market where safety, cost and continuity intersect, being proactive in 2026 will determine which companies convert regulatory pressure into competitive advantage. PW Consulting’s Fire Resistant Hydraulic Fluids Market study provides the evidence base and strategic roadmaps to do exactly that. Contact our team to access the full intelligence package and begin operationalizing these insights.
For detailed analysis of this topic, please visit the official page: Fire Resistant Hydraulic Fluids Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com