

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Camera Module Adhesives Market to Reach USD 523.27 Million in 2025

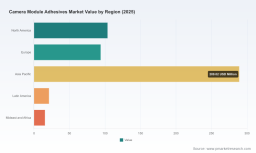
Camera Module Adhesives Market — Strategic Preview for 2026 Decision-Makers
As companies calibrate strategies for 2026, the camera module adhesives market presents a distinct mix of steady growth, regulatory pressure and technology-driven product differentiation. PW Consulting’s forthcoming in-depth study (base year 2025; historical window 2020–2025; forecast 2026–2032) synthesizes primary research, cost and formulation analytics, and competitive intelligence to give procurement, R&D and corporate development leaders an operational roadmap for near-term and medium-term choices.
Camera Module Adhesives Market
Why this market matters in 2026
-
Durable, low-defect optical assemblies remain a gating factor for smartphone cameras, advanced ADAS/automotive cameras, and a widening set of industrial and medical imaging modules.
Camera Module Adhesives Market -
After five years of steady expansion, the overall market shows a clear upward trajectory — reflecting both higher per-module adhesive performance requirements and incremental unit demand from new end-markets. PW Consulting’s topline model pegs the global market at USD 523.3 Million in 2025, with a compound annual growth rate of 6.9% through the 2026–2032 forecast horizon.
Camera Module Adhesives Market -
The combination of material innovation (low-shrink, dual-cure chemistries), process acceleration (active alignment workflows), and regulatory reformulation (VOC limits, REACH/RoHS compliance) creates simultaneous risk and opportunity for material suppliers and OEMs.
What the 2026 strategist needs to know — high-level takeaways
-
Growth is predictable but selective: the market trajectory is upward and resilient to short-term end-market shocks, yet value accrues unevenly — premium formulations that enable higher throughput and reduced rework capture disproportionate margin.
-
Competitive positioning hinges on technical depth: suppliers that combine formulation expertise (UV/dual-cure, low-temperature systems) with application engineering for active alignment win design wins and lock in longer-term volume contracts.
-
Regulatory and trade dynamics are non-negotiable inputs: compliance and supply-chain locality will influence cost curves and customer selection criteria in 2026 more strongly than in prior cycles.
-
Market concentration is meaningful but not monopolistic: top suppliers account for a material share of global revenues, leaving room for differentiated entrants leveraging niche chemistries or service-led commercialization models.
How PW Consulting’s study helps executives make decisions in 2026
-
Prioritize capital allocation: our scenario-driven market sizing (base year 2025) and 6.9% CAGR projection enable CFOs to stress-test investment cases for capacity expansion, pilot R&D, or M&A.
-
Design procurement strategy: we map supply risk against tariff exposures and raw-material sourcing constraints, letting sourcing teams weigh localization versus global sourcing and identify near-term hedging priorities.
-
Inform product roadmap choices: R&D leaders receive a taxonomy of adhesive attributes with quantified performance trade-offs (cure speed vs. shrinkage vs. thermal stability) and suggested go/no-go thresholds for automotive-grade qualification.
-
Shape commercial tactics: the report translates technical differentials into commercial levers — value-based pricing, bundling of application engineering services, and warranty structures aligned to customers’ yield improvement targets.
What’s inside the report — actionable, practice-oriented content
-
Market model and scenarios: a base-case and two alternative scenarios through 2032, with sensitivity testing on unit mix, ASP trends, and regulatory cost pass-through assumptions.
-
Cost and formulation deep dives: bill-of-materials templates, margin waterfall analyses, and estimated incremental cost of compliance for reformulation to VOC/REACH/RoHS standards.
-
Supplier scorecards and heatmaps: qualitative and quantitative assessments across technical capability, scale, geographic footprint, regulatory readiness and partnering posture.
-
Competitive playbooks: battle-tested commercial strategies for suppliers and OEMs — from rapid qualification pilots to locked-in supply contracts with tiered pricing tied to yield metrics.
-
Regulatory risk matrix and compliance roadmap: actionable steps to adapt formulations, documentation and supply-chain traceability to meet EU General Safety Regulation, REACH, RoHS and other regional requirements.
-
Go-to-market templates for new chemistries: recommended pilot designs, qualification milestones, and OEE improvement KPIs to accelerate adoption in both consumer and automotive channels.
Competitive landscape — what to watch in 2026
-
Supplier differentiation is rooted in both chemistry and service. Market leaders maintain portfolios that span light-curable epoxies, dual-cure systems and low-temperature UV formulations — enabling them to support active alignment workflows and heat-sensitive assemblies.
-
Representative players earning strategic mentions in our analysis include established names with distinct advantages: a US-based innovator with strength in light-curable optical epoxies and recent product introductions focused on low-shrink active alignment; Japanese specialists with depth in insulating and camera-module adhesives tailored to fixed- and autofocus modules; German firms advancing dual-cure and UV systems for first-lens bonding in demanding environments; and legacy formulators offering low-temperature, UV-cure chemistries for sensitive assemblies.
-
Recent corporate actions signal tactical plays to watch: a lease renewal underscored a US supplier’s commitment to local operations (July 2025); a German adhesive manufacturer launched new dual-cure and UV products optimized for first-lens bonding (January 2026); and another US innovator announced a next-generation low-shrink active-alignment epoxy (May 2026). These moves illustrate a two-track dynamic — supply-side investments in both innovation and operational stability.
Regulatory, tariff and supply-chain factors shaping 2026 strategy
-
Regulatory tightening: the EU’s General Safety Regulation (effective July 2024) and ongoing REACH/RoHS enforcement accelerate reformulation and documentation requirements. Firms that front-load compliance see shorter qualification cycles with conservative automotive customers.
-
Tariff-driven cost recalibration: elevated duties on imported specialty resins and curing agents introduced in 2025 (notably in the US) are reshaping vendor selection and prompting some buyers to pursue near-shoring, dual sourcing, or qualified domestic alternatives.
-
Labor and compliance expense pressure: transforming solvent-based products into compliant low-VOC formulations increases both direct reformulation costs and indirect labor/compliance overhead — an input we explicitly model in supplier margin scenarios.
Strategic playbook — recommended actions for 2026
-
For OEMs and integrators: lock in design-win roadmaps tied to adhesive performance payoffs (throughput, yield, reliability). Negotiate performance-based supply agreements that share upside from yield improvements and protect against raw-material cost spikes.
-
For suppliers: prioritize modular go-to-market offers — combine differentiated chemistries with application engineering and qualification accelerators. Invest selectively in capacity where regulatory-favored geographies and customer clusters justify capital spend.
-
For investors and M&A teams: target assets that bring either scarce chemistries (e.g., fast-curing, low-shrink epoxies) or embedded application engineering relationships with OEMs; use PW Consulting’s supplier scorecards and concentration metrics to refine target lists and valuation assumptions.
-
Cross-cutting: build a regulatory-control tower to track REACH/RoHS/General Safety updates and to operationalize rapid reformulation pathways — this reduces time-to-market for compliant variants and limits revenue exposure from sudden regulatory enforcement.
Why PW Consulting’s intelligence is different
-
Integrated engineering-commercial lens: we marry lab-validated performance trade-off curves with commercial pricing and warranty constructs so teams can translate chemical improvements into wallet-share gains.
-
Actionable templates: rather than only high-level forecasting, the study includes supplier scorecards, cost build-up models and qualification playbooks ready to be adapted by procurement, R&D and BD teams.
-
Proven scenario methodology: our base case (anchored to 2025 data) and 6.9% CAGR forecast extends to 2032 and includes tailored downside/upside paths that reflect tariff shocks, rapid re-platforming to new module architectures, or sudden regulatory tightening.
Next step — where to find the missing details
This preview sketches the strategic contours that will determine winners and laggards through 2026. For confidentiality and clarity, this article intentionally omits granular regional and application split details that are included in the full study — data that executives rely on to justify capital projects, contract negotiations and M&A bids. Access to the complete PW Consulting Camera Module Adhesives Market report provides the full quantitative breakdowns, supplier-level scorecards, and downloadable scenario models that operational teams use to execute decisions with confidence.
Contact PW Consulting to obtain the complete report, request bespoke modeling for your product portfolio, or schedule a strategic briefing tailored to your role (procurement, R&D, corporate development). In a market growing from a mid-single-digit base into the early 2030s with a 6.9% CAGR, the difference between leading and lagging strategies will be set by how teams translate material science into predictable manufacturing and commercial advantage.
For detailed analysis of this topic, please visit the official page: Camera Module Adhesives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com