

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
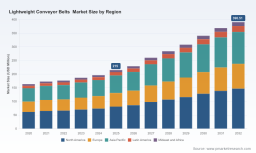
Lightweight Conveyor Belts Market: USD 215M in 2025, rising to USD 390.5M by 2032 at 8.9% CAGR

Lightweight Conveyor Belts Market — Strategic Imperatives for 2026 Decision-Making
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a distillation of the strategic intelligence embedded in our new Lightweight Conveyor Belts Market study. Anchored on a 2025 base year and a projected compound annual growth rate (CAGR) of 8.9% over the 2026–2032 forecast window, the market demonstrates robust expansion: from roughly USD 163 million in 2020 to an estimated USD 215 million in 2025, and approaching USD 391 million by 2032. For executives planning capital allocation, product roadmaps, or M&A moves in 2026, the right combination of timing and precision will determine winners and also-rans. This introductory briefing highlights the report’s strategic value while intentionally withholding core segment-level datapoints to guide you to the full study for the detailed models and proprietary spreadsheets.
Lightweight Conveyor Belts Market
Why this research matters in 2026
-
Actionable forecasting: The study converts a multi-year growth trajectory and volatility drivers into scenario-ready forecasts. CFOs and strategy teams can translate these into CAPEX phasing and working-capital models for 2026–2028.
Lightweight Conveyor Belts Market -
Competitive signaling: Our analysis exposes where leading vendors are placing bets—capacity expansion, product extensions, and hygiene-led innovation—enabling timely countermeasures or partnership plays.
Lightweight Conveyor Belts Market -
Risk-to-reward clarity: The report isolates raw-material sensitivity, regulatory risk, and aftermarket service opportunities so procurement and commercial functions can prioritize hedges and premium pricing where feasible.
-
Execution playbooks: For product managers and business development teams, the study translates macro trends into prioritized initiatives (e.g., material selection, modularization, service models) with measurable ROI frameworks.
Market dynamics shaping 2026 decisions
-
Structural demand drivers: Continued automation in food processing, e-commerce-driven logistics, and tighter hygiene regimes are core growth levers. Lightweight belts reduce conveyor energy demand and machine wear, accelerating replacement and retrofit cycles across automation projects.
-
Material & cost pressure: Polyurethane and other engineered thermoplastics remain attractive for hygiene and durability, but producers face cost pressures from feedstock volatility. In 2026 we observed material price upticks in key Asia supply hubs that compress margins for PU-heavy portfolios, prompting manufacturers to reassess pricing and sourcing strategies.
-
Regulatory & standards convergence: Food contact regulations across major markets (FDA, EU) and machine-safety standards such as ISO 22100-4 are tightening spec requirements. Compliance is now a commercial differentiator—buyers increasingly treat certifications and documented hygienic performance as non-negotiable selection criteria.
-
Environmental and process innovation: Water-based polyurethane and other lower-VOC formulations are moving from niche to mainstream as OEMs and end-users seek both hygiene and reduced environmental footprint. This shift is reflected in recent capacity and product investments by major suppliers.
-
Channel & aftermarket economics: Serviceable, retrofit-friendly belt designs and digital condition monitoring are unlocking recurring revenue streams—an important margin lever as product commoditization accelerates.
Competitive landscape — what the incumbents’ moves signal
The market exhibits moderate concentration: the top three players account for a meaningful but not dominant share of global revenues, and the top five consolidate a clear majority of industry scale. This structure creates an environment where global leaders set technology and compliance benchmarks, while focused specialists capture niche premium segments.
-
Habasit (Switzerland) — Strengths: fabric-based hygienic belts and deep food-sector relationships. Strategic relevance: leadership in tailored solutions for hygienic processing lines; watch for moves into integrated service contracts and digital installation aids.
-
Ammeraal Beltech (Netherlands) — Strengths: broad synthetic and modular portfolio plus fabrication capabilities. Strategic relevance: recent investments include a new plant dedicated to water-based polyurethane production—an explicit bet on sustainable, food-grade chemistries and a signal to competitors to de-risk legacy solvent-based supply chains.
-
Chiorino (Italy) — Strengths: precision in process-belt engineering for industrial automation. Strategic relevance: vertical focus on automation OEMs gives it a route to embed belts within machine-package sales, increasing switching costs for end-users.
-
Forbo Siegling (Germany) — Strengths: Transilon fabric-based belts and modular plastics. Strategic relevance: positions itself across fabric and plastic lines—an advantage in mixed-application accounts requiring both solutions.
-
Intralox (United States) — Strengths: modular plastic solutions optimized for food hygiene. Strategic relevance: aggressive product cadence in 2026 (notable belting and installation tool launches) shows a dual track of product performance improvement and installer productivity — a classic penetration strategy.
-
Volta Belting (Netherlands) — Strengths: homogeneous thermoplastic belts focused on hygiene and durability. Strategic relevance: recent introduction of a high-strength hygienic material underscores premiumization and the value of material science differentiation at trade shows and sector events.
-
Derco & Esbelt (Netherlands/Spain) — Strengths: pragmatic portfolios across PVC, PU, and plastic modular belts. Strategic relevance: these players often serve regional channels and act as important partners for OEMs seeking localized supply and fabrication services.
Taken together, these moves show an industry where incumbents deploy a mix of product innovation, capacity expansion, and installation/service tooling to protect margins and capture long-term service revenues. For potential entrants or capital allocators, the message is clear: compete on demonstrable hygiene performance, installer ergonomics, and supply-chain resilience—not just price.
What the full report delivers (actionable scope)
-
Robust market sizing and forecast models (2020–2032) including base-year reconciliation and scenario overlays tuned to material-price shocks and regulatory shifts.
-
Segment-level maps across types, applications and regions with buyer persona profiles that translate technical specifications into procurement decision criteria.
-
Profit-pool analysis identifying where manufacturing scale, customization, and aftermarket service create highest margin opportunities.
-
Supply-chain sensitivity matrix quantifying impact of raw-material swings and regional sourcing constraints on gross margins, with suggested procurement hedge structures.
-
Competitive benchmarking including product-technology matrices, capability heatmaps and a tactical watchlist of near-term strategic moves by key vendors.
-
Regulatory and standards playbook mapping compliance checkpoints by region and application—critical for commercialization timelines in food and pharma segments.
-
Decision-ready playbooks for go-to-market, pricing, channel design and M&A screening (including deal rationale templates and integration checklists).
-
Downloadable excel models and sensitivity dashboards for CFOs to stress-test CAPEX alternatives and investment returns under multiple scenarios.
How to use these insights in your 2026 playbook
-
Prioritize investments where regulatory and hygiene tailwinds create premium pricing power. If you serve food processors or pharma, emphasize certified materials and documented cleaning protocols.
-
Stress-test procurement: run material-price stress scenarios and build alternative sourcing and substitution strategies for polymer feedstocks—particularly polyurethane inputs where feedstock volatility can quickly erode margins.
-
Design product roadmaps that combine material innovation with installer ergonomics and serviceability. Tool launches that improve installation consistency (tensioning tools, clamp sets) amplify product propositions and reduce system downtime — a clear route to aftermarket revenues.
-
Consider targeted capacity moves or partnerships: the market’s concentrated but fragmented nature means strategic joint ventures or bolt-on acquisitions can rapidly scale capabilities in hygiene-certified manufacturing or localized fabrication.
-
Embed service and digital monitoring as part of pricing strategies. Recurring revenue models mitigate cyclical exposure and raise lifetime value per account.
Top-level recommendations
-
Make hygiene- and compliance-led product differentiation a priority rather than an afterthought.
-
Hedge feedstock exposure through diversified procurement and consider investing in water-based chemistries or alternative polymers.
-
Invest in installer productivity and condition-monitoring tools to unlock aftermarket margins.
-
Pursue targeted M&A or partnerships to achieve regional scale quickly where you lack fabrication or service presence.
-
Use scenario modeling to phase CAPEX aligned to 2026 demand inflection points—avoid all-or-nothing expansion bets.
PW Consulting’s full Lightweight Conveyor Belts Market report contains the granular segment models, regional breakdowns and proprietary market-share datasets that underpin these strategic takeaways. This introduction is designed as a tactical “preview”: it maps the terrain and flags where real competitive advantage will be earned in 2026, while preserving the detailed segment outputs and decision tools for the full report. For organizations preparing board-level investment memoranda, supplier negotiations, or acquisition screens this year, the full dataset and executable playbooks provide the difference between informed risk and speculative bets.
Contact the PW Consulting publications desk to access the complete study, the downloadable financial models, and the executive briefing package tailored for your strategic planning cycle.
For detailed analysis of this topic, please visit the official page: Lightweight Conveyor Belts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com