

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Fire-Resistant Hydraulic Fluids Market to Reach USD 200.62M by 2032 at 3.9% CAGR

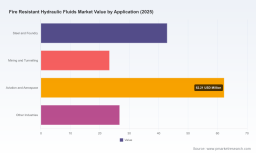
Fire Resistant Hydraulic Fluids Market 2026: Strategic Briefing for Executive Decision‑Makers
As companies set strategy for 2026 in heavy industry, steel mills, aerospace, and capital‑intensive process plants, the choice of hydraulic fluids — and the suppliers who provide them — has shifted from an operational detail to a source of competitive risk and opportunity. PW Consulting’s latest market study, based on a 2025 base year and a 2026–2032 forecast horizon, synthesizes technical, regulatory and commercial signals firms must act on now. The global market has expanded from roughly USD 130 million in 2020 to USD 155 million in 2025 and is projected to reach about USD 200.6 million by 2032, growing at a 3.9% CAGR. This steady, structurally driven growth underscores that incremental improvements in fluid selection, procurement strategy and supplier collaboration can yield outsized benefits for uptime, safety and total cost of ownership.
Fire Resistant Hydraulic Fluids Market
What this briefing delivers for decisions in 2026
- Sensitivity to regulatory shifts: New and updated standards (notably ISO 12922 and approvals referenced by major OEMs) are raising minimum performance baselines for oxidation stability, water content control and fire performance. Manufacturers must align product roadmaps and procurement specifications to avoid retrofit costs.
- Supply‑chain resilience planning: Raw material volatility (recent oxo‑chemical price jumps and regional feedstock disruptions) is creating short‑term margin pressure. Our study maps exposure across chemistries and recommends hedging and supplier concentration strategies.
- M&A and portfolio alignment: Market concentration is meaningful — leading suppliers hold a large share of demand — which makes inorganic moves and bolt‑on acquisitions an accelerating way to secure channel access and technology. We profile recent strategic transactions and their operational implications.
- Performance versus cost tradeoffs: Comparative lifecycle analyses in the report quantify when higher‑cost phosphate‑ester or synthetic‑ester products deliver better plant‑level economics through reduced fire risk, longer oil life and fewer maintenance interventions.
Report composition — actionable modules
- Market sizing and trend decomposition (2020–2025 historical, 2026–2032 forecast) with scenario pathways reflecting regulatory tightening and raw‑material shocks.
- Supply‑side intelligence: supplier scorecards, approval portfolios (FM, OEMs), technical performance matrices and fit‑for‑application routing by pressure, temperature and contamination risk.
- Cost modelling: feedstock price pass‑through, lubricant lifecycle costing, and maintenance cost linkages under different degradation and contamination regimes.
- Go‑to‑market playbooks for suppliers and industrial buyers, including contracting templates, inventory strategies and testing protocols to align operations with ISO and OEM requirements.
- Deal pipeline and strategic options: M&A targets, joint‑development partners and licensing routes to accelerate entry into higher‑value aviation and steel applications.
Competitive landscape — what the leading suppliers mean for your strategy
The market demonstrates a balance of scale and technical differentiation. The top three competitors control a substantial portion of market demand and the top five an even larger share, creating a dynamic where scale, approvals and distribution reach matter. At the same time, certification and product performance continue to open windows for regional and specialist entrants.
Fire Resistant Hydraulic Fluids Market
- Quaker Houghton — Known for its QUINTOLUBRIC polyol ester HFD‑U range and water‑glycol offerings, Quaker Houghton combines deep application engineering for steel and metalworking with broad service capabilities. For buyers, this positions them as a pragmatic partner for large‑scale, site‑level conversions and long‑term lubricant management agreements.
- Shell — Shell’s industrial lubricants group emphasizes formulations that limit flame propagation and ignition hazards. Their global logistics and OEM relationships make them a logical play for multinational operators seeking harmonized specifications across locations.
- CITGO Petroleum Corporation — With product lines tailored to high‑pressure steel mill and die‑casting systems, CITGO illustrates how regional scale combined with application focus can win specialized tenders where service and inventory responsiveness matter.
- Q8Oils — Q8’s ester‑based HFDU products with recognized approvals appeal to operators prioritizing high flash points and specific plant safety standards. Their positioning is an example of using technical credentialing to gain share in heavy industrial accounts.
- FUCHS — Active expansion by acquisition has broadened FUCHS’ product portfolio in the fire‑resistant segment. Their strategy underscores the role of M&A in building capability quickly — a relevant consideration for private‑equity‑backed entrants and strategic buyers alike.
- Houghton International — Houghton’s recent technical literature and application‑specific formulations signal a push to reinforce customer engineering support, making them a compelling partner for conversion projects and technical trials.
Recent strategic moves and market signals
- Acquisitions and capital moves: Consolidation activity, including portfolio add‑ons by established lubricant houses and private capital interest in major brands, shows acquirers are betting on the adjacent industrial‑fluids economics and the premium nature of fire‑resistant products.
- Certification and OEM acceptance: National airworthiness approvals and OEM lists are reshaping competition for aerospace and aviation applications — winning an airworthiness or OEM stamp of approval can drive rapid adoption in high‑value segments.
- Material and capacity trends: Price spikes in oxo‑intermediates and announced capacity expansions for phosphate‑ester intermediates create both risk and opportunity: short‑term cost pressure versus longer‑term supply security for vertically integrated players.
- Standards and procurement: ISO 12922 updates, and their adoption by environmental and procurement frameworks, mean buyers will increasingly specify measurable oxidation and water‑content metrics at tender stage — turning lab performance into a commercial requirement.
Dynamics that will drive supplier selection in 2026
Three dynamics will dominate procurement and product strategy this year:
Fire Resistant Hydraulic Fluids Market
- Regulatory and OEM alignment: Conformance to updated testing and measurement methods is non‑negotiable for access to major accounts and green procurement frameworks.
- Cost and availability of intermediates: Feedstock price volatility mandates flexible contracting, inventory buffers and multiple qualified suppliers to limit production interruptions.
- Supplier engineering capability: The ability to deliver application‑specific formulations, supported by field trials and documented lifecycle performance, is becoming as important as price in long‑term contracts.
Strategic implications and recommended actions for 2026
- For end‑users (steel, foundry, mining, aerospace): Prioritize qualification of two to three technical suppliers that collectively cover your OEM approval needs and feedstock risk exposure. Implement controlled pilot conversions with joint metrics for fire‑resistance, fluid life and maintenance intervals.
- For lubricant manufacturers: Accelerate certification efforts (national and OEM) where your formulations already meet performance thresholds; consider targeted acquisitions or licensing to fill gaps quickly in key geographies and application verticals.
- For investors and M&A teams: Evaluate targets that combine technical approvals, niche application penetration and downstream service contracts — these asset types de‑risk revenue and create recurring income streams.
- For procurement and supply‑chain leaders: Build feedstock exposure dashboards and include contractual clauses for price pass‑through and allocation priorities during feedstock shortages. Consider dual‑sourcing strategies for ester and water‑glycol chemistries where operational continuity is critical.
Why PW Consulting’s report is strategically valuable in 2026
The study translates market projections (3.9% CAGR through 2032 to roughly USD 200.6 million) into decision‑ready insights: supplier scorecards, approval matrices, cost pass‑through models and scenario playbooks calibrated to both regulatory tightening and raw‑material shocks. It bridges technical performance data with commercial levers — enabling executives to quantify the ROI of conversion projects, the payback for securing OEM approvals, and the tradeoffs of different sourcing strategies.
Importantly, our work follows a “trailer” approach: this briefing demonstrates the analytical depth and commercial relevance of the study while reserving granular segmentation, supplier benchmarking tables and downloadable financial models for the full report. Those core datasets — including detailed type, regional and application breakdowns and supplier‑level pricing curves — are central to bespoke purchasing or investment decisions and are available with the full research package.
Next steps
- Book a 60‑minute briefing with our industry desk to walk through scenario sensitivities and to map the implications for your 2026 procurement and product plans.
- Commission a tailored supplier due‑diligence or conversion pilot, leveraging our technical checklists and lifecycle costing templates from the report.
- Request the full report and Excel models to access the detailed segmentation, supplier scorecards and approval matrices that support executable contracts and investment theses.
In a market where safety, cost and continuity intersect, being proactive in 2026 will determine which companies convert regulatory pressure into competitive advantage. PW Consulting’s Fire Resistant Hydraulic Fluids Market study provides the evidence base and strategic roadmaps to do exactly that. Contact our team to access the full intelligence package and begin operationalizing these insights.
For detailed analysis of this topic, please visit the official page: Fire Resistant Hydraulic Fluids Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com