

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Polycarboxylate Superplasticizers Market: PW Consulting Forecast Shows 5.98% CAGR (2026–2032)

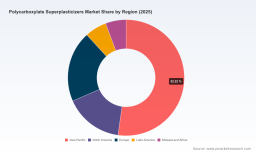
Polycarboxylate Superplasticizers Market — Strategic Preview for 2026 Decision-Makers
At PW Consulting, our practice advises boards, corporate strategy teams, and private equity sponsors on where to allocate capital and how to de-risk market-entry and scale-up plans. This market intelligence preview summarizes the high-conviction findings from our full Polycarboxylate Superplasticizers (PCE) Market study (base year 2025; historical 2020–2025; forecast 2026–2032), and explains why executives with 2026 decision horizons should prioritize this dossier.
Polycarboxylate Superplasticizers Market
Market snapshot — what the headline numbers mean for strategy
Our analysis quantifies a PCE market that expanded steadily through the 2020–2025 period and is projected to grow at a compound annual growth rate (CAGR) of approximately 5.98% over the 2026–2032 forecast window. In plain terms, demand and revenue trajectories that were measured in the low‑to‑mid billions of USD in the early 2020s pass into a materially larger market by the early 2030s. This pace of expansion is significant for capital allocation: it supports greenfield investments, targeted capacity expansions, and bolt‑on M&A programs, but it also requires disciplined supply‑chain and risk management to protect margins.
Polycarboxylate Superplasticizers Market
Importantly, the headline growth masks heterogeneity across customer segments, value chain positions, and geographies. The full report preserves that segmentation granularity for subscribers, but in this preview we intentionally withhold detailed split tables and point readers to the source page for the full data set. What follows is actionable perspective rather than raw sub‑segment disclosure.
Polycarboxylate Superplasticizers Market
Why the 2026 planning cycle is pivotal
- CapEx timing and lead times: Chemical plant expansions, polymerization lines, and third‑party tolling agreements have multi‑year lead times. Decisions taken in 2026 determine utilization and competitive positioning into the 2030–2032 window when market demand is significantly higher.
- Input cost volatility: Key monomers and co‑polymers that feed PCE synthesis experienced disruptive price swings in recent years. Supply disruptions and geopolitical events in 2025 fed through into raw material inflation, tightening spot availability at critical points in the value chain — a pattern we expect to continue in scenarios where feedstock markets remain tight.
- Product evolution and differentiation: Third‑generation PCE chemistries (monomer innovations, tailored side chains, powder vs liquid formulations) are moving from R&D into commercial rollouts. License, JV, or acquisition strategies executed in 2026 will determine who captures the premium for higher‑margin, high‑performance admixtures.
- Regulatory tightening: Compliance costs are rising (our modeling shows environmental and safety regulation headwinds can increase marginal production costs noticeably), and standards such as REACH require more granular substance submissions and residual monitoring. Firms that retro‑fit compliance into late‑stage expansion programs will underperform those that design for compliance from the outset.
Key demand and supply drivers
- Infrastructure and urbanization: Continued infrastructure replacement and urban construction activity underpin steady base demand, while pockets of accelerated activity (high‑rise, precast, high‑performance concrete projects) drive premium product uptake.
- Performance requirements: Concrete mix optimization for higher strength, lower water/cement ratio, and faster cycle times incentivizes adoption of advanced PCE formulations.
- Raw material dynamics: TPEG/HPEG feedstock and acrylic monomers remain the single largest source of margin volatility for producers. Recent market signals show spot prices moving sharply in response to petrochemical plant outages and extended feedstock chain disruptions; procurement strategies (vertical integration, long‑term supply agreements, hedging) materially change profitability profiles.
- Environmental, social and governance (ESG) pressures: Buyers increasingly demand suppliers who can demonstrate lower embodied carbon and robust chemical safety management. PCE producers who can quantify life‑cycle benefits and reduce manufacturing emissions gain advantaged access to institutional buyers.
Risks and scenario sensitivities
- Geopolitical shocks: Middle‑East supply chain tensions in 2025 already contributed to raw material cost spikes; similar shocks can rapidly compress margins for unconsolidated producers.
- Regulatory compliance cost inflation: Stringent chemical registration and monitoring requirements lift operating expense; our scenario testing shows that non‑compliant or late‑compliant players face both cost penalties and market access restrictions.
- Technology substitution risk: Incremental improvements in alternative admixtures or mix designs could erode the premium for certain PCE grades; sustained R&D investment is required to protect value.
- Concentration and pricing pressure: While top incumbents retain strong customer relationships and technical service capabilities, the market is not immune to price competition from lower‑cost regional suppliers or factory‑direct producers. Competitive dynamics vary by channel and application.
What the full report contains — practical, deal‑ready analysis
Our full market study is designed for immediate boardroom use. Key deliverables include:
- Transparent market sizing and revenue modeling (base year 2025; historical 2020–2025; forecast 2026–2032) with sensitivity ranges and scenario outputs suitable for valuation models.
- Demand segmentation by application and region with addressable market maps, adoption curves, and value capture pathways (note: detailed segment tables are gated to preserve subscriber value).
- Supply‑chain mapping, raw‑material exposure matrices, and procurement playbooks highlighting where to lock margins through feedstock strategies.
- Regulatory impact assessment (REACH and regional chemical compliance), compliance cost estimates, and a roadmap to design-for-compliance in new plants.
- Competitive benchmarking with each major player profiled on product portfolio, channel strategy, technical service capability, and partnership history.
- Transaction guidance: a short‑list of acquisition targets and low‑hanging collaboration opportunities, valuation triangulation, and integration risk checklists.
- Commercial playbooks for go‑to‑market (pricing, distribution, specification management) and product development (formulations, powder vs liquid commercialization tradeoffs).
Competitive landscape — who to watch
The market features a mix of global chemical majors, specialized admixture producers, and vertically integrated regional players. Below are the principal companies we profile in depth (headquarters and web references included as a convenience):
- Sika AG (Baar, Switzerland) — https://www.sika.com — notable for its ViscoCrete® PCE portfolio targeting high‑performance concrete.
- BASF SE (Ludwigshafen, Germany) — https://www.basf.com — a major innovator; recently introduced a new iPEG monomer platform designed for third‑generation PCEs.
- GCP Applied Technologies (Alpharetta, GA, USA) — https://gcp.com — producer of ADVA® products focused on admixture performance.
- Chryso (Courbevoie, France) — https://www.chryso.com — supplier to ready‑mix and paving segments with a broad admixture range.
- Fosroc International (London, UK) — https://www.fosroc.com — offers high‑range water reducers for performance‑critical mixes.
- Arkema (Colombes, France) — https://www.arkema.com — a provider with integrated construction chemicals capabilities.
- Mapei S.p.A. (Milan, Italy) — https://www.mapei.com — notable for construction chemicals and PCE formulations.
- Kao Corporation (Tokyo, Japan) — https://www.kao.com — supplier of admixtures focused on regional markets.
- Selected Chinese producers (examples include Sobute, MUHU, Jiahua, Kima, WOTAIchem) — factory‑direct suppliers that compete aggressively on price and local service.
- Altus Material and CEMEX Admixtures (U.S.) — https://altusmaterial.com, https://www.cemex.com — examples of localized innovation and integration with concrete producers.
Recent industry moves underscore the strategic dynamics we describe: in 2025 a major chemical company launched a new isoprenol‑PEG monomer specifically targeted at third‑generation PCEs; another announced capacity expansion in Europe to capture rising demand. These actions validate our view that both product innovation and scale remain decisive competitive levers.
Executive imperatives for 2026
- Stress‑test your portfolio against feedstock scenarios: model PCE margin sensitivity to TPEG/HPEG and acrylic price shocks; shift procurement from spot to diversified long‑term contracts where feasible.
- Prioritize regulatory‑first design: build environmental and chemical‑compliance costs into new capacity models and product development roadmaps to avoid retrofit penalties.
- Choose commercialization pathways deliberately: decide whether to compete on premium technical service and differentiated chemistries, or to pursue cost leadership through local, factory‑direct models — both are viable, but require different operating models.
- Assess M&A targets with integration playbooks: target regional producers with complementary channels or specific formulation IP; a short due‑diligence checklist in our report speeds appraisal.
- Invest in customer co‑development: technical support and lab‑to‑site trials remain the fastest route to specification wins in concrete contractors and precast manufacturers.
How to use this preview
This preview is intentionally focused on strategic implications and topline metrics. The full PW Consulting PCE Market study contains the fortified datasets, regional and application-level breakouts, supplier share matrices, and downloadable financial models that boards and deal teams need to execute decisively in 2026. We have withheld specific segmentation tables and sensitive competitive concentration metrics from this summary to protect the commercial integrity of the fieldwork and to ensure subscribers receive exclusive access to the full intelligence package.
Contact PW Consulting to request the full report, the underlying datasets, or a tailored executive briefing. In markets where lead time, feedstock volatility, and regulatory pressure converge, the difference between a reactive plan and a proactive strategy is measured in months — not years. For executives planning capital and commercial moves in 2026, the time to act is now.
For detailed analysis of this topic, please visit the official page: Polycarboxylate Superplasticizers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com