

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Vapor Chamber Market to Reach USD 5,790 Million by 2032 at 10.5% CAGR

Vapor Chamber Market: Strategic Briefing for 2026 — Why This Study Will Shape Your Next Move
Executive snapshot
By 2025 the global vapor chamber market reached roughly USD 2,990 Million (base year: 2025). Our model projects a sustained compound annual growth rate (CAGR) of approximately 10.5% through the forecast window, positioning the market north of USD 5.7 Billion by 2032. For corporate leaders making capital allocation, product and supply-chain choices in 2026, this study is designed to translate that headline expansion into actionable priorities — without burying you in raw tables. Consider this article a trailer: it demonstrates the depth and practical orientation of the full PW Consulting analysis while preserving critical, high-value segmentation and unit-level intelligence for the full report access.
Vapor Chamber Market
Why 2026 is a strategic inflection point
- Demand geometry: Multiple end-markets (consumer electronics, data centers, automotive, aerospace, healthcare and industrial) are converging on higher thermal-performance requirements. This is no longer a niche heat-spreading technology: vapor chambers are moving from optional performance uplift to required enablers in designs constrained by power density and form factor.
- Supply-side transformation: Capacity investments and new product families introduced in late 2025–mid 2026 are materially reshaping manufacturing economics. Some suppliers have already announced multi-fold capacity expansions targeted at AI/ASIC and server cooling segments, tilting supplier bargaining power and time-to-market dynamics.
- Input-cost volatility and policy risk: The commodity cycle and trade policy interventions in 2025–2026 have amplified input-cost and sourcing risk for copper-heavy assemblies, requiring procurement playbooks that marry hedging, alternate material strategies, and nearshoring considerations.
What the PW Consulting study delivers (practical, transaction-ready intelligence)
This research goes beyond market-sizing and trend narration. It is a practitioner’s dossier for executives and deal teams preparing to compete or invest in vapor chamber value chains in 2026:
Vapor Chamber Market
- Investment-grade TAM and demand scenarios: base, upside and stress cases that reconcile end-market unit trajectories with thermal design adoption curves.
- Driver-based cost model: factory-level cost build-ups, sensitivity to copper and PCM inputs, labor and automation levers — stated as templates you can apply to your own BOMs (modeling worksheets included in the full deliverable).
- Supplier scorecards and capacity maps: production footprints, lead-time risk hot spots, and a dynamic supplier risk index calibrated for 2026 supply shocks.
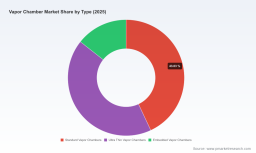
- Product and IP segmentation playbook: how to prioritize standard, ultra-thin and embedded vapor chamber portfolios against OEM qualification cycles and regulatory constraints.
- Regulatory and qualification navigator: checklists and timelines for AEC-Q100, IATF 16949, ISO 13485 and other customer/OEM certification gates that commonly extend project timelines by 12–36 months.
- M&A and partnership playbook: valuation heuristics, bolt-on targets, JV structures and earn-out frameworks for consolidators and strategic buyers.
- Go-to-market tactical templates: OEM engagement sequences, design-win timelines, and pricing strategies for high-power vs. form-factor-sensitive segments.
Market dynamics that matter in 2026
The market’s macro trajectory is robust: with a mid-teens-ish expansion in absolute dollars expected over the forecast period, firms that move early to secure design wins and scale will capture asymmetric value. Key dynamics we explore in the report include:
Vapor Chamber Market
- Thermal performance ceilings: advances in vapor chamber geometry, wicking and ultra-thin manufacturing mean thermal solutions are being specified for power densities previously reserved for active liquid cooling. This drives differentiated product tiers and margin dispersion.
- Qualification and time-to-revenue friction: OEM qualification standards in automotive and medical markets (AEC-Q100, IATF 16949, ISO 13485) impose long lead-times and high test burdens; our analysis quantifies the typical investment and calendar impact per market.
- Commodity and trade-policy shock scenarios: 2025–2026 saw record copper price pressure and tariff actions that materially increased producers’ cost-of-goods and reshuffled cost-competitive geographies. The full report models several mitigations — from alloy substitution and plating strategies to procurement hedging and supplier diversification.
- Concentration and competitive structure: the vapor chamber market displays a low-to-moderate concentration structure; major incumbents collectively control a minority share, leaving room for niche specialists and high-volume OEM suppliers to expand through both organic and inorganic routes.
Competitive landscape — what you need to know now
Our competitive analysis synthesizes corporate positioning, product breadth, capability gaps and near-term strategic moves across the vendor ecosystem. Highlights include:
- Strategic capacity builders: Several Taiwanese and regional manufacturers have accelerated capacity additions aimed at AI-server, GPU and high-power compute segments. These moves materially change lead-time and scale economics for large OEM contracts.
- Product breadth and specialization: Market players differentiate on thickness (standard vs. ultra-thin), embedded designs, and integrated thermal-module solutions for specific end-markets (e.g., AI servers, foldable consumer devices, automotive power modules). Companies that bundle vapor chambers with thermal modules and system-level engineering services extract higher margin capture and longer-term customer stickiness.
- North-south technology transfer and cost arbitrage: Chinese manufacturers are increasingly competitive on 3D and thin-form vapor chambers, while US and Taiwanese firms emphasize integrated engineering services, IP protection and quality systems favored by tier-1 OEMs.
- Notable corporate developments: Recent public disclosures in early-to-mid 2026 show capacity buildouts, new high-spec product introductions and design guidance updates that together accelerate adoption for high-power applications. These are tracked in a dedicated timeline within the full report.
Regulatory, procurement and raw-material risk — practical implications
Regulatory compliance is not just a certification checkbox: it materially affects time-to-revenue and cost. Automotive- and medical-grade vapor chambers require rigorous qualification and test matrices, which our fieldwork shows commonly extend project schedules and necessitate capitalized testing budgets.
On the procurement side, record-level copper dynamics and tariff moves in mid-2025–2026 elevated raw-material cost exposure. Effective procurement strategies we model include dual-sourcing, long-term offtakes with indexation clauses, and selective pass-through pricing in OEM contracts. The report includes scenario outputs showing the P&L sensitivity of these strategies under different commodity and tariff shocks.
High-conviction plays for 2026
- Secure early design wins in high-growth, high-ASP segments (AI, data-center accelerators) where cycle-times compress margins less than consumer product channels.
- Invest in thin/embedded process IP or partner with a specialist — thin-form factor wins are conversion barriers that justify price premiums in handheld and mobile applications.
- Rebalance the supply chain: diversify sourcing of critical copper inputs and qualify geographically distinct contract manufacturers to mitigate tariff and logistics risk.
- Structure OEM contracts to share upstream commodity exposure and align incentives for scale: include step-up pricing bands and volume rebates tied to validated design wins.
- Prepare regulatory roadmaps early for automotive and medical programs to avoid late-stage rework that erodes margin and time-to-market.
Why PW Consulting’s vapor chamber study is different
We combine primary vendor interviews, factory tours, BOM-level cost models and OEM qualification-path mappings to produce an actionable blueprint. Instead of generic slices of demand by region and application, we translate market momentum into decision-support tools: scenario P&Ls, supplier risk indices, investment timelines and M&A targets prioritized by strategic fit and time-to-value.
How to use this briefing in 2026 strategic planning
- Board-level budgeting: use our downside and upside scenarios to stress capital plans and to set guardrails for capacity additions.
- Corporate development teams: prioritize M&A targets using our valuation premia that reflect IP ownership, design-win stickiness, and supplier footprint.
- Product and engineering leaders: adopt the report’s technology roadmap to align product launches with the OEM qualification cadence.
- Procurement and operations: implement the tactical sourcing and hedging templates to reduce COGS volatility and ensure continuity of supply during peak ramp periods.
Next steps — where to get the full playbook
This article intentionally omits proprietary segmentation matrices and unit-level forecasts that form the highest-value outputs in our research — these are available in the full PW Consulting Vapor Chamber Market report. The full deliverable contains detailed regional and application splits, supplier-by-supplier competitive scorecards, factory economics, and downloadable financial models designed for integration with your own planning systems.
For leadership teams prioritizing decisive action in 2026, this report is both a radar and a road-map: it identifies where the next design-wins and scale economies will appear, and it prescribes the commercial, operational and financial playbooks to capture them.
For detailed analysis of this topic, please visit the official page: Vapor Chamber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com