

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Hydrotalcite Market to Reach $273.72M by 2032 at 5.8% CAGR

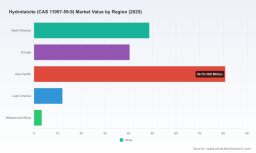
Hydrotalcite (CAS 11097-59-9): Strategic Outlook for 2026 Decision-Makers
As global chemical buyers, specialty compounders, and strategic investors plan capital and commercial moves for 2026, hydrotalcite (CAS 11097-59-9) is emerging as a quietly pivotal input across plastics, pharmaceuticals, and advanced materials. PW Consulting’s new market study—anchored to 2025 as the base year and projecting through 2032—maps a market that has expanded steadily over the first half of the decade and is forecast to continue growing at a mid-single-digit compound annual growth rate. Between 2020 and 2025 the market demonstrated resilient expansion; our baseline projections point to sustained growth through 2032 under current demand drivers and regulatory trends.
Hydrotalcite (CAS 11097-59-9) Market
Why this study matters to 2026 strategy
-
Timing for capacity and product investments: Manufacturers and compounders face a choice in 2026—scale commodity-grade capacity to secure volume-led margins, or deploy capital toward high-purity and surface-modified grades that command price premia but require tighter raw-material control and regulatory certification. Our forecast trajectory provides the demand visibility needed to validate either path and to phase capex with confidence.
Hydrotalcite (CAS 11097-59-9) Market -
Regulatory compliance as a market filter: Regulatory tightening in major markets is transforming hydrotalcite from a simple heat stabilizer to a certified excipient and specialty additive. Companies that align R&D and quality systems to evolving REACH and FDA excipient guidance will unlock higher-margin channels in pharmaceuticals and food-contact applications.
Hydrotalcite (CAS 11097-59-9) Market -
Supply-chain resilience and feedstock security: The synthesis route for high-quality hydrotalcite is dependent on purified magnesium and controlled co-precipitation processes. Procurement executives will need scenario-based sourcing strategies to mitigate volatility in feedstock purification costs and to assure pharmaceutical-grade traceability.
Market health at a glance (high-level)
Our study documents year-by-year market size from 2020 through 2032 in USD (Million). The market expanded from the early-2020s into 2025 and is forecast to continue its upward trajectory through 2032 at an approximate CAGR of 5.8% under the base-case assumptions used in this research. This growth reflects the combined effect of persistent demand in polymer stabilization, renewed uptake in pharmaceutical and food-grade applications, and incremental adoption in advanced material and flame-retardant applications tied to electrification and cable insulation trends.
Note: This introduction deliberately presents high-level market trends and the headline growth assumptions to inform executive decision-making. Core segmentation data, price curves, and addressable-market breakdowns are reserved for the full report to preserve the competitive intelligence value of the dataset.
Demand-side dynamics
-
Polymer and PVC stabilization remain the dominant demand pillars. The combination of performance (heat stability, halogen scavenging) and an accelerating regulatory preference for heavy-metal-free stabilizers has kept hydrotalcite central to formulation strategies across flexible and rigid PVC and an increasing share of polyolefin formulations.
-
Pharmaceutical and food-grade applications are a fast-follow opportunity: enhanced purity grades, validated excipient status, and tailored particle morphologies enable entry into antacid and excipient markets, but require significant investment into GMP-style production controls and certification programs.
-
Electrification and flame retardancy: Electric vehicle wiring, cable insulation, and flame-retardant masterbatches are driving demand for engineered hydrotalcite grades. These grades often have surface treatments or tailored compositions to improve dispersion and performance in filled systems.
Supply-side and manufacturing considerations
-
Raw-material purification is non-trivial. Industrial magnesium feedstocks require stringent cleanup to meet high-purity and pharmaceutical specifications; this adds technical and cost layers that favor incumbents or vertically integrated players who can secure feedstock quality.
-
Specialty grades increase technical complexity. Nano-sized and surface-treated materials deliver performance benefits but introduce higher production costs and narrower commercial windows in price-sensitive markets. Adoption will be stepwise and concentrated in applications with clear value capture.
-
Geographic deployment of capacity matters. Recent capacity additions in Europe and new lines targeting European compounders demonstrate suppliers’ strategic focus on proximity to automotive, cable, and pharmaceutical hubs. Companies planning investments should align plant footprints with regulatory, logistics, and customer concentration maps.
Competitive landscape — what to watch
The hydrotalcite market exhibits a moderate degree of concentration: top-tier manufacturers command meaningful scale and technical advantage, while a broader tier of regional suppliers competes on cost and service. Our research maps incumbent strengths and strategic moves by companies that set the tone for 2026:
-
Kyowa Chemical Industry (Japan) — an early industrial pioneer with product families oriented to PVC stabilization and medical antacids. Their recent investments to expand European supply capacity reflect a play to serve both polymer and pharma customers with high-purity grades.
-
Sakai Chemical Industry (Japan) — specialist grades targeting thermal performance and color retention in plastics. Expansion activity aimed at EV wire insulation underlines the company’s tactical pivot to flame-retardant markets.
-
Clariant AG (Switzerland) — a major specialty player focusing on heavy-metal-free formulations and recently expanding European capacity while licensing new high-purity grades for pharmaceutical use. Clariant’s moves illustrate how broad chemical platforms can accelerate grade development and regional market access.
-
SINWON Chemical, GCH Technology, Doobon, Sasol, and Heubach — these regional and multinational players provide diversified supply, technical service, and localized product variants. Their combined presence sustains competition on price, grade breadth, and proximity to downstream manufacturers.
Recent publicly announced capacity and product initiatives during 2025 illustrate a clear pattern: supply-side incumbents are securing footprint and introducing pharmaceutical- and specialty-oriented grades to capture value beyond commodity PVC markets. For buyers and investors, this signals a tightening of the premium-grade supply curve during the mid-decade planning horizon.
Regulatory and sustainability context
-
Regulatory tightening is a differentiator. REACH in Europe and evolving FDA excipient expectations in the U.S. raise the bar for documented purity, impurity profiles, and manufacturing controls. Certifications and validated supply chains will be prerequisites for pharmaceutical and food-contact adoption.
-
Environmental preferences are reshaping formulations. A significant portion of industrial adoption reflects a shift toward eco-friendlier stabilizers, where hydrotalcite’s profile can be advantageous versus legacy heavy-metal chemistries.
Strategic implications and recommended actions for 2026
-
For producers: adopt a tiered-capability strategy. Separate investments into (a) cost-competitive commodity capacity to protect volume channels and (b) certified, high-purity lines with traceability and quality systems to serve pharmaceuticals, food, and high-value polymer applications. Align capex phasing with our forecast horizon to avoid overcapacity risk.
-
For compounders and OEMs: specify material provenance and performance thresholds now. Locking supply agreements with certified suppliers and qualifying alternative grades will lower disruption risk and protect product claims in regulated markets.
-
For investors and M&A strategists: target bolt-on acquisitions that provide regulatory-qualified manufacturing or feedstock purification capabilities. Add-on plays that compress time-to-market for pharmaceutical grades are likely to offer asymmetric returns.
-
For procurement and risk teams: stress-test supplier base against scenarios of feedstock constraint and regulatory change. Diversify across technologies (e.g., sol-gel vs co-precipitation routes) and negotiate quality escrow arrangements for excipient-grade supply.
What the full report delivers
PW Consulting’s full market research expands the strategic threads above into actionable deliverables: a granular addressable-market model, price and margin curves by grade, supply-demand balance by scenario, supplier scorecards, regulatory roadmaps, supply-chain stress tests, go-to-market playbooks for specialty-grade launches, and a prioritized M&A watchlist. The report also includes primary-sourced interviews with compounders and manufacturers, and an annotated timeline of regional capacity moves and product innovations.
To preserve the competitive integrity of our analysis—and to provide readers with a clear incentive to engage—this introduction presents the headline forecasts and strategic implications while reserving detailed segmentation and operator-specific share data for the full study.
Next steps for executives
-
Use the headline growth profile and the regulatory trends summarized above to validate 2026 capital and sourcing decisions.
-
Commission a focused supplier qualification audit if your product roadmap includes pharmaceutical or food-contact claims; the ramp from polymer-grade to excipient-grade is operationally intensive.
-
Engage with PW Consulting for a tailored briefing that maps our full dataset to your company’s product lines, procurement footprint, and regulatory exposure.
Hydrotalcite is no longer a niche filler; it is a strategic lever across multiple value chains. In 2026, the companies that convert regulated-quality capability into scalable supply while maintaining cost discipline will capture the most attractive economics. For the complete segmentation, price schedules, supplier scorecards, and scenario-modeled forecasts that support these decisions, consult the PW Consulting full Hydrotalcite (CAS 11097-59-9) Market report.
For detailed analysis of this topic, please visit the official page: Hydrotalcite (CAS 11097-59-9) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com