

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Insight: Polymer-Based TIM Market at USD 793.9M in 2025

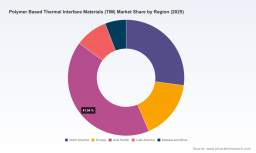
Polymer-Based Thermal Interface Materials (TIM) Market — Strategic Outlook for 2026 Decision‑Makers
Executive summary
As thermal management requirements tighten across electronics, automotive electrification and heavy infrastructure, polymer-based thermal interface materials (TIMs) are at the intersection of materials science, supply‑chain risk and regulatory change. Our PW Consulting study — grounded in audited historicals (2020–2025) and forward-looking scenarios (2026–2032) — shows a market that expanded from USD 688.15 Million in 2020 to USD 793.9 Million in 2025 and is forecast to grow at a modest compound annual growth rate (CAGR) of 2.27% through the 2026–2032 window, reaching roughly USD 932.8 Million by 2032. This measured growth masks considerable complexity: concentrated supplier positions, raw‑material volatility, accelerating regulation on recyclability and emissions, and shifting end‑market dynamics that will define winners and losers in 2026 and beyond.
Polymer Based Thermal Interface Materials (TIM) Market
Why this report matters for 2026 strategic choices
-
Investment and capacity planning: A low-to-moderate aggregate growth rate forces a choice between pursuing share through differentiation or competing on cost. Capex and capacity decisions must be informed by granular demand scenarios rather than headline growth alone.
Polymer Based Thermal Interface Materials (TIM) Market -
Margin protection vs. market share: Stable revenue growth conceals episodic cost shocks (notably in silicone feedstocks). Procurement and product-pricing strategies designed for volatility will be discriminating advantages.
Polymer Based Thermal Interface Materials (TIM) Market -
Regulatory timetables will re‑shape product roadmaps. New EU rules on recyclability and restrictions accelerating adoption of halogen‑free and low‑VOC formulations create both compliance risk and first‑mover opportunities for suppliers who can reformulate quickly.
-
Competitive consolidation and partner plays: The market structure is concentrated — the top three suppliers account for roughly 62.4% of industry revenues and the top five about 74.2% — creating a landscape where strategic partnerships, co‑development agreements and selective M&A can materially change competitive trajectories.
Report contents — practical intelligence we provide
-
Validated market sizing and multi‑scenario forecasts (2026–2032) with demand drivers and downside/upside sensitivity analyses calibrated to component lead times and end‑market cycles.
-
End‑to‑end supply‑chain mapping and cost‑to‑serve models that translate raw‑material price moves into impact on gross margin by product family and customer segment.
-
Regulatory impact matrix and compliance roadmaps for EU and major markets, including product reformulation windows and estimated compliance cost ranges.
-
Competitive benchmarking: capability heatmaps, technology positioning, commercial footprints and an M&A playbook prioritizing targets by strategic fit and integration risk.
-
Commercial playbooks and procurement negotiation templates, designed for OEMs, contract manufacturers and TIM suppliers to optimize contract length, price escalators and pass‑through clauses under volatile raw‑material regimes.
-
Technology and product roadmaps that align performance (thermal resistance, compressibility, outgassing, lifetime) with regulatory constraints and manufacturing cost levers.
Market dynamics shaping 2026 decisions
-
Raw‑material volatility: Early 2026 saw a sharp uptick in silicone prices (approximately +28%) and a roughly +15% increase in silicon metal feedstock costs (Semitech Insights, March 2026). These spikes materially alter cost curves for silicone‑based TIMs and compress legacy margins for producers that lack hedging strategies or flexible formulations.
-
Regulatory acceleration: New EU requirements on recyclability and tighter restrictions on halogen content and VOC emissions are not distant possibilities — they are active drivers forcing reformulation timelines and supply‑chain audits (IDTechEx TIM Report, 2026). Suppliers who front‑load compliance testing will avoid retrofit costs and access preference in automotive and hyperscale data center procurement.
-
Customer expectations: OEMs increasingly bundle thermal management specifications with sustainability KPIs and lifecycle cost models. The purchasing decision is shifting from unit price to validated TCO and circularity credentials.
-
Concentration and bargaining power: High concentration amplifies the commercial leverage of tier‑one suppliers but also increases procurement vulnerability for customers that lack alternative validated sources or reformulation capability.
Competitive landscape — strategic profiles
-
Henkel AG & Co. KGaA (Düsseldorf, Germany — https://www.henkel.com) : With established brands and an integrated portfolio spanning gap fillers, phase‑change materials and elastomeric pads, Henkel’s strength is breadth and customer co‑development. Strategic moves to watch: accelerated automotive validation programs and deeper OEM partnerships emphasizing recyclability.
-
3M Company (St. Paul, MN — https://www.3m.com) : A major presence on thermally conductive pads and tapes, 3M leverages scale, adhesive technology and global distribution. Competitive edge lies in application engineering and rapid prototyping for consumer electronics. Vulnerability: cost exposure to polymer feedstocks if hedging is insufficient.
-
Dow Inc. (Midland, MI — https://www.dow.com) : Supplier of advanced silicone‑based TIMs targeting high‑performance electronics, EVs and data centers. Dow’s strengths are materials innovation and vertical integration potential; expect initiatives around silicone performance enhancement and sustainability claims.
-
Parker Hannifin / Chomerics (Cleveland, OH — https://www.parker.com) : Focused on elastomeric pads and gap fillers for aerospace, defense and industrial segments. Parker’s domain expertise in ruggedized applications and qualification cycles is an entry barrier for new suppliers eyeing specialized markets.
-
Shin‑Etsu Chemical (Tokyo — https://www.shinetsu.co.jp) : High‑purity silicone and polymer compound supplier with strengths in semiconductor and electronics applications. Shin‑Etsu’s capabilities support customers requiring tight material specifications and long lifecycle stability.
-
Momentive Performance Materials (Niskayuna, NY — https://www.momentive.com) : Advanced polymer composites and silicone TIMs, competitive in industrial and electronics thermal management; watch for co‑development with OEMs on data‑center thermal solutions.
-
Wacker Chemie AG (Munich — https://www.wacker.com) : Specialist in silicone polymer chemistries, positioned to capitalize on demand for low‑VOC and high‑performance formulations. Strategic focus likely on automotive EV validations.
-
Elkem ASA (Oslo — https://www.elkem.com) : Supplies silicone and polymer TIMs for electronics and industrial apps; strategic advantages include feedstock integration and European supply footprints.
-
Polymer Science, Inc. (Monticello, IN — https://polymerscience.com) : Niche and custom‑focused, serving medical and specialized electronics markets. Their agility for custom formulations can attract clients seeking rapid validation and small‑batch innovation.
Strategic implications and recommended actions for 2026
-
Immediate procurement playbook: Negotiate flexible contracts with price collars and longer‑term volume commitments where appropriate; use our cost‑to‑serve models to determine acceptability thresholds for passing through raw material surcharges.
-
Formulation and R&D priorities: Fast‑track low‑VOC and halogen‑free reformulations targeted at automotive and data centers; invest in recyclability testing to claim early compliance and secure OEM qualification windows.
-
Supply‑chain resilience: Diversify critical feedstock sources, evaluate regional manufacturing to reduce lead times and consider strategic inventory buffers for key silicone intermediates during peak volatility.
-
Commercial differentiation: Build validated sustainability narratives (verified recyclability, lower lifecycle emissions) into product value propositions — customers are increasingly awarding preference to verified circular solutions.
-
M&A and partnerships: Prioritize targets that close capability gaps (e.g., low‑VOC chemistries, validation labs, regional manufacturing) and offer rapid route‑to‑market in regulated segments.
-
Scenario planning: Use the report’s sensitivity modules to stress‑test P&L under alternate raw‑material, regulatory and demand curves; incorporate these outputs into 2026 budgeting and capital allocation decisions.
How to use the study
-
For strategy teams: Translate scenario outputs into a 24‑month roadmap for product, regulatory and capacity investment.
-
For procurement: Leverage supplier benchmarking and cost models to re‑shape sourcing strategies and renegotiate contracts.
-
For R&D and product management: Use the technology roadmaps and test‑matrix templates to sequence reformulation and validation activities aligned to regulatory deadlines.
-
For corporate development: Apply the M&A playbook and target screen to prioritize inorganic growth that accelerates compliance and performance differentiation.
Next steps (teaser)
PW Consulting’s full report contains the granular datasets, validated segmentations by region, type and application, supplier scorecards and downloadable financial models necessary to operationalize the actions above. This briefing has highlighted the strategic signals and recommended plays for 2026 without disclosing proprietary segment‑level figures — for access to the detailed tables, scenario files and supplier heatmaps, consult the full report on our source webpage or contact our advisory team to schedule a bespoke briefing and model walkthrough.
For detailed analysis of this topic, please visit the official page: Polymer Based Thermal Interface Materials (TIM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com