

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cobalt Market to Grow at 6.69% CAGR (2026-2032)

Cobalt Market 2026: Strategic Intelligence for Boardroom Decisions
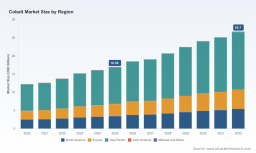
As PW Consulting’s lead industry analyst, I present an executive preview of our Cobalt Market research — a targeted, decision-focused briefing structured to help executives calibrate strategy in 2026. Built on a base year of 2025 and a historical lens covering 2020–2025, the full study projects the market across 2026–2032. Our headline finding: the global cobalt market is on a sustained growth trajectory with a compound annual growth rate of 6.69%, expanding materially from an assessed USD 16.96 billion in 2025 toward a projected market north of USD 26 billion by 2032. This preview outlines the strategic implications, competitive dynamics, and the precise operational modules included in the full report — while intentionally withholding granular segment tables and regional splits to preserve the analytic value available only in the report itself.
Cobalt Market
Why this research matters for 2026 decision cycles
-
Timing capital allocation: The medium-term growth path (2026–2032) is clear and durable, driven by electric mobility, industrial metallurgy, and high-performance applications. Boards and CFOs evaluating capex, offtake agreements, or refinery investments in 2026 need an evidence-based view of demand momentum and realistic upside scenarios. Our forecast provides that trajectory and quantifies growth sensitivity to key demand levers.
Cobalt Market -
Supply-chain resilience and sourcing strategy: Geopolitical concentration of upstream supply and concentrated refining capacity are constraining factors that can amplify price volatility and availability risk. Strategic procurement teams must weigh long-term supply contracts, backward integration, and inventory policy against heightened policy risk and trade frictions.
Cobalt Market -
M&A and partnership prioritization: With midstream and downstream pockets of value, 2026 is a year for opportunistic consolidation and strategic partnerships — particularly where firms can secure feedstock, battery-grade refinement, or end-market integration. The full study identifies the most accretive deal archetypes and valuation benchmarks.
-
Regulatory and ESG readiness: Increasing regulatory intervention, import tariffs, and scrutiny of cobalt sourcing and processing require a proactive compliance and traceability posture. Our analysis maps regulatory vectors and provides an operational readiness checklist for 2026 implementation.
Market dynamics: what the numbers reveal (and what we do not disclose here)
From a macro perspective, the cobalt market has expanded significantly during the 2020–2025 vintage years. Our base-year assessment (2025) and the forecast window (2026–2032) demonstrate a steady compound growth rate of approximately 6.69% — enough to justify multi-year investments but not so steep as to rule out meaningful substitution or efficiency gains in adjacent technologies. By 2032 the market is projected to exceed USD 26 billion, confirming a multi-billion-dollar incremental pool of demand for participants along the value chain.
What we are not publishing in this teaser are the full segment-level revenue schedules, regional and application-level percentage splits, and granular cost curves — the core analytic assets in our paid model. These withheld datasets are central to contract negotiation strategies, plant-sizing, and region-specific entry/exit decisions; they are accessible in the full briefing.
Supply-side structure and concentration
Two structural features stand out and carry immediate implications for 2026 strategy:
-
Concentration among producers and refiners: Market concentration is non-trivial — our study estimates that the top three companies control a near-majority share of the market, and the top five account for roughly 60% of global supply. For buyers, this implies counterparty concentration risk and potential price-setting dynamics that favor large incumbent suppliers.
-
Geopolitical supply risk: Recent industry reporting and public data indicate that a substantial share of mine production and refining feedstock comes from a very limited set of source countries and integrated refiners. This centralization elevates the impact of export restrictions, tariffs, and policy shifts on global availability and pricing.
These structural realities inform several high-priority actions: diversification of supplier networks, strategic inventory buffers, increased due diligence of midstream partners, and accelerated investment in processing capability outside highly concentrated basins.
Competitive landscape: profiles and strategic posture
Our research evaluates the strategic positions of major global actors. A selection of these profiles and inferred strategic implications follows.
-
Glencore (Baar, Switzerland) — A major integrated miner and trader active across nickel-copper assets and byproduct cobalt. Its diversified footprint and trading capabilities make it a pivotal swing supplier. Notably, Glencore reported full-year 2025 cobalt production of 36.1 kt, a decline versus 2024 as the company prioritized copper processing amid regional export constraints. For counterparties, Glencore’s flexibility makes it a key partner for spot and strategic purchases, but its allocation decisions can create transient supply tightness.
-
CMOC Group (Beijing, China) — A leading miner with integrated cathode and hydroxide production geared toward battery-grade markets. CMOC’s vertical integration into battery-materials production positions it as a strategic supplier for OEMs and battery manufacturers seeking secure, quality-assured feedstock.
-
Zhejiang Huayou Cobalt (Tongxiang, China) — A large refiner and precursor supplier with operations in multiple jurisdictions. Its strength lies in downstream refinement capability and established offtake relationships with battery makers; for companies requiring consistent chemical-grade material, Huayou is a go-to partner.
-
Vale S.A. (Rio de Janeiro, Brazil) — Produces cobalt as a byproduct of nickel and copper mining, offering geographic diversification to buyers. Vale’s assets provide optionality for offtake and incremental supply security outside the most concentrated mining basins.
-
BHP Group (Melbourne, Australia) — Supplies cobalt principally as a nickel byproduct and benefits from stable regulatory environments in core jurisdictions. BHP can be a strategic supplier for long-duration contracts tied to nickel-cobalt chemistry demands.
-
Rio Tinto (London, UK) — With byproduct flows from large copper operations, Rio Tinto’s role is complementary but strategically significant for customers seeking North American or diversified sourcing.
These profiles are supplemented in the full report by supplier scorecards that quantify operational scale, counterparty risk, ESG performance, and integration potential — information that underpins supplier selection and M&A screening.
Regulatory and trade environment: the 2026 playbook
Policy and trade measures have altered the operational landscape: public data show tariff adjustments and an active regulatory emphasis on traceability and import origin. Notably, recent government disclosures highlight tariff rate increases affecting ores and concentrates from certain origins and record-high mine and refinery production dynamics concentrated in a few jurisdictions. China remains the largest consumer of refined cobalt products, primarily driven by the lithium-ion battery sector, and a meaningful portion of refinery feedstock has been derived from partially refined imports from key producing countries. For corporate strategists, this means:
-
Increased compliance risk and the need to validate supply chains end-to-end.
-
Potential for sudden cost impacts due to tariff regimes or export controls that require dynamic scenario planning.
-
An incentive to localize or regionalize refining and recycling capabilities where feasible.
What’s in the full PW Consulting Cobalt Market report (operational overview)
The full deliverable is designed as a practical playbook for 2026 action, not an academic exercise. Core modules include:
-
Top-line market forecast (2026–2032) with scenario variants tied to EV adoption curves, battery chemistry transitions, and recycling uptake.
-
Supply-demand balancing by year with sensitivity runs for key shocks (export restrictions, rapid substitution, macro downturns).
-
Comprehensive supplier scorecards and a ranked watchlist for strategic partnerships or acquisition targets.
-
Price-modeling engine that decomposes landed cost by origin, processing tier, and tariff/regulatory overlay for contract negotiation support.
-
Risk matrix covering geopolitical, regulatory, ESG, technical, and reputational vectors, with mitigation playbooks.
-
Operational toolkits: negotiation templates, RFP frameworks for long-term offtake, and refinery project financial model baselines.
-
Scenario-based recommendations for OEMs, battery manufacturers, traders, and upstream miners on optimal strategies through 2032.
Immediate tactical recommendations for 2026
-
Lock in a portion of three-year supply via staggered offtake agreements to smooth price exposure while preserving spot optionality.
-
Invest in third-party supplier audits and blockchain-enabled traceability pilots to de-risk sourcing and satisfy downstream clients’ ESG demands.
-
Accelerate feasibility work on regional refining or recycling to reduce dependence on single-source refining hubs.
-
Define clear substitution thresholds and R&D milestones for cathode chemistry adjustments to keep procurement flexible.
Next steps
For executives preparing 2026 budgets, procurement strategies, or M&A pipelines, this preview should be treated as a directional roadmap. The full PW Consulting Cobalt Market report contains the actionable data feeds, segmented forecasts, supplier scorecards, and contractual templates necessary to execute the recommendations outlined here. To convert insight into advantage, access to the complete dataset and models is required — the detailed segmentation and scenario outputs are intentionally reserved to preserve their strategic value for subscribers and clients.
Contact PW Consulting to obtain the full report, interactive models, and an implementation workshop tailored to your organization’s role in the cobalt value chain.
For detailed analysis of this topic, please visit the official page: Cobalt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com