

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Electrical Insulation Paper Market Poised for 3.9% CAGR Through 2032

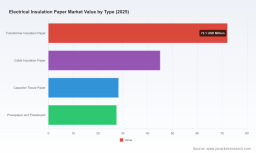
Electrical Insulation Paper Market — Strategic Preview for 2026 Decision-Makers
As energy systems, electrification programs, and industrial modernization accelerate globally, the humble but mission-critical category of electrical insulation paper is re-emerging as a strategic supply-chain and technology priority. PW Consulting’s new market research—anchored on a 2025 base year, five-year historical analysis (2020–2025) and a forward-looking forecast to 2032—translates market dynamics into decision-ready implications for procurement leaders, product strategists, and M&A teams planning for 2026.
Electrical Insulation Paper Market
Snapshot: Where the market stands and where it’s headed
Our top-line analysis shows a resilient market trajectory. After a modest dip and recovery in the early 2020s, total market revenue reached approximately USD 172.8 Million in 2025 and is projected to grow to about USD 224.9 Million by 2032. The underlying compound annual growth rate (CAGR) over the forecast window is 3.9%, reflecting steady, structurally-driven demand rather than speculative expansion.
Electrical Insulation Paper Market
These headline numbers conceal important texture: growth is being driven by a mixture of incremental replacement demand in traditional power equipment and higher-specification requirements tied to grid modernization, increased deployment of power electronics, and stricter reliability standards in distribution and transmission assets. For executives preparing 2026 budgets, the takeaway is clear—this is a market characterized by steady, technically nuanced growth that rewards manufacturers and buyers who can master quality, compliance, and cost volatility.
Electrical Insulation Paper Market
Why this report matters for 2026 strategy
- Operational resilience: The report identifies how raw-material price volatility and compliance costs translate into margin pressure. It quantifies the material sensitivity of insulation-paper production and models scenarios that show near-term cost shocks propagating through supply chains.
- Product positioning: As transformers, capacitors, and cable systems demand ever-higher dielectric performance, product differentiation (e.g., creped vs. plain grades, coated variants, thermal upgrading) becomes the primary lever for margin expansion. The study maps which technical attributes correlate most closely with premium pricing and specification wins.
- M&A and partnership targets: With a moderately concentrated vendor base (notably, top-three and top-five shares indicating room for consolidation), the research highlights pockets of fragmented supply where acquisitive players can rapidly scale technical capability and geographic reach.
- Procurement optimization: Practical roadmaps for raw-material sourcing, hedging strategies, and contract structures are included, enabling buyers to lock in supply without sacrificing flexibility amid cyclical pulp markets.
Supply dynamics and cost pressure — what to watch in 2026
Two structural themes dominate near-term economics:
- Raw-material volatility: Kraft pulp remains the principal feedstock for cellulose-based electrical insulation papers. Recent price signals—illustrated by short-term fluctuations in pulp markets—demonstrate how quickly input cost can swing. Our modeling uses observed volatility to show that insulation-paper producers can experience up to roughly 28% variation in production cost across cycles, driven primarily by pulp price movements. We also flag that cellulose-pulp prices have risen materially (single-digit to low double-digit percentage movements) in recent production cycles, a trend that episodically compresses margins unless passed through via contracts or product premiuming.
- Regulatory and compliance overlay: Environmental controls on paper processing emit additional operating costs. Regions with strict emissions rules can impose compliance burdens that add an estimated 6–11% to operational expenditure for producers. These incremental costs influence strategic choices about plant locations, capital investments in abatement technology, and vertical integration into pulp sourcing.
Segments and technical differentiation (teaser)
The market is multi-faceted: products are optimized for transformers, cables, capacitors, and rotating machines, and come in grades such as kraft flat paper, creped and coated papers, presspaper and pressboard, and specialty capacitor tissues. Each application imposes distinct mechanical and dielectric performance criteria—creping, coating, thermal upgrading, and surface finish are not cosmetic choices but design decisions that materially affect asset lifetime and failure modes.
PW Consulting’s full report provides granular performance matrices linking technical features to typical field failure modes and lifecycle costs. This is deliberately summarized here to preserve the competitive edge the full dataset delivers; decision-makers will find the detailed matrices invaluable when optimizing design-specifications for total cost of ownership rather than first-cost alone.
Competitive landscape — who matters and why
The supplier landscape blends established specialty mills and vertically integrated European players with resilient family-owned firms in local markets. Key vendors profiled in our study include firms headquartered in Switzerland, Finland, Germany, and the United States—each bringing distinct strengths:
- Quality-driven specialty mills: Several leaders focus on electrical-grade kraft pulp processing, creping, coating and value-added finishing tailored for transformer applications. Their technical documentation and controlled production environments command trust among OEMs and asset owners.
- Brand and technical-service differentiation: Some global companies pair product families with thermal upgrading or specific processing technologies under proprietary brands, enabling clearer specification pathways for high-voltage and instrument transformer markets.
- Regional specialists and niche innovators: Long-established family manufacturers and smaller companies continue to hold meaningful positions in local and legacy markets—especially where tailored product formats (e.g., glazed variants or specialty composites) are needed.
Recent market activity also demonstrates the importance of continuous product refinement: for example, a leading supplier published updated technical guidance on optimizing transformer insulation systems in March 2026, a signal that technical leadership and customer education are core competitive tools.
Strategic implications for buyers, producers and investors
- Buyers (OEMs, utilities, EPCs): Move beyond unit-price procurement. Create multi-year specification contracts that reward suppliers for quality assurance, traceability, and guaranteed dielectric performance. Include clauses that allocate raw-material-driven cost adjustments transparently to avoid surprise shocks.
- Producers: Prioritize investments in process control, thermal upgrading capabilities, and emissions abatement. These are not marginal compliance costs but strategic enablers—facilities that achieve both tight quality control and regulatory compliance unlock premium customers and geographic expansion.
- Investors and M&A teams: The market shows moderate concentration with room for consolidation. Target acquisitions that bring complementary technical capabilities (e.g., creping/coating expertise) or access to feedstock security. The most accretive deals will improve margin resilience against pulp-price cycles and regulatory costs.
What PW Consulting’s report delivers (practical contents)
- Comprehensive historic and forecast market model (2020–2032) with scenario-ready sensitivities to raw-material price swings and regulatory cost factors.
- Technical feature-to-application matrices that map product grades to performance outcomes and lifecycle economics for transformers, cables, capacitors, and rotating machines.
- Supplier benchmarking that ranks vendors on quality control, technical services, geographic coverage, and strategic strengths—plus recent commercial and technical developments.
- Operator-focused playbooks for procurement, hedging, and specification governance that reduce total cost of ownership and failure risk.
- Strategic M&A screening criteria and a shortlist of subsegments where consolidation or capability acquisition can yield high IRR in a 3–5 year horizon.
How to use this intelligence in 2026 planning cycles
Practical steps informed by the report:
- Incorporate insulation-paper cost sensitivities into capital-cost models for transformer procurements and life-cycle cost analyses for grid assets.
- Revise supplier scorecards to weight technical conformity and emissions-compliance capabilities more heavily than price alone.
- Negotiate multi-year supply agreements with indexed cost pass-throughs and quality milestones to stabilize manufacturing throughput for both buyers and sellers.
- Prioritize investment cases for plants or upgrades that reduce exposure to pulp-price shocks and regulatory compliance risk—these investments often pay back through access to premium contracts.
Concluding perspective and next step
Electrical insulation paper is no longer a commodity relegated to procurement checklists—its quality, availability, and cost dynamics materially influence transformer reliability, capacitor performance, and the economics of power asset fleets. The market’s 3.9% forecast CAGR and the path from roughly USD 172.8 Million in 2025 toward USD 224.9 Million in 2032 indicate steady demand growth, but the real strategic battleground is margin resilience: mastering raw-material volatility, regulatory compliance, and technical differentiation.
PW Consulting’s full study contains the granular tables, country-level forecasts, product-grade economics, and supplier performance metrics that organizations need to convert this insight into 2026 action. For procurement teams, product strategists, and investors preparing budgets and deal pipelines this year, the report functions as both a risk-heatmap and an opportunity playbook.
Contact PW Consulting or visit the report landing page to access the full dataset and obtain a tailored briefing for your organization’s 2026 planning cycle. The executive summary here outlines the strategic contours—our full deliverable gives you the precise, source-level intelligence required to act with confidence.
For detailed analysis of this topic, please visit the official page: Electrical Insulation Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com