

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Sodium Permanganate Market to Grow at 4.6% CAGR Through 2032

Sodium Permanganate Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a focused, decision-grade briefing on the sodium permanganate market that frames the strategic choices organizations will face in 2026. This market is no longer a niche chemical business insulated from broader industrial trends — it sits at the intersection of water infrastructure, semiconductor and electronics manufacturing, and evolving battery- and critical-materials policy. The briefing that follows synthesizes our market sizing, competitive mapping, supply-chain stress testing, and scenario-driven recommendations. It is designed to signal the levers that matter to procurement, commercial strategy, operations, and M&A teams while deliberately withholding full segment-level detail to encourage access to the full PW Consulting report.
Sodium Permanganate Market
Market snapshot: scale, trajectory, and concentration
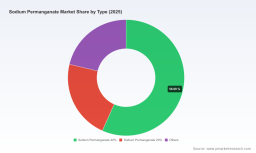
Using 2025 as the base year, our topline market model values global sodium permanganate demand at approximately USD 357.7 Million (USD Million). The market is projected to expand to roughly USD 379.9 Million in 2026 and to approach USD 488.0 Million by 2032, implying a compound annual growth rate (CAGR) of 4.6% over the 2026–2032 forecast horizon. These figures reflect a steady expansion driven by sustained municipal water-treatment procurement, growth in specialty industrial applications, and incremental gains in electronics and high-purity use cases.
Sodium Permanganate Market
Market structure matters: the industry shows a high degree of concentration (CR3 ≈ 70%; CR5 ≈ 75%), which shapes competitive dynamics, pricing behavior, and the speed at which supply shocks are transmitted to end markets. For corporate decision-makers, this concentration implies that a relatively small set of incumbent suppliers will continue to set commercial norms — but it also creates pockets of opportunity for differentiated entrants and vertically integrated players.
Sodium Permanganate Market
Why 2026 is a pivotal year for strategic choices
- Procurement inflection: Recent upstream volatility has shortened suppliers’ planning cycles and increased the value of contract certainty. Buyers who act early to secure flexible, indexed contracts will reduce margin exposure.
- Regulatory realignments: New critical-materials rules and public investment programs are shifting the economics of manganese sourcing and downstream processing, creating both compliance burdens and investment incentives.
- Demand mix evolution: While water treatment remains the backbone of demand, higher-value segments — notably electronics and research-grade supplies — are growing faster and require different quality, packaging, and service models.
Key market dynamics shaping 2026 decisions
- Raw material tightness and cost pass-through: Price volatility at the manganese sulfate and ore level has become a persistent theme. Q1 2026 data showed a notable quarter-over-quarter uptick in manganese sulfate pricing linked to rising sulphuric acid costs. That spike, combined with legacy supply disruptions (for example, mine suspensions following severe weather events in 2024), has amplified input-cost transmission into finished sodium permanganate prices.
- Policy and strategic-materials pressure: The European Union’s Critical Raw Materials Act (effective May 2024) explicitly flagged high-purity manganese as strategic, creating compliance and sourcing implications for anyone competing in EU markets. At the same time, U.S. Department of Energy and Department of Defense grant programs supporting domestic battery-grade manganese production are altering the competitive landscape for manganese feedstocks, potentially diverting material and investment into the battery supply chain.
- Public procurement as a demand anchor: Municipal tendering remains a stable and predictable revenue channel for certified suppliers. Recent public awards — exemplified by a municipal contract award in March 2025 — underscore the premium placed on certifications (e.g., NSF, AWWA), logistics reliability, and compliance documentation.
Supply chain and margin levers
Our scenario analysis highlights three levers that determine supplier and buyer outcomes through 2026:
- Sourcing strategy: Vertical integration into manganese sulfate conversion or long-term offtake agreements can buffer margin swings but require capital and lead time.
- Product differentiation: Certification, purity grading, and service (e.g., just-in-time deliveries, on-site dosing solutions) create defensible pricing tiers, especially for municipal and electronics customers.
- Contract design: Indexed pricing with caps/floors and blended-term structures reduces the probability of one-sided shocks while preserving supplier economics.
Competitive landscape — strategic positioning and implications
The market is populated by incumbent suppliers that follow distinct routes to competitive advantage. Below is a synthesis of the strategic posture of core industry players covered in our research.
- Carus Corporation (Peru, Illinois) — A major U.S. producer with a strong focus on water-treatment liquid grades and recognized certifications. Carus’s strengths lie in scale, certification credentials, and a deep municipal-sales footprint. Strategy implication: Carus is well positioned to defend municipal share and expand into adjacent treatment services; competitors should consider niche specialization or superior service models to counteract its scale.
- Hawkins, Inc. (Roseville, Minnesota) — A domestic manufacturer, blender, and distributor focused on municipal and government contracts through B2B channels. Hawkins’s distribution-centric model emphasizes localized supply and contract flexibility, a differentiator in municipal procurement cycles.
- Valudor Products, LLC (Encinitas, California) — A supplier of certified 40% solution grades with complete safety and compliance documentation. Valudor’s emphasis on certified formulations and documentation makes it a natural supplier to regulated water-treatment buyers and specialty industrial users.
- American Elements (Los Angeles, California) — Provider of very high-purity sodium permanganate grades targeting research, electronics, and high-end industrial customers. Their product focus allows premium pricing but requires tight quality controls and traceability.
- Rock Chemicals, Inc. — A bulk supplier that differentiates on reliable sourcing, compliance documentation, and logistics. Rock is attractive to buyers seeking scale purchasing and straightforward compliance support.
Collectively, these players illustrate three viable strategic archetypes: scale/certification (large incumbents), distribution-led reliability (regional blenders/distributors), and quality-differentiation (high-purity specialists). Our competitive scorecards in the full report benchmark each against CAPEX plans, certification breadth, and logistics resilience.
Strategic playbook for 2026
Below are actionable recommendations tailored to different organizational roles — buyers, producers, and investors — grounded in our market modeling and stress tests.
- For buyers and municipal procurement teams: Revisit sourcing cadence and contract design. Prioritize suppliers with dual strengths in certification and logistics. Build 12–18 month buffer inventories for critical projects and negotiate indexed, two-way price adjustment mechanisms tied to transparent input-cost proxies.
- For producers and distributors: Accelerate investments that raise barriers to entry — NSF/AWWA certifications, high-purity production lines for electronics, and traceable sourcing agreements. Consider selective vertical integration into manganese sulfate processing or structured partnerships with miners to manage feedstock risk.
- For investors and corporate development: Look for bolt-on opportunities that add either certification capabilities or localized logistics footprints. The concentrated supplier base presents M&A potential, but diligence must stress test feedstock exposure and regulatory compliance readiness, particularly for EU market access.
What PW Consulting’s full report provides (practical deliverables)
- Granular market model (2020–2032) with base-year 2025 calibration, scenario runs, and sensitivity matrices.
- Segmented demand analysis by region, grade, and application with adoption curves and forecasted unit consumption patterns (note: detailed segment tables are only available in the full report).
- Supplier scorecards covering certification breadth, capacity, contract history, and logistical strengths, plus a CR3/CR5 concentration assessment.
- Raw-material flow maps, stress-test results (including the impacts of manganese sulfate price shocks), and mitigation playbooks for buyers and sellers.
- Contract templates, procurement negotiation checklists, and a shortlist of strategic M&A targets aligned to three archetypal buyer/investor strategies.
Closing—why this matters for your 2026 agenda
Decisions made in 2026 around contracting, capacity investments, and certification will determine who captures the upside of the projected 4.6% CAGR through 2032 and who remains exposed to raw-material and regulatory dislocations. The concentrated nature of the market rewards strategic clarity: incumbents can protect margins through certification and logistics; new entrants must pursue either niche quality premiums or stronger supply-chain control to scale.
For executives preparing 2026 plans, the most valuable near-term actions are pragmatic: secure flexible supply terms, prioritize certifications demanded by large public buyers, and align capex to segments showing above-average growth in our forecasts. PW Consulting’s full Sodium Permanganate Market report operationalizes these priorities with the models, templates, and supplier analytics needed to convert insight into measurable outcomes.
To access the full dataset, including segment-level shares, price forecasts, and supplier scorecards, please refer to the complete PW Consulting report. The executive-level summary above is intentionally high-level — it surfaces the structural risks and strategic levers without disclosing the proprietary segment splits and microdata that underpin our proprietary conclusions.
For detailed analysis of this topic, please visit the official page: Sodium Permanganate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com