

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Hard Coating Film Market Outlook: 6.44% CAGR to USD 1,116M by 2032 – PW Consulting

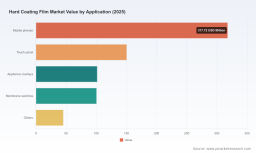
Hard Coating Film Market 2026: Strategic Imperatives for Decision-Makers
As companies prepare strategy and capital allocation plans for 2026, the hard coating film market presents a blend of steady growth, concentrated pockets of technological differentiation, and rising regulatory and materials complexity. Our PW Consulting market model pegs the industry at USD 715.0 Million in the base year (2025) and projects a clear expansion through the 2026–2032 forecast window, consistent with a compound annual growth rate of approximately 6.44%. This trajectory translates into a mid‑single‑digit growth path that rewards timely investments in product innovation, supply-chain resilience, and targeted go‑to‑market plays.
Hard Coating Film Market
Why this research matters for 2026 decisions
-
Timing of capacity and product launches: The market’s steady CAGR means capital deployment must be selective — favoring projects with differentiated IP, scalable manufacturing economics, and near-term OEM qualification paths. Firms that move from lab innovation to certified volume production in 2026 position themselves to capture disproportionate share as demand converts from prototypes to mainstream designs.
Hard Coating Film Market -
Technology inflection points: Display trends (foldable and flexible form factors), automotive interior/heads‑up displays, and medical device demands are shifting technical requirements toward multilayer coatings, self‑healing chemistries, and dual‑function surface treatments (e.g., anti‑glare + anti‑fingerprint). Our analysis highlights where first‑mover advantage matters and where incremental improvements will be table stakes.
Hard Coating Film Market -
Regulatory and procurement gating: Safety and biocompatibility standards (e.g., ANSI Z87.1 for specific applications, ISO 10993 for medical devices) and chemical compliance regimes (RoHS, REACH) materially affect supplier selection and qualifying timelines. Procurement teams must bake these regulatory milestones into supplier scorecards and R&D roadmaps in 2026.
-
Competitive positioning: The market shows moderate concentration — leadership clusters exist, but no single incumbent dominates. Our CR analysis indicates enough fragmentation to allow well‑executed entrants to scale quickly through targeted partnerships and differentiated value propositions.
Market dynamics executives must internalize
The hard coating film market is evolving from a materials problem into an integrated solution business where chemistry, substrate selection, laminating processes, and application engineering converge. Key dynamics to prioritize:
-
Application convergence: Electronic displays, touch panels, and consumer electronics still underpin demand, but automotive interiors, medical devices, and industrial hardware are increasing share of wallet for suppliers that can meet durability, optical, and regulatory thresholds.
-
Material supply and upstream partnerships: Polyester and polycarbonate substrates remain strategic inputs. Leading chemical suppliers and film producers are increasing coordination with coating formulators to secure upstream feedstocks and to accelerate scale‑up of functional films.
-
Performance layer innovation: Self‑healing coatings, multilayer stacks for foldables, and hybrid functional surfaces (e.g., anti‑glare plus anti‑fingerprint) are moving from demonstration to volume. These technologies demand new qualification protocols and often longer lead times for OEM acceptance.
-
Sustainability and process chemistry: Water‑based coating lines, solvent‑free chemistries, and lifecycle considerations are becoming procurement filters for Tier‑1 OEMs, particularly in automotive and medical categories.
Four strategic plays for 2026
-
Invest selectively in differentiated IP and scale economics — Not all capacity is equal. Prioritize investments that reduce unit cost while protecting differentiation (e.g., unique self‑healing formulations or verified multilayer stacks for flexible displays). Capital plans should include phased ramps tied to OEM qualification milestones to minimize stranded capacity risk.
-
Lock upstream and downstream partnerships — Secure substrate and chemical supply through long–term agreements or co‑development arrangements with major upstream suppliers; simultaneously, create OEM pilots that validate end‑to‑end performance. This reduces time‑to‑qualification and shields margins from raw‑material volatility.
-
Modular product portfolios — Offer core hard‑coated film platforms that can be configured via surface treatments (anti‑fingerprint, anti‑glare, antimicrobial, self‑healing) to meet divergent vertical needs. This modularity reduces SKU proliferation and accelerates OEM integration.
-
Embed regulatory readiness into go‑to‑market playbooks — For medical, automotive, and industrial applications, prepare pre‑emptive compliance dossiers (biocompatibility, chemical compliance, optical standards). Being “qualification‑ready” is a commercial advantage that shortens procurement cycles.
Competitive landscape — who is shaping the market
The competitive map blends specialized coating houses, large diversified materials groups, and regional scale players. A non‑exhaustive, representative set of firms illustrates the range of strategic postures:
-
Specialized innovators: Companies that focus on precision optical and functional coatings for displays and medical applications, offering proprietary hardness and ultra‑thin formats. These players differentiate on technical depth and OEM servicing.
-
Large materials groups: Diversified chemical and film producers that are developing multilayer systems for next‑generation displays and automotive use cases, often pairing coating science with substrate expertise and broader distribution networks.
-
Regional scale suppliers: Firms leveraging roll‑to‑roll processing efficiencies and localized service models to serve fast‑growing consumer electronics assembly hubs.
Notable companies characterized in our competitive analysis include leaders in precision optical coatings, multilayer and flexible film systems, dual‑function surface technologies, self‑healing chemistries, and regional coatings specialists. Each profile includes corporate strategy, technical capabilities, geographic orientation, and recent strategic moves — ranging from capacity expansion and product launches to expanded distribution agreements and volume deployments. These profiles illuminate replication risk and partnership opportunities alike.
Supply‑chain and regulatory checklist for 2026
-
Map critical upstream exposures: Identify single‑source risk for specialty resins and functional monomers, and quantify the lead times for qualification of substitute chemistries.
-
Build compliance slates early: Align product design with ANSI, ISO, RoHS/REACH, and medical biocompatibility standards to avoid last‑mile rejection by OEMs.
-
Plan for intelligent sourcing: Consider co‑development or toll‑coating arrangements in key regions to reduce logistics friction and accelerate OEM approvals.
-
Design quality economics: Invest in in‑line metrology and accelerated lifetime testing to validate self‑healing and multilayer performance at scale.
What the PW Consulting report delivers (practical takeaways)
Our full Hard Coating Film Market study combines quantitative forecasting with hands‑on, executable guidance for executives planning 2026 strategies. Highlights include:
-
Market sizing and demand model calibrated to 2020–2025 historicals and a 2026–2032 forecast horizon — enabling scenario analysis for conservative, base, and accelerated adoption curves.
-
Segment mapping by substrate, coating type, and application with supplier benchmarking and qualitative adoption trajectories — structured to support commercial and technical decision‑making.
-
Technology deep dives covering self‑healing chemistries, multilayer constructions for foldables, and dual‑function surface treatments — including validation approaches and OEM qualification pathways.
-
Practical go‑to‑market playbooks and procurement scorecards: supplier shortlists, qualification templates, and ramp‑to‑volume checklists for 2026 execution.
-
Three investment cases (conservative, base, upside) tied to entry options: greenfield capacity, toll coating partnerships, and licensing/co‑development — each with expected breakeven windows and sensitivity to raw‑material pricing and OEM adoption timing.
How to use this intelligence in your 2026 planning cycle
-
Boardroom readiness: Use the market model to stress‑test CAPEX requests — link each tranche of spend to concrete OEM milestones and compliance gates.
-
R&D prioritization: Allocate R&D budgets to technologies with the shortest path to qualification for target verticals (e.g., automotive HUDs vs. consumer foldables) and to chemistries that reduce lifecycle costs or improve sustainability metrics.
-
Commercial alignment: Integrate product modularity into sales engineering material so that channel partners and OEM customers can rapidly prototype and qualify configurations.
-
M&A and partnerships: Identify acquisition targets that provide missing capabilities (e.g., self‑healing formulations or specific functional surface treatments) and consider structured earn‑outs tied to volume milestones.
Closing perspective and next steps
The hard coating film market in 2026 rewards disciplined execution more than broad bets. The sector’s steady growth and increasing technical requirements create room for both high‑margin niche specialists and scaled producers that can integrate substrate and coating value chains. Short‑term winners will be those who (1) secure upstream inputs, (2) demonstrate rapid OEM qualification, (3) build modular product platforms, and (4) embed regulatory readiness into product roadmaps.
PW Consulting’s full report provides the granular segmentation, supplier scorecards, and actionable templates that senior leaders need to convert 2026 planning into executed outcomes. For decision‑makers who require the detailed splits, supplier matrices, and the complete scenario model — including downloadable financial templates calibrated to our base and upside forecasts — please access the full Hard Coating Film Market report on the PW Consulting research portal.
For detailed analysis of this topic, please visit the official page: Hard Coating Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com