

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Transformer Oil Market to Hit USD 3,905 Million by 2032 at 6.5% CAGR

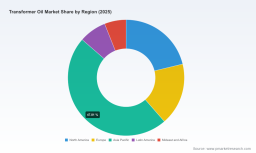
Transformer Oil Market: Strategic Imperatives for 2026
As power systems evolve — driven by electrification, renewables, urbanization and tighter energy-efficiency mandates — the transformer oil market is moving from a commoditized backwater into a strategically important input for utilities, OEMs and industrial buyers. PW Consulting’s latest Transformer Oil Market study (base year 2025; forecast 2026–2032) synthesizes five years of historical behaviour with forward-looking scenario analysis to deliver the market intelligence executives need to set resilient, opportunity-focused strategies for 2026.
Transformer Oil Market
Macro snapshot you can act on
Our market model places the global transformer oil market at USD 2,530 Million in 2025, growing at a compound annual growth rate (CAGR) of 6.5% through the 2026–2032 forecast window, reaching roughly USD 3,905 Million by 2032. Those headline dynamics mask important second-order forces: raw material price volatility, regulatory tightening on energy performance and hazardous substances, and an accelerating shift toward ester, bio-based and circular fluids in specific high-value use cases. The full report translates this macro trajectory into decision-ready scenarios — from conservative procurement hedges to aggressive product and M&A playbooks — without exposing the proprietary segment-level data you’ll find in the paid study.
Transformer Oil Market
Why 2026 is a strategic inflection point
-
Regulatory acceleration: Since early 2025 the EU introduced stricter energy performance and greenhouse gas reduction requirements for transformers, raising the bar for dielectric fluids’ thermal and oxidative performance. Concurrently, legacy regulatory rules (for example, EPA TSCA requirements that require incineration for oils with PCB concentrations above specified thresholds) continue to impose disposal and remediation costs that change total cost of ownership calculations for older assets.
Transformer Oil Market -
Input-cost shocks and supply-side repricing: Base oil prices have shown renewed upward pressure — with reported US base oil prices around USD 1,842/MT in March 2026 — and crude volatility historically translating into rapid cost shifts. These dynamics compress margins on commodity mineral oils while improving the economics of premium, long-life fluids that lower lifecycle maintenance and replacement spending.
-
Market consolidation and buyer leverage: The market exhibits a moderate concentration profile (CR3 ~46.3%; CR5 ~61.2%), creating a structure where leading suppliers exert meaningful influence over product innovation, certification pathways and supply chain arrangements — but also where differentiated, sustainable products can carve premium niches.
Competitive landscape: where capability meets strategy
The competitive map is a mix of global majors with deep logistics and R&D footprints, regional specialists with application-specific expertise, and emerging leaders in sustainable fluids. Key supplier archetypes identified and profiled in the report include:
-
Innovation-led incumbents: European and multinational players have pushed premium grades, certification frameworks and circular initiatives. Recent commercial and deployment news underline this trend — for example, the uptake of circular transformer oils by OEMs and factory-level deployments in 2026 highlights how sustainability credentials are moving from pilot to production readiness.
-
Regional scale players: Large refiners and chemical groups supply base mineral grades at scale for domestic markets and exports, using integrated supply chains to preserve cost advantage. Their strength in price-sensitive segments coexists with an increasing focus on compliance and certification.
-
Niche specialists: Producers of natural esters and re-refined oils are building selective advantages in urban substations, offshore wind, and other fire-sensitive or sustainability-conscious applications. These suppliers often combine technical testing support with field qualification programs tailored to utilities and OEMs.
Full company profiles in the report unpack go-to-market strategies, technology differentiators, certification footprints and recent commercial developments for leading players — enabling buyers to match supplier capabilities to specific asset strategies and procurement levers.
Operational levers and strategic playbook for 2026
PW Consulting recommends a prioritized set of actions for corporate decision-makers, organized by horizon and informed by stress-tested scenarios in the full report.
-
Immediate (0–6 months) — Harden procurement and compliance. Implement hedging and flexible contracting tied to base oil indices; audit aging transformer fleets for PCB risk and disposal cost exposure; and fast-track qualification of at least one circular or natural-ester fluid as a pilot for high-value substations.
-
Near-term (6–18 months) — Shift product and capital allocation. Reallocate OPEX/CAPEX toward long-life fluids where lifecycle cost models justify higher unit prices; invest in in-situ testing capability; and establish recycling partnerships or off-take agreements with re-refiners to reduce disposal risk and capture circular premiums.
-
Mid-term (18–36 months) — Reconfigure supplier networks and M&A scouting. Pursue bolt-on acquisitions or strategic JV arrangements to secure niche ester or re-refining capability; renegotiate supply terms based on total-cost-of-ownership metrics; and embed regulatory scenario triggers into capital planning for new transformer builds.
Risk management and scenario analysis you can use
The report includes sensitivity matrices showing how +/-10–30% swings in base oil costs, varying adoption curves for ester fluids, and differentiated regulatory paths affect price, margin and NPV for buyers, suppliers and investors. It also provides a practical risk heatmap focused on supply disruption, regulatory penalties, certification delay, and reputational exposure from non-compliant disposal. These tools convert headline CAGR and market-size projections into actionable thresholds for contract clauses, inventory policy and capital allocation.
Actionable contents of the full study (high level)
-
Proprietary market model (2020–2025 historical; 2026–2032 forecast) with scenario toggles for price shocks, regulatory regimes and adoption curves for alternative fluids.
-
Supplier benchmarking and capability maps, including certification matrices, regional logistics strength and technical validation timelines.
-
Procurement playbook and sample contractual language for indexation, quality warranties and circular off-take agreements.
-
Lifecycle cost calculators and field-qualification protocols for mineral, synthetic and bio-based fluids.
-
M&A and partnership targets: screening criteria and shortlist derived from market concentration analytics and technology readiness levels.
-
Regulatory impact assessment covering PCB disposal rules, EU energy-performance measures, recent duty changes affecting trade flows, and recommended compliance pathways.
To honour the “preview” purpose of this article, we intentionally withhold proprietary granular splits and segment-by-region revenue tables; the full study includes detailed segmentation and quantitative matrices that power the tactical recommendations above.
Signals to watch in 2026
-
Certification and factory deployments: Major OEMs integrating circular and ester fluids into production lines will be an early indicator that field adoption is becoming de‑risked.
-
Raw-material and index behaviour: Sustained high base oil prices or renewed crude volatility will accelerate buyer interest in longer-life, higher-margin fluids.
-
Regulatory shifts: Any tightening of energy-performance or hazardous-waste rules materially changes lifecycle economics for legacy oils, increasing conversion activity.
-
Competitive moves: M&A by majors to acquire re-refining or ester capabilities will compress time-to-market for circular products and alter supplier bargaining dynamics.
What this means for executives
For procurement leaders, the decision calculus in 2026 must move beyond unit price to lifecycle value: qualification timelines, disposal costs, and supplier sustainability credentials will determine true TCO. For product and R&D leaders, allocating resources to ester and circular chemistry — plus the validation infrastructure to shorten qualification cycles — offers a high-return hedge against both regulation and raw material inflation. For corporate strategists and deal teams, the market’s moderate concentration suggests attractive pick-and-build opportunities to stitch regional scale to differentiated products.
PW Consulting’s Transformer Oil Market study converts the headline growth path (USD 2,530 Million in 2025 growing at 6.5% CAGR to 2032) into a clear sequence of choices: where to protect margins, where to innovate, and where to consolidate. The actionable tools in the full study — scenario models, procurement playbooks, supplier scorecards and target lists — are designed to be executed against a 2026 planning calendar.
Next steps
If you are preparing budgets, portfolio plans or acquisition screens for 2026, PW Consulting offers executive briefings and custom modelling workshops that use the report’s underlying data and scenario engines to produce bespoke recommendations for your asset base and strategic priorities. For access to the full segmentation, company profiles, and the quantitative annex that underpins the recommendations in this preview, please visit our report page or contact our industry team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Transformer Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com