

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: PVB Film Market to hit USD 344.8M by 2032 at 6.98% CAGR

PVB Film Market Outlook — Strategic Imperatives for 2026 Decision Makers
As PW Consulting’s lead industry strategist, I present a forward-looking briefing drawn from our new PVB Film Market study — an operationally focused intelligence product designed to inform boardroom decisions in 2026. This executive “trailer” synthesizes the macro trajectory, competitive shifts, and strategic levers that will determine winners and laggards in laminated interlayers over the next investment cycle. It intentionally surfaces the analysis framework and actionable takeaways while withholding granular segment and regional splits to encourage direct access to the full dataset and model.
PVB Film Market
Executive snapshot: growth, structure, and pace
The global PVB film market reached a material scale by the 2025 base year and, after pandemic-era volatility, is positioned for steady expansion through our forecast window. Our topline model projects a compound annual growth rate of approximately 6.98% from the 2026 base into the 2032 horizon, reflecting sustained demand across safety glass, architectural innovation, and emerging photovoltaic applications. The market is also structurally concentrated: the three largest suppliers command the majority of market influence, and the top five players consolidate most commercial capacity — a dynamic that creates both stability and strategic friction for newcomers and mid-market producers.
PVB Film Market
Why this study matters for 2026 strategic choices
- Capital allocation timing: With mid-single-digit CAGR and visible policy-driven tailwinds for sustainable materials, the next 12–24 months are pivotal for committing greenfield expansions, retrofitting lines for recycled-content PVB, or negotiating offtake terms. Missed timing reduces the optionality premium embedded in later-cycle demand surges.
- Supply-chain positioning: Inputs and energy are major drivers of margin variability. Our report quantifies raw-material exposure and offers hedging and supplier-contract archetypes that protect margin without forfeiting growth.
- Product roadmap alignment: Innovations in stiffness, optical effects, and recycled-resin content are already reshaping procurement specifications across automotive and architectural OEMs. Firms that translate material technology into validated safety and aesthetic claims will capture premium pricing bands.
- M&A and partnerships: High concentration creates opportunities for bolt-on consolidation, regional capability plays, and joint ventures that provide rapid access to certification and OEM contracts. The report’s candidate-screening engine accelerates target identification based on technological fit and balance-sheet thresholds.
- Regulatory and ESG compliance: Certification regimes and decarbonization mandates materially affect contract viability. Early certification (or rapid roadmap implementation) for recycled-content and low-carbon production de-risks long-term revenue and unlocks sustainability-linked incentives.
Demand drivers and supply dynamics — what to watch in 2026
Three convergent forces underpin the market’s trajectory:
PVB Film Market
- End-market innovation: Automotive safety regulations, architectural design trends favoring large-format glazing and minimal profiles, and nascent PV module laminates are each expanding technical requirements for interlayers. These use-cases place different emphases on optical clarity, structural stiffness, and durability — pressuring producers to broaden product portfolios or specialize for higher-margin niches.
- Sustainability and certification: Buyers and regulators are accelerating material-quality demands. Industry-leading suppliers have already announced recycled-content PVB offerings and secured third-party sustainability certifications, creating a bifurcated market between certified low-carbon products and conventional grades. Certificate-backed supply is becoming a procurement precondition for major OEMs and façade contractors.
- Raw material and energy volatility: Cost exposure is non-trivial — key feedstocks and energy inputs can swing margins sharply. Some producers are actively deploying derivatives and long-term procurement contracts to smooth cost profiles; others remain exposed, creating differentiated margin outcomes that will show up in financial results and competitively significant pricing moves.
Competitive landscape — capabilities, bets, and recent moves
The market’s leading players combine global manufacturing footprints, brand recognition, and long-term OEM relationships. Four archetypes illustrate strategic divergence:
- Global integrators — Firms that combine resin production, interlayer manufacture, and multi-market distribution. These players leverage scale to invest in certification, recycled-content offerings, and regional service models that OEMs require for just-in-time supply.
- Product innovators — Companies focused on differentiated interlayers (e.g., enhanced stiffness, visual effects) that command specification preference in architectural marquee projects and safety-critical automotive applications.
- Regional specialists — Producers that concentrate assets in select geographies to serve local energy, regulatory, or logistics advantages; they are attractive partners or acquisition targets for global players seeking faster market entry.
- Niche premium brands — Small but high-margin firms that target design-oriented architectural projects with unique finishes and optical effects.
Recent commercial moves illustrate these archetypes in action: several major suppliers have commercialized next‑generation interlayers with improved structural performance and novel aesthetic finishes. Others have announced low‑carbon product variants that incorporate recycled resin inputs and/or migrate production to renewable energy sources. Certification wins and product launches in 2024–2025 signal that sustainability credentials and technical differentiation will be decisive procurement filters in 2026.
Operational implications: procurement, manufacturing, and R&D
For commercial and operations leaders, the study translates macro insights into specific levers:
- Procurement redesign: Move from spot buying to blended contracting: a mix of long-term fixed-price supply for critical feedstocks, indexed volumes for flexibility, and optionality for recycled-content streams. The report provides contract templates and elasticity curves to quantify the trade-offs.
- Manufacturing roadmaps: Prioritize retrofits that enable higher recycled-content runs without sacrificing optical quality, and modularize investments so scale can be accelerated if demand trajectories exceed base-case assumptions.
- Product differentiation: Invest in a tiered product architecture — standard grades for cost-sensitive volumes, high-performance grades for margin capture, and certified low-carbon SKUs for sustainability-driven tenders.
- Channel and service models: OEMs increasingly value certified, traceable supply chains and product-testing support. Building capabilities in technical support, on-site testing, and logistics reliability is a low-cost route to win share.
Scenario thinking: timing your moves under three plausible futures
Our forecast framework uses a three-scenario approach to stress-test timing decisions:
- Base Case (reference): Reflects continued mid-single-digit expansion driven by steady automotive and architectural demand and measured adoption in PV applications. This scenario supports deliberate capacity additions phased against validated offtake.
- Sustainability Upside: Accelerated policy adoption and rapid OEM procurement shifts toward certified recycled-content and low-carbon PVB. Under this path, early movers with certified supply unlock premium price realization and faster volume growth — justifying earlier and larger capacity investments or strategic acquisitions.
- Downside / Volatility: Raw-material shocks, adverse currency movements, or delays in certification adoption compress margins and delay pickup in discretionary architectural projects. In this case, operational flexibility and hedging discipline preserve cash and maintain service levels while avoiding margin-diluting spot sales.
Each scenario includes triggers and tactical playbooks — the full report maps those triggers to decision gates for capital projects, procurement commitments, and M&A timelines.
What the full PVB Film Market report delivers
PW Consulting’s full study is built as a decision-support suite for executives and investors. Key deliverables include:
- Granular market model and dashboard (2020–2032) with downloadable scenarios and sensitivity toggles.
- Competitive matrix and supplier scorecards covering technology, certification, capacity, and regional footprint.
- Detailed supply-chain maps with raw-material exposure analysis and hedging strategies.
- Commercial playbooks: pricing levers, contract templates, and channel strategies tailored to OEM and architectural buyer archetypes.
- M&A and partnership shortlist methodology with candidate filters and valuation ranges (confidential annex available).
- Regulatory and certification roadmaps, including timelines and expected cost implications for certification programs relevant to low-carbon and recycled-content claims.
- Implementation roadmaps for manufacturing retrofits to accommodate recycled-content blends and high-performance grades.
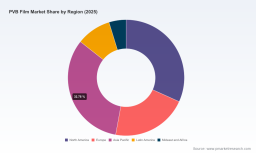
To preserve the strategic advantage for paying subscribers and corporate clients, the preview above intentionally omits detailed regional and application splits and the specific revenue breakdown by subsegment — those are provided in the interactive model and appendices of the full report.
How PW Consulting supports execution
Beyond research, PW Consulting partners with clients to translate insight into outcomes: we co-develop capex timing decisions, run procurement optimization pilots, structure JV and M&A diligence, and validate product commercialization plans with OEM procurement teams. Our modular engagement templates let clients buy only the parts they need — from a rapid 8-week market-entry feasibility to a full-scale program that embeds PW leaders in your capital approval and supply-chain negotiations.
For executives making 2026 decisions, the strategic choices are straightforward in concept but complex in execution: align product strategy with certified supply, lock cost exposure on critical feedstocks, and time capacity moves to where demand and value converge. The PVB Film Market study arms you with the quantitative models, supplier intelligence, and scenario playbooks to make those choices with conviction.
Access the full report and the interactive market model on our publications page to unlock the complete dataset, subsegment detail, and operational templates.
For detailed analysis of this topic, please visit the official page: PVB Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com