

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Pharma-Grade Sodium Chloride Market to Reach USD 630M by 2032, 5.6% CAGR (PW Consulting)

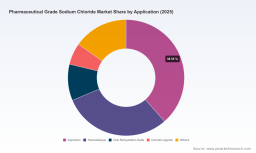
Pharmaceutical Grade Sodium Chloride Market: Strategic Primer for 2026 Decision-Makers
As healthcare systems normalize post‑pandemic and manufacturers recalibrate supply chains, pharmaceutical grade sodium chloride has re‑emerged as a quietly critical commodity underpinning therapies, diagnostics and life‑saving procedures. This primer synthesizes the key market dynamics from PW Consulting’s new study (base year 2025) and frames the concrete strategic choices executives must make in 2026. It demonstrates the analytical depth available in the full report while intentionally withholding detailed sub‑segment tables and regional breakouts to preserve the value of the underlying intelligence.
Pharmaceutical Grade Sodium Chloride Market
Market trajectory at a glance
The market for pharmaceutical grade sodium chloride has expanded steadily through the historical window (2020–2025), moving from an estimated USD 470.0 Million in 2020 to USD 525.0 Million in the base year 2025. PW Consulting’s forecast for 2026–2032 models a compound annual growth rate (CAGR) of 5.6%, projecting continued expansion to an estimated USD 630.0 Million by 2032. This secular growth is underpinned by rising procedural volumes in mature health systems, expanding dialysis and injectable drug markets in growth regions, and an elevated emphasis on pharmaceutical‑grade raw materials driven by regulatory scrutiny and patient safety demands.
Pharmaceutical Grade Sodium Chloride Market
Why this matters for 2026 strategic planning
-
Supply resilience is no longer optional. The 5.6% forecast CAGR implies meaningful incremental demand that will collide with constrained processing capacity and quality‑assured supply chains. Firms that secure validated, multi‑sourced supply lines and invest in buffer inventories will avoid margin‑eroding disruptions.
Pharmaceutical Grade Sodium Chloride Market -
Quality and compliance are premium drivers. Regulatory expectations for pharmaceutical excipients and APIs are tightening. Manufacturers and contract buyers must architect traceable processes, third‑party audit readiness and documentation ecosystems that differentiate their products in tender processes.
-
Commercial negotiations will hinge on value‑added services. Buyers are increasingly purchasing “assurance” — validated supply, chain transparency, and packaging/sterilization options — not simply commodity salt. Suppliers that bundle technical support, certification, and logistics will command better economic terms.
-
Medium‑term investment choices (2026–2028) are pivotal. Decisions on capacity additions, greenfield vs brownfield projects, and automation will determine market positioning for the majority of the forecast period. PW Consulting’s scenario models show that early movers who calibrate capacity to projected demand corridors capture disproportionate share with limited price concessions.
Data‑driven implications for different business functions
-
Procurement: Shift from single‑source contracts to a tiered, qualification‑based supplier portfolio. Introduce contractual KPIs for lead times, batch release, and recall response, and price mechanisms that reflect service components.
-
Manufacturing & Quality: Prioritize investments in analytical capacity (impurity profiling, particulate monitoring) and batch release automation. Prepare for increased regulatory audits and expand documentation control to support cross‑border distribution.
-
Commercial: Reframe value propositions — sell risk mitigation and compliance as much as volume. Tender strategies should weigh lower unit costs against supplier resilience and service guarantees.
-
M&A & Corporate Development: The market’s moderate concentration profile creates opportunities for bolt‑on acquisitions that expand geographic coverage, technical capabilities, or API credentials.
Report highlights — what the full study delivers (practical, deal‑ready outputs)
-
Demand forecasting and scenario planning for 2026–2032 with sensitivity analyses across macro, regulatory and clinical adoption levers.
-
Detailed supplier assessment framework and benchmarking templates to expedite vendor qualification and risk scoring.
-
Commercial playbooks tailored to buyers and sellers: tender construction, price indexation clauses, and logistics optimization strategies.
-
Capex decision support: cost‑benefit models for capacity expansion, including break‑even timelines under conservative and aggressive demand scenarios.
-
Regulatory & quality readiness checklist aligned to FDA, EMA and major emerging market authorities, enabling faster market entry and fewer audits.
-
Consumer safety and sustainability pathway: roadmaps to reduce carbon intensity of salt production, water management best practices, and end‑to‑end traceability blueprints.
Competitive landscape — contours and strategic moves
The pharmaceutical grade sodium chloride market remains fragmented by design: a mix of global chemicals companies, regional salt specialists and life sciences suppliers. Aggregate concentration metrics indicate that leading groups do not overwhelmingly dominate — a structural feature that preserves negotiation leverage for well‑organized buyers and creates acquisition openings for strategic consolidators.
-
K+S Aktiengesellschaft (Germany): A vertically integrated player with deep experience in mining and processing. Their strengths are consistent raw material access and scale in bulk operations. Strategic focus for 2026 should be on converting industrial scale into pharma‑grade throughput via enhanced purification lines and pharmaceutical QA systems.
-
Nouryon (Netherlands): A specialty chemicals incumbent with global distribution and technical service capabilities. Nouryon’s advantage lies in formulation know‑how and regulatory familiarity — assets that facilitate partnerships with injectable and dialysis solution manufacturers.
-
Tata Chemicals Ltd. (India): A low‑cost producer with regional reach and experience across food and industrial sectors. For 2026, opportunities include upgrading facilities to meet pharma GMP, and leveraging domestic contract manufacturing growth.
-
Dominion Salt Ltd. (Canada): A producer whose market position is strengthened by regional logistics and stable feedstock. Their strategic play is to offer near‑market supply resilience and to target adjacent life‑science customers requiring tight lead times.
-
Cargill (Salt Business, USA): A global CPG and ingredient giant with strong customer relationships across healthcare and nutrition. Cargill’s distribution network and quality systems enable it to be a preferred supplier for multinational pharmaceutical manufacturers.
-
Salinen Austria AG & Sudsalz GmbH (Austria & Germany): European salt specialists with longstanding production assets. Their niche is high‑purity crystalline salt and regional regulatory know‑how — attractive to European pharma customers prioritizing short, controlled supply chains.
-
Cheetham Salt (Australia) & Compass Minerals (USA): Producers with logistics and bulk supply advantages. Their strategic differentiation rests on export capabilities and the ability to serve both industrial and pharma verticals by dedicating GMP lines.
-
Swiss Saltworks: A smaller, specialty supplier able to offer tight traceability and tailored packaging solutions for sensitive applications.
-
Merck KGaA & Spectrum Chemical (Germany & USA): Life‑science oriented suppliers that bridge commodity supply and application support. They possess distribution channels into clinical and research labs, making them credible partners for high‑margin pharma uses.
-
Hubei Xingfa Chemicals Group (China): A high‑volume producer with strong manufacturing scale. Their growth vector is serving local API and contract manufacturing hubs while investing selectively in GMP upgrades for export markets.
Across these players, three strategic fault lines define competition in 2026: (1) quality and compliance versus cost leadership, (2) global scale and distribution versus regional responsiveness, and (3) sustainable production credentials as a differentiator for sophisticated buyers.
Recommended strategic moves for 2026
-
For suppliers: Prioritize certification roadmaps (GMP, ISO and client‑specific standards), modularize capacity to support both large‑volume contracts and high‑margin small‑batch production, and develop transparent chain‑of‑custody reporting to command premium pricing.
-
For buyers: Implement multi‑tier sourcing with contractual service level metrics, invest in supplier development programs to uplift capability in strategic regions, and adopt hedging or collaborative inventory models to smooth price and availability volatility.
-
For investors/M&A teams: Target regional leaders with strong quality credentials or smaller specialists with proprietary purification technologies that can be scaled through capital and distribution assets.
-
For policy and sustainability officers: Begin capital projects and supplier dialogues that reduce freshwater usage and energy intensity — both regulatory risk and buyer preference are converging on environmental performance.
Methodology & confidence intervals
PW Consulting’s analysis uses a bottoms‑up synthesis of historical consumption (2020–2025), industry audit trails, company disclosures, and proprietary channel checks. The base year is 2025 (USD, revenue unit: Million). Forecasts for 2026–2032 reflect a central scenario at a 5.6% CAGR with alternate upside and downside pathways modeled for policy shifts, major capacity additions, or abrupt clinical demand changes. Where the market shows fragmentation, concentration ratios were computed to assess competitive intensity and acquisition potential.
Conclusion — next steps for executives
Pharmaceutical grade sodium chloride presents a classic strategic choice: treat it as a routine commodity or recognize it as a mission‑critical input whose availability, quality and provenance materially affect product safety, regulatory compliance and economics. PW Consulting’s full report transforms that choice into operationally actionable plans — detailed supplier scorecards, capex calculators, and regulatory readiness templates that executives can deploy immediately. The executive summary here is a preview of the decision‑grade intelligence behind the paywall; for the granular regional, application and company segment data that will shape contracting and investment rounds in 2026, consult the full study.
For detailed analysis of this topic, please visit the official page: Pharmaceutical Grade Sodium Chloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com